

វិចារណកថា
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
បន្ទប់ព័ត៌មាន
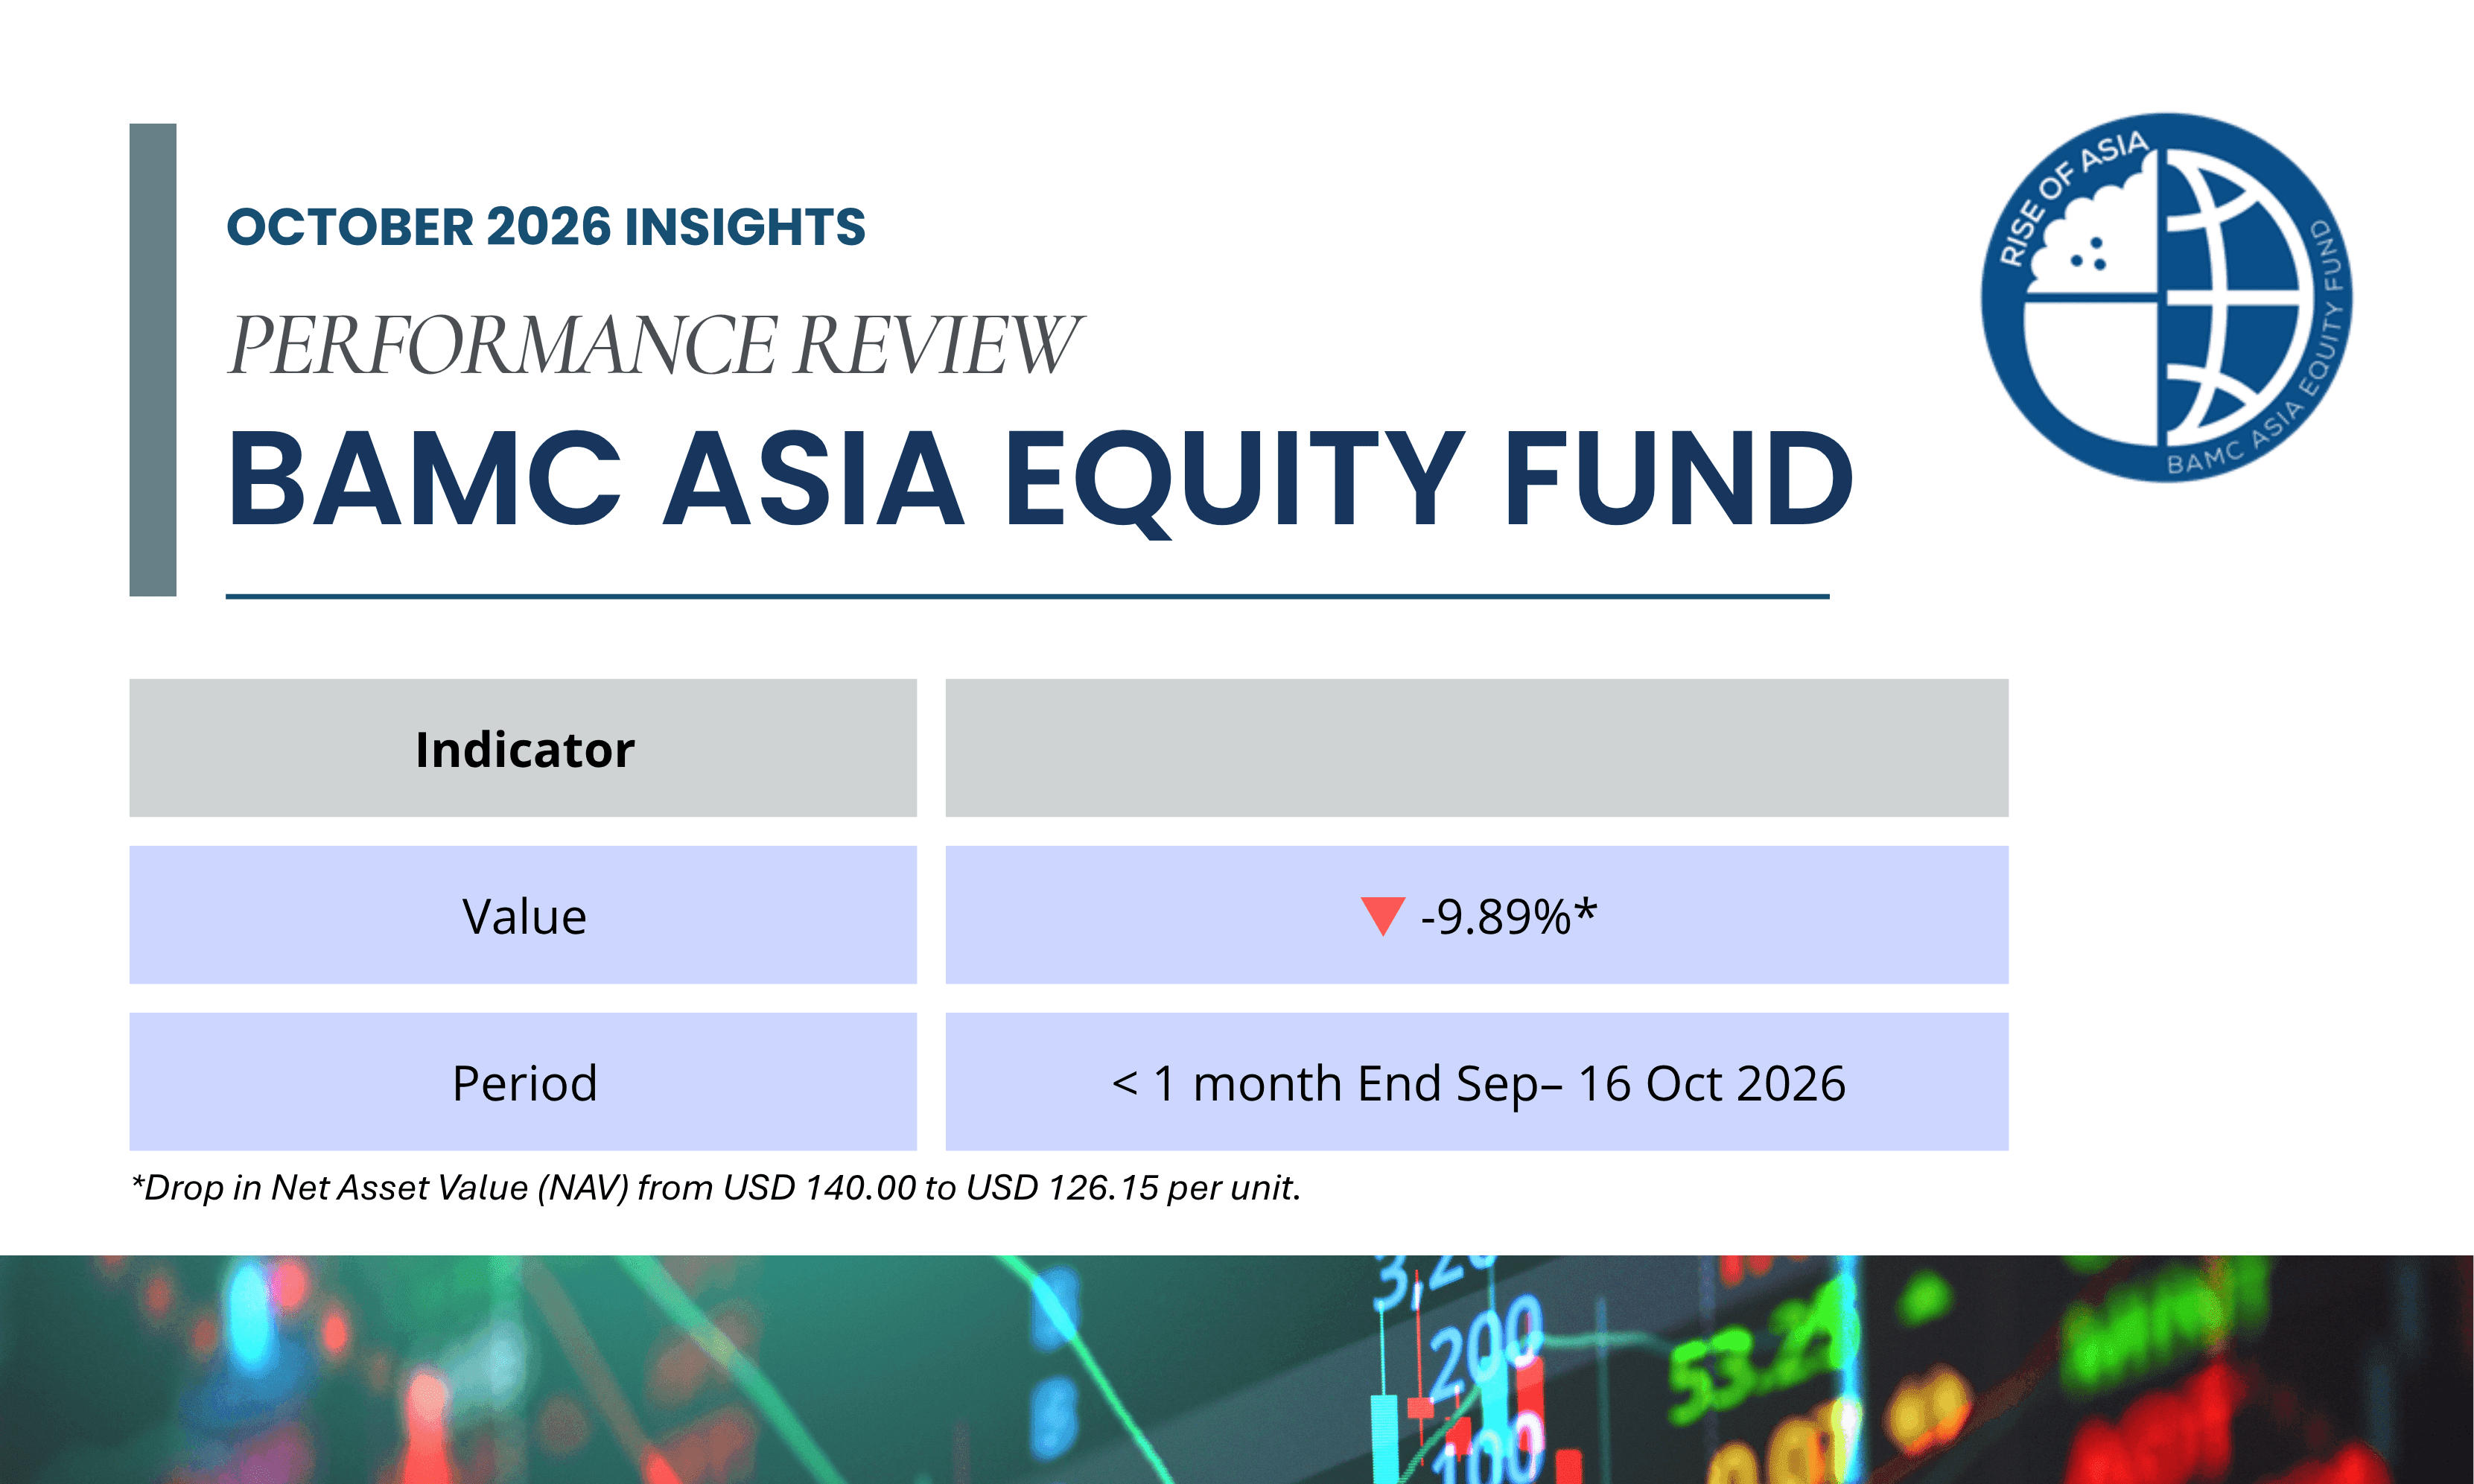
លទ្ធផលមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF Fund) គិតត្រឹមថ្ងៃទី១៦ ខែតុលា ឆ្នាំ២០២៦
ស្ថានភាពទីផ្សារក្នុងខែតុលា ចាប់តាំងពីចុងខែកញ្ញា ទីផ្សារភាគហ៊ុនសកលបានប្រឈមនឹងសម្ពាធពីការកើនឡើងនៃ ថ្លៃដើមរបស់ប្រាក់ កម្ចី ( Borrowing costs) និង ការត្រួតពិនិត្យកាន់តែខ្លាំងឡើងលើ ផលចំណេញពី ការចំណាយ ពាក់ព័ន្ធនឹង បច្ចេកវិទ្យា បញ្ញាសប្បនិម្មិត (AI) ។ អតិផរណានៅក្នុង សហរដ្ឋ អាមេរិកបានកើនឡើងខ្ពស់ លើសពី ការរំពឹងទុក នាំឱ្យមានការ ព្យាករណ៍ថា ធនាគារកណ្តាល សហរដ្ឋ អាមេរិក នឹង រឹតបន្តឹងគោលនយោបាយរូបិយវត្ថុបន្ថែមទៀត បណ្ដាលឱ្យ ប៉ះពាល់ យ៉ាង ខ្លាំងជា ពិសេសលើការវាយតម្លៃភាគហ៊ុននៃវិស័យបច្ចេកវិទ្យា និងវិស័យពាក់កណ្តាលចម្លង ( Semiconductor) ។ តម្លៃប្រេងដែលបន្តកើនឡើងស្ថិតក្នុងកម្រិតខ្ពស់ បានបន្ថែមសម្ពាធ មួយ បន្ថែមទៀតទៅលើក្តីបារម្ភ អំពី អតិផរណា។ ជារួម ទីផ្សារភាគហ៊ុនក្នុងតំបន់អាស៊ីដែល ផ្ដោតខ្លាំង លើវិស័យបច្ចេកវិទ្យា បានទទួលរងនូវសម្ពាធលក់ចេញក្នុងទំហំ ដ៏ច្រើន នៅក្នុងអំឡុងពេលនៃការចុះខ្សោយនៃវិស័យបច្ចេកវិទ្យាសកលក្នុងខែតុលា។ ការវិនិយោគ របស់យើងលើភាគហ៊ុនក្នុងតំបន់អាស៊ី បានឆ្លុះបញ្ចាំងពីការផ្តោតអារម្មណ៍របស់យើងលើឱកាសកំណើនរយៈពេលវែងនៅក្នុ ង តំបន់នេះ។ បម្រែបម្រួលថ្លៃភាគហ៊ុនយ៉ាងគំហុក ក្នុងរយៈពេលខ្លី គឺជាហានិភ័យដែលកើតមានឡើងជាធម្មជាតិក្នុងវិធីសាស្ត្រវិនិយោគ មួយ នេះ ប៉ុន្តែការសម្រេចចិត្តវិនិយោគរបស់យើងនៅតែបន្ត ផ្ដល់អាទិ៍ភាព លើ មូលដ្ឋានគ្រឹះរបស់ក្រុមហ៊ុន និងសក្តានុពលរបស់ក្រុមហ៊ុនទាំងនោះក្នុងការបង្កើតផលចំណេញប្រកបដោយចីរ ភាព ក្នុងរយៈពេលវែង ។ មូលហេតុដែលនាំឱ្យ ផលប័ត្រវិនិយោគ មានការធ្លាក់ចុះ នៅក្នុងបរិបទនេះ កត្តាចម្បងដែលជិះឥទ្ធិពលអវិជ្ជមានដល់លទ្ធផលរបស់មូលនិធិ BAEF គឺការប្រមូលផ្តុំការ វិ និយោគលើភាគហ៊ុនប្រទេសកូរ៉េខាងត្បូង តៃវ៉ាន់ និងភាគហ៊ុនពាក់ព័ន្ធនឹងវិស័យពាក់កណ្តាលចម្លង ( Semiconductor) ដែលភាគហ៊ុនទាំងនេះបូកបញ្ចូលគ្នាមានទំហំ ៣២ , ៣% នៃផលប័ត្រវិនិយោគសរុប និង បានរួមចំណែកប្រមាណ ៤% ក្នុងទំហំនៃតម្លៃដែលបានធ្លាក់ចុះ។ មូលនិធិដែលអាចជួញដូរបាននៅប្រទេសកូរ៉េ ខាងត្បូង និងភាគហ៊ុនក្រុមហ៊ុន Samsung តែពីរមុខនេះ បានទាញទម្លាក់តម្លៃប្រមាណ ២% ទៅហើយ។ ប្រទេសកូរ៉េខាងត្បូង បានរងផលប៉ះពាល់យ៉ាងធ្ងន់ធ្ងរ ជាពិសេសពីការដកដើមទុនចេញ/ការលក់ចេញនូវភាគ ហ៊ុនពាក់ព័ន្ធនឹង បច្ចេកវិទ្យា បញ្ញាសប្បនិម្មិត (AI) ។ នៅថ្ងៃទី១៥ ខែតុលា សន្ទស្សន៍ភាគហ៊ុនគំរូ ( Benchmark index) របស់ប្រទេសនេះ បានធ្លាក់ចុះប្រមាណ ៨%។ ការធ្លាក់ចុះនៃតម្លៃភាគហ៊ុនរបស់ក្រុមហ៊ុន Samsung បានកើតឡើង បើទោះបីជាក្រុមហ៊ុនបានផ្ដល់ការព្យាករណ៍ថា ប្រាក់ចំណេញប្រតិបត្តិការ សម្រាប់ត្រីមាសទីបីនឹងកើនឡើងយ៉ាងច្រើនក៏ដោយ ដែលនេះបង្ហាញថាក្នុងរយៈពេលខ្លីក្តីបារម្ភលើការវាយតម្លៃ ភាគហ៊ុន លក្ខខណ្ឌហិរញ្ញប្បទាន និងការប្រកួតប្រជែង មានទម្ងន់ធ្ងន់ជាងភាពប្រសើរឡើងនៃប្រាក់ចំណេញ។ ការធ្លាក់ចុះនេះត្រូវបានបង្កើនទម្ងន់បន្ថែមទៀត ដោយសារការធ្លាក់ថ្លៃយ៉ាងគំហុកនៃតម្លៃភាគហ៊ុនរបស់ក្រុមហ៊ុន ខ្នាត តូច និងភាគហ៊ុនក្នុងវិស័យហិរញ្ញវត្ថុមួយចំនួននៅប្រទេសសិង្ហបុរី។ ភាគហ៊ុន Addvalue បានធ្លាក់ចុះ ២២ , ៩% , UOB Kay-Hian ធ្លាក់ចុះ ២៥ , ២% និង OCBC ធ្លាក់ចុះ ១០ , ៣%។ ធនាគារ OCBC បានប្រឈមមុខនឹងកត្តាជំរុញអវិជ្ជមានជាក់លាក់មួយ នៅពេលដែលស្ថាប័ន Citi បានទម្លាក់ចំណាត់ថ្នាក់ភាគហ៊ុននេះពី « អព្យាក្រឹត ( Neutral)» មក « លក់ ( Sell)» ដោយលើកឡើងពីហានិភ័យនៃប្រាក់ចំណេញត្រីមាសទីបី សម្ពាធលើគម្លាតអត្រាការប្រាក់សុទ្ធ ( Net interest margins) ដែលកើតចេញពីថ្លៃដើមប្រាក់បញ្ញើខ្ពស់ជាងមុន និងលទ្ធភាពនៃការត្រឡប់មករកកម្រិតធម្មតានៃប្រាក់ចំណូលពីសេវាកម្មគ្រប់គ្រងទ្រព្យសកម្ម ដែលធ្លាប់តែកើន ឡើងយ៉ាងខ្លាំងខុសធម្មតាក្នុងឆមាសទីមួយ។ ចំណែកឯភាពចុះខ្សោយនៃតម្លៃភាគហ៊ុន Addvalue គឺបណ្តាល ម កពីការលក់យកប្រាក់ចំណេញបន្ទាប់ពីតម្លៃភាគហ៊ុននេះបានកើនឡើងយ៉ាងខ្លាំងនាពេលកន្លងមក។ ក្រុមហ៊ុនផ្គត់ផ្គង់ពាក់ព័ន្ធនឹងវិស័យពាក់កណ្តាលចម្លង ( Semiconductor) នៅប្រទេសសិង្ហបុរី ដែលផ្គត់ផ្គង់ដល់ក្រុមហ៊ុនផលិតបន្ទះឈីបធំៗ បានធ្លាក់ចុះតម្លៃយ៉ាងគំហុកជាងក្រុមហ៊ុនផលិតបន្ទះឈីបខ្នាតធំទៅទៀត ដោយភាគហ៊ុន Frencken បានធ្លាក់ចុះ ១៤ , ៩% , UMS ធ្លាក់ចុះ ១៤ , ៨% និង AEM ធ្លាក់ចុះ ៩ , ៩%។ ភាគ ហ៊ុនទាំងនេះបូកបញ្ចូលគ្នាមានទំហំប្រមាណ ១៤% នៃផលប័ត្រវិនិយោគសរុប និងបានទាញទម្លាក់តម្លៃបន្ថែមទៀតប្រមាណ ២ , ៣%។ ដូចគ្នានឹងការលក់ចេញភាគហ៊ុនបច្ចេកវិទ្យាសកលផងដែរ ក្តីបារម្ភកាន់តែ ខ្លាំង លើវដ្តនៃការវិនិយោគលើវិស័យ បច្ចេកវិទ្យា AI បានដាក់សម្ពាធលើចិត្តសាស្ត្រទីផ្សារ លើសពីលទ្ធផលប្រតិបត្តិការដែលបានរាយការណ៍របស់ក្រុមហ៊ុននីមួយៗទៅទៀត។ ក៏មានភាគហ៊ុនមួយចំនួននៅក្នុង ផលប័ត្រវិនិយោគ ទទួលបានផលចំណេញ ប៉ុន្ដែវា មិនមានទំហំគ្រប់គ្រាន់ដើម្បីទប់ទល់នឹងការខាតបង់ទាំងនោះឡើយ។ ហេតុអ្វីបានជាយើងនៅតែបន្ដរក្សាការវិនិយោគរបស់យើងលើភាគហ៊ុនទាំងនេះ? ទោះបីជាមានភាពចុះខ្សោយនាពេលថ្មីៗនេះក៏ដោយ យើងនៅតែបន្តរក្សាទុកនូវភាគហ៊ុនទាំងនេះ ពីព្រោះកត្តា ជំរុញប្រាក់ចំណេញជាមូលដ្ឋាននៅតែមានភាពប្រាកដនិយម និងត្រូវគ្នានឹងរយៈពេលនៃការវិនិយោគរបស់យើ ង។ ការលក់ចេញយ៉ាងគំហុកនេះ បានទាញទម្លាក់តម្លៃភាគហ៊ុនឱ្យធ្លាក់ចុះខ្លាំងជាងលក្ខខណ្ឌវិនិយោគពិតប្រាកដក្នុងរយៈពេលមធ្យម ទៅរយៈពេលវែង។ នៅក្នុងវិស័យពាក់កណ្តាលចម្លង ( Semiconductor) ការកែតម្រូវថ្លៃនេះបានកើតឡើងក្នុងពេលដំណាលគ្នានឹងការកើនឡើងជាបន្តបន្ទាប់ នៃតម្រូវការលើសមត្ថភាព គណនារបស់បច្ចេកវិទ្យា AI (AI compute) ។ របាយការណ៍ចុងក្រោយ និងការបញ្ជាក់ការព្យាករណ៍របស់ក្រុមហ៊ុន TSMC បានចង្អុលបង្ហាញពីតម្រូវការស្ថិតស្ថេរលើបន្ទះឈីបកម្រិតខ្ពស់ ខណៈដែលការព្យាករណ៍ប្រាក់ចំណេញរបស់ក្រុមហ៊ុន Samsung ឆ្លុះបញ្ចាំងពីការលក់ និងតម្លៃបន្ទះអង្គចងចាំ ( Memory chips) ដ៏រឹងមាំជាងមុន។ ការវិវត្តទាំងនេះ ទ្រទ្រង់ដល់ការរក្សាទុកការវិនិយោគនៅក្នុងវិស័យនេះ ទោះ ជាយ៉ាងណាក៏ដោយ យើង ទទួលស្គាល់ថា ប្រតិបត្តិការអាជីវកម្មដ៏រឹងមាំ មិនអាចលុបបំបាត់ហានិភ័យនៃការវាយតម្លៃភាគហ៊ុន ឬលទ្ធភាពនៃបម្រែបម្រួលតម្លៃភាគហ៊ុន យ៉ាងគំហុកនោះឡើយ ។ ភាគហ៊ុន ក្នុង វិស័យពាក់កណ្តាលចម្លង ( Semiconductor) របស់យើងនៅប្រទេសសិង្ហបុរី ត្រូវបានបំបែក លើផ្នែកផ្សេងៗគ្នានៃវដ្តវិនិយោគនេះ។ ក្រុមហ៊ុន UMS ទទួលបានផលប្រយោជន៍ពីតម្រូវការឧបករណ៍ ធន់ធ្ងន់ និងការកើនឡើងនៃប្រតិបត្តិការលើបច្ចេកវិទ្យាវេចខ្ចប់បន្ទះឈីបកម្រិតខ្ពស់ ( Advanced packaging) រីឯ ក្រុមហ៊ុន AEM ផ្តល់នូវការចូលរួមក្នុងដំណើរការធ្វើតេស្តបន្ទះឈីបដែលមានភាពស្មុគស្មាញខ្លាំង ខណៈដែលក្រុមហ៊ុន Frencken ផ្តល់នូវ ពិពិធកម្មដោយផ្ដោតលើ ផ្នែកផលិត។ ហេតុផលនៃការរក្សាទុកនូវភាគហ៊ុនទាំងនេះ គឺផ្អែក លើប្រាក់ចំណេញរំពឹងទុកនាពេលអនាគតរបស់ពួកគេ ក្នុងពេលដែលអតិថិជនវិនិយោគបន្ថែមលើសមត្ថភាពផ លិត និងរចនាសម្ព័ន្ធបន្ទះឈីបកម្រិតខ្ពស់ ជាជាងការរំពឹងទុកថាភាគហ៊ុនពាក់ព័ន្ធនឹងវិស័យពាក់កណ្តាល ចម្លង (Semiconductor) ទាំងអស់នឹងងើបឡើងវិញក្នុងពេលដំណាលគ្នានោះឡើយ។ សម្រាប់ភាគហ៊ុននៅក្នុងវិស័យហិរញ្ញវត្ថុ លទ្ធផលប្រតិបត្តិការនាពេលថ្មីៗនេះ ផ្តល់នូវមូលដ្ឋានគ្រឹះក្នុងការបែងចែកឱ្យច្បាស់រវាងភាពចុះខ្សោយនៃតម្លៃភាគហ៊ុន និងការធ្លាក់ចុះនៃគុណភាពអាជីវកម្ម។ ប្រាក់ចំណូលពីសេវាកម្មគ្រប់គ្រងទ្រព្យសកម្ម និងប្រាក់ចំណូលមិនមែនការប្រាក់ផ្សេងទៀតរបស់ធនាគារ OCBC បានជួយទប់ទល់នឹងសម្ពាធលើគម្លាតអត្រាការប្រាក់កម្ចី ( Lending margins) ខណៈដែលស្ថានភាពដើមទុនរបស់ខ្លួននៅតែបន្តទ្រទ្រង់ដល់កំណើនអាជីវកម្ម និងការបែងចែកផលចំណេញ។ ក្រុមហ៊ុន UOB Kay Hian បានរាយការណ៍ពីប្រាក់ចំណេញឆមាសទីមួយកើនឡើងយ៉ាងខ្លាំង ដែលទ្រទ្រង់ដោយសកម្មភាពជួញដូរកាន់តែសកម្ម ប្រាក់ចំណូលពីកម្រៃជើងសារ និងប្រាក់ចំណូលពីការប្រាក់។ យើងនៅតែបន្តរក្សាការវិនិយោគលើប្រភពប្រាក់ចំណេញទាំងនេះ ខណៈដែលទទួលស្គាល់ថា ប្រាក់ចំណូលពាក់ព័ន្ធនឹងការគ្រប់គ្រងទ្រព្យសកម្ម និងសកម្មភាពឈ្មួញជើងសារ គឺមានភាពប្រែប្រួលងាយរងគ្រោះតាមស្ថានភាពទីផ្សារ ហើយអត្រាកំណើននាពេលថ្មីៗនេះ អាចនឹងមិនបន្តកើតមានក្នុងកម្រិតដដែលនោះឡើយ។ យើងនៅតែបន្តរក្សាការវិនិយោគលើក្រុមហ៊ុន Addvalue ដោយសារកំណើនរយៈពេលវែងនៃប្រព័ន្ធភ្ជាប់ទំនាក់ទំនងតាមផ្កាយរណប និងហេដ្ឋារចនាសម្ព័ន្ធអវកាស។ ភាពចុះខ្សោយនៃតម្លៃភាគហ៊ុននាពេលថ្មីៗនេះ ហាក់ដូចជាឆ្លុះបញ្ចាំងភាគខ្លះពីការលក់យកប្រាក់ចំណេញ បន្ទាប់ពីតម្លៃភាគហ៊ុនបានហក់ឡើងយ៉ាងខ្លាំង ខណៈដែលការបញ្ជាទិញជាបន្តបន្ទាប់ បានទ្រទ្រង់ដល់ទស្សនវិស័យកំណើនជាមូលដ្ឋានរបស់ក្រុមហ៊ុន។ នៅក្នុងខែកញ្ញា Addvalue បានប្រកាសពីការទទួលបានការបញ្ជាទិញថ្មីៗក្នុងទំហំទឹកប្រាក់ ១៥.០០០.០០០ (ដប់ប្រាំលាន) ដុល្លារអាមេរិក លើអាជីវកម្មប្រព័ន្ធភ្ជាប់ទំនាក់ទំនងអវកាស និងវិទ្យុឌីជីថលកម្រិតខ្ពស់របស់ខ្លួន ដែលធ្វើឱ្យបញ្ជីការបញ្ជាទិញដែលមិនទាន់សម្រេច ( Order book) កើនឡើងដល់ ២០ . ២០០.០០០ (ម្ភៃ លាន ពីររយពាន់ ) ដុល្លារអាមេរិក។ ការបំប្លែងការបញ្ជាទិញទាំងនេះឱ្យទៅជាប្រាក់ចំណេញ និងលំហូរសាច់ប្រាក់ នៅតែជាចំណុចស្នូលនៃលក្ខខណ្ឌវិនិយោគរបស់យើង។ សរុបរួមមក យើងនៅតែបន្តមានភាពប្រុងប្រយ័ត្ន និងជ្រើសរើសយ៉ាងសម្រិតសម្រាំង ហើយយើងមើលឃើញថាការធ្លាក់ចុះនេះ គឺជាឱកាសដ៏មានសក្តានុពលក្នុងការទិញបន្ថែមលើភាគហ៊ុនដែលមានស្រាប់ ជាជាង អង្គុយរង់ចាំមើលស្ថានភាពទីផ្សារដោយមិនធ្វើអ្វីទាំងអស់។ ការបន្តកាន់កាប់ភាគហ៊ុន នៅតែត្រូវផ្ដោតលើ មូលដ្ឋាន គ្រឹះរបស់ក្រុមហ៊ុន ការវាយតម្លៃភាគហ៊ុនក្នុងកម្រិតដែលអាចទទួលយកបាន និងកំណើនប្រាក់ចំណេញពិតប្រាកដ។ អ្វីដែលយើងនឹងធ្វើបន្ដ ជំហានប ន្ទាប់ យើងមានបំណងបង្កើនការវិនិយោគលើក្រុមហ៊ុន ដែលមានមូនធនទីផ្សារ ធំ ប្រកបដោយ គុណភាពខ្ពស់ និងក្រុមហ៊ុនឈានមុខដែលមានស្ថិរភាពរឹងមាំ ( Blue-chip companies) ដើម្បីពង្រឹងភាពធន់នៃផលប័ត្រវិនិយោគ នៅក្នុងអំឡុងពេលដែលទីផ្សារបន្តមានភាពមិនទៀងទាត់។ យើងនឹងផ្តល់ អាទិ៍ ភាពដល់អាជីវកម្មទាំងឡាយណាដែលមាន របាយការណ៍តុល្យការ រឹងមាំ ប្រាក់ចំណូល មានស្ថិរភាព និងលំហូរសាច់ប្រាក់ប្រកបដោយចីរភាពព្រមទាំងមានប្រៀប ក្នុង ប្រកួតប្រជែងប្រកបដោយនិរន្តរភាព។ ប្រសិនបើទីផ្សារនៅតែ បន្ដធ្លាក់ចុះ បន្ថែមទៀត វានឹងផ្តល់ឱកាសឱ្យយើងក្នុងការបង្កើនទំហំវិនិយោគនៅតម្លៃល្អ ខណៈពេលដែលយើងនៅតែប្រកាន់ខ្ជាប់នូវវិធីសាស្ត្រវិនិយោគប្រកបដោយវិន័យលើការវាយតម្លៃភាគហ៊ុន។ ការ បដិសេធ ៖ ឯកសារនេះត្រូវបានចេញផ្សាយក្នុងគោលបំណងផ្តល់ព័ត៌មាន និងបង្កើនការយល់ដឹងរបស់វិនិយោគិនតែប៉ុណ្ណោះ ដើម្បីពន្យល់ពីកត្តានានាដែលរួមចំណែកដល់ការប្រែប្រួលនៃតម្លៃទ្រព្យសកម្មសុទ្ធ ( NAV) របស់មូលនិធិ BAEF ។ ឯកសារនេះមិនមែនការណែនាំឱ្យវិនិយោគ ការផ្តល់យោបល់វិនិយោគ ការផ្តល់ជូន ឬការដេញថ្លៃដើម្បីទិញ-លក់ ឬកាន់កាប់ឯកតាមូលនិធិរបស់មូលនិធិ BAEF នោះឡើយ។ ព័ត៌មានដែលបានផ្តល់ជូននៅក្នុងឯកសារនេះ មិនគួរត្រូវបានយកមកធ្វើជាមូលដ្ឋានគ្រឹះតែមួយគត់សម្រាប់ការសម្រេចចិត្តវិនិយោគណាមួយឡើយ ហើយក៏មិនមែនជាការធានាចំពោះលទ្ធផលវិនិយោគនាពេលអនាគតនោះដែរ។ វិនិយោគិនគួរតែផ្អែក លើឯកសារផ្តល់ជូនជាផ្លូវការនិងឯកសារផ្ដល់ព័ត៌មាន ហើយវាយតម្លៃដោយប្រុងប្រយ័ត្នលើគោលដៅវិនិយោគផ្ទាល់ខ្លួន និងកម្រិតហានិភ័យដែលខ្លួនអាចទទួលយកបាន មុនពេលធ្វើការសម្រេចចិត្តវិនិយោគណាមួយ។
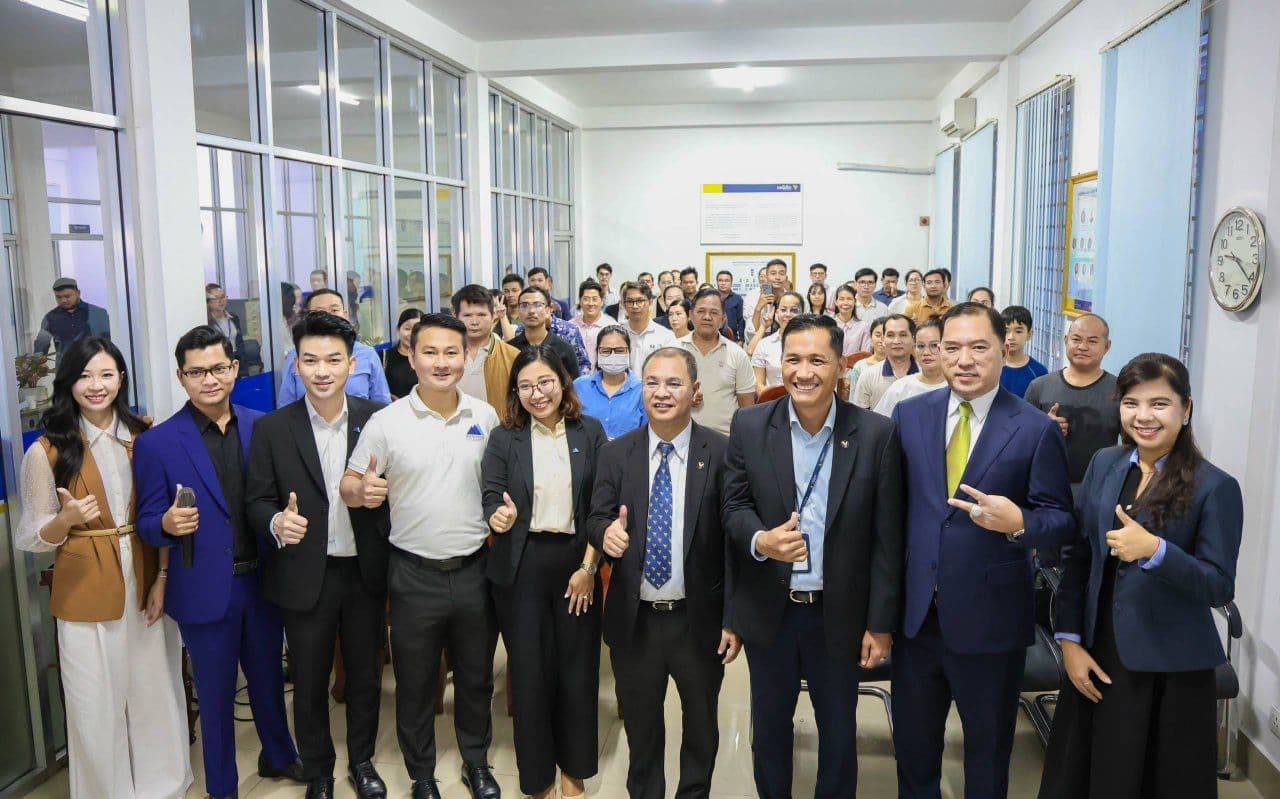
សិក្ខាសាលាអំពីការវិនិយោគមូលបត្រ ក្នុងកម្មវិធីរ៉ូដសូ លើកទី៣ នៅខណ្ឌមានជ័យ
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុនមូលបត្រ អេស៊ីលីដា ម.ក និងសាខាក្រុមហ៊ុនក្នុងស្រុកធនាគារអេស៊ីលីដា ភីអិលស៊ី (ខណ្ឌមានជ័យ-សង្កាត់បឹងទំពុនទី១) បានរៀបចំដោយជោគជ័យនូវសិក្ខាសាលាស្តីពី “ឱកាសមាសនៃការវិនិយោគមូលបត្រ” ដែលជាផ្នែកមួយនៃដំណើរការផ្សព្វផ្សាយកម្មវិធីរ៉ូដសូ លើកទី៣។ សិក្ខាសាលានេះបានរៀបចំឡើងនៅសាលប្រជុំរបស់សាខាក្រុមហ៊ុនក្នុងស្រុកធនាគារអេស៊ីលីដា ភីអិលស៊ី (ខណ្ឌមានជ័យ-សង្កាត់បឹងទំពុនទី១) កាលពីព្រឹកថ្ងៃទី០៥ ខែកញ្ញា ឆ្នាំ២០២៦។ សិក្ខាសាលានេះរៀបចំឡើងក្នុងគោលបំណងលើកកម្ពស់ការយល់ដឹងអំពីការវិនិយោគក្នុងទីផ្សារមូលធននិងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ដែលជាគម្រោងវិនិយោគរួម (CIS)។ យើងខ្ញុំសូមថ្លែងអំណរគុណយ៉ាងជ្រាលជ្រៅចំពោះដៃគូសហការនិងសិក្ខាកាមទាំងអស់ ដែលបានចូលរួមនិងគាំទ្រដល់ការរៀបចំសិក្ខាសាលានេះប្រកបដោយជោគជ័យ។ សូមថ្លែងអំណរគុណជាពិសេសចំពោះលោក សុខ ច័ន្ទតុលា អនុប្រធានផ្នែកលក់និងទីផ្សារ នៃក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ដែលបានចូលរួមជាវាគ្មិនសម្រាប់បទបង្ហាញដ៏មានអត្ថន័យនិងខ្លឹមសារយ៉ាងមានសារៈសំខាន់អំពី “មូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF)”។ យើងខ្ញុំរីករាយនិងស្វាគមន៍អ្នកទាំងអស់គ្នាក្នុងកម្មវិធីបន្ទាប់។
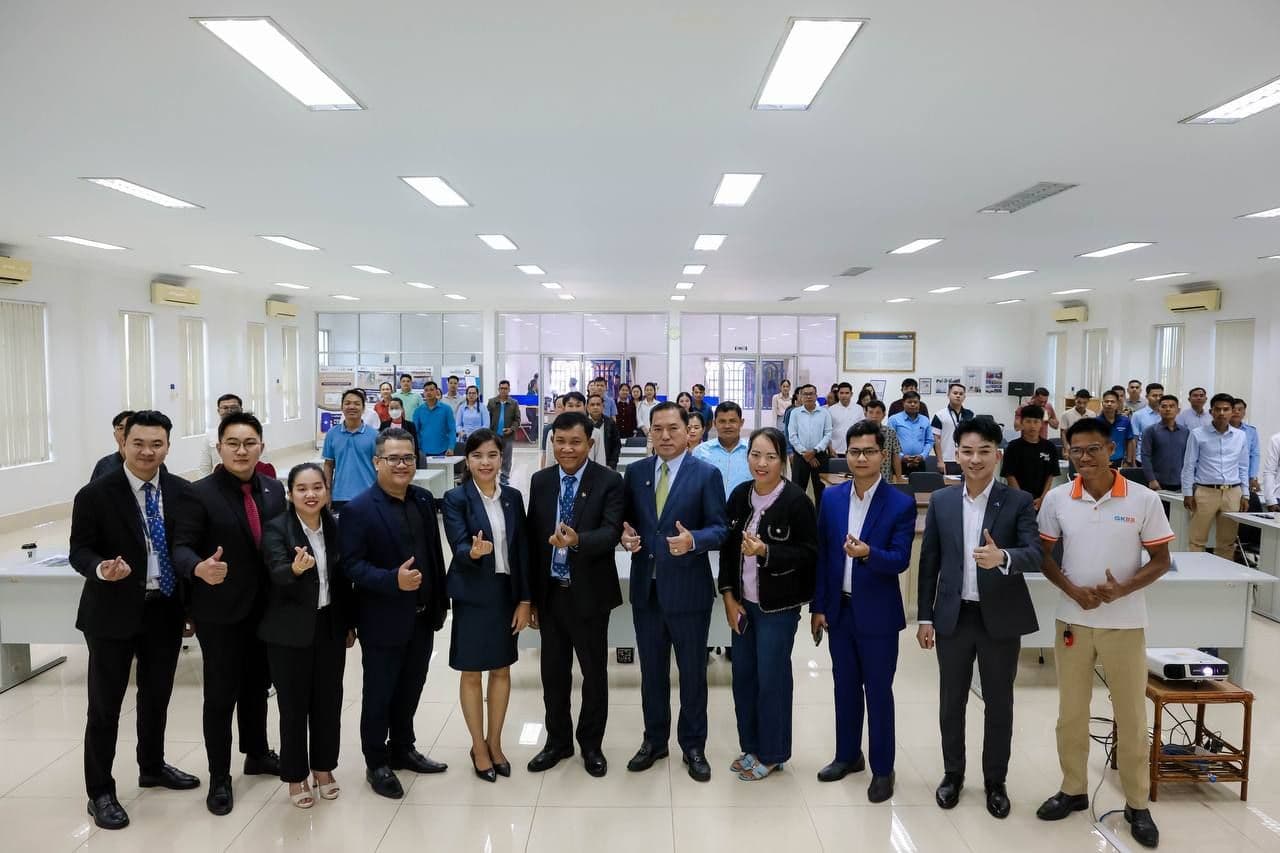
សិក្ខាសាលាអំពីវិនិយោគមូលបត្រ ក្នុងកម្មវិធីរ៉ូដសូ លើកទី៣ នៅខេត្តស្វាយរៀង
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុនមូលបត្រ អេស៊ីលីដា ម.ក សាខាក្រុមហ៊ុនក្នុងស្រុកធនាគារអេស៊ីលីដា ភីអិលស៊ី (ខេត្តស្វាយរៀង) បានរៀបចំដោយជោគជ័យនូវសិក្ខាសាលាស្តីពី “ឱកាសមាសនៃការវិនិយោគមូលបត្រ” ដែលជាផ្នែកមួយនៃដំណើរការផ្សព្វផ្សាយកម្មវិធីរ៉ូដសូ លើកទី៣។ សិក្ខាសាលានេះបានរៀបចំឡើងនៅសាលប្រជុំរបស់សាខាក្រុមហ៊ុនក្នុងស្រុកធនាគារអេស៊ីលីដា ភីអិលស៊ី (ខេត្តស្វាយរៀង) កាលពីព្រឹកថ្ងៃទី២២ ខែសីហា ឆ្នាំ២០២៦។ សិក្ខាសាលានេះរៀបចំឡើងក្នុងគោលបំណងលើកកម្ពស់ការយល់ដឹងអំពីការវិនិយោគក្នុងទីផ្សារមូលធននិងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ដែលជាគម្រោងវិនិយោគរួម (CIS)។ យើងខ្ញុំសូមថ្លែងអំណរគុណយ៉ាងជ្រាលជ្រៅចំពោះដៃគូសហការនិងសិក្ខាកាមទាំងអស់ ដែលបានចូលរួមនិងគាំទ្រដល់ការរៀបចំសិក្ខាសាលានេះប្រកបដោយជោគជ័យ។ សូមថ្លែងអំណរគុណជាពិសេសចំពោះ លោក តាំង ហយ បុគ្គលិកផ្នែកច្បាប់និងអនុលោមភាព នៃក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ដែលបានចូលរួមជាវាគ្មិនសម្រាប់បទបង្ហាញដ៏មានអត្ថន័យនិងខ្លឹមសារយ៉ាងមានសារៈសំខាន់អំពី “តម្លៃនិងអត្ថប្រយោជន៍នៃការវិនិយោគក្នុងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ”។ យើងខ្ញុំរីករាយនិងស្វាគមន៍អ្នកទាំងអស់គ្នាក្នុងកម្មវិធីបន្ទាប់។
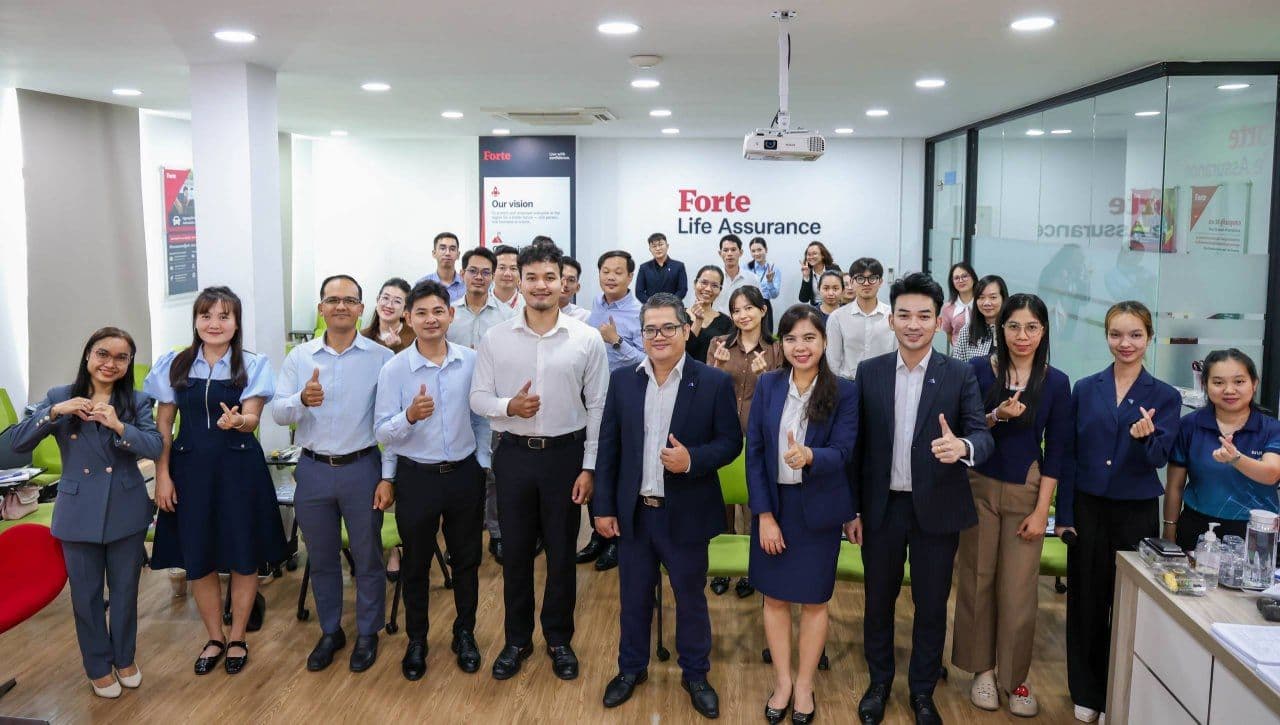
សិក្ខាសាលាវិនិយោគមូលបត្រសម្រាប់ថ្នាក់ដឹកនាំ និងបុគ្គលិកក្រុមហ៊ុន ហ្វតតេ
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុន មូលបត្រ អេស៊ីលីដា ម.ក បានរៀបចំដោយជោគជ័យនូវសិក្ខាសាលាស្តីពី “ឱកាសមាសនៃការវិនិយោគមូលបត្រ” សម្រាប់ថ្នាក់ដឹកនាំ និងបុគ្គលិករបស់ ក្រុមហ៊ុន ហ្វតតេ អ៊ិនសួរឹនស៍ (ខេមបូឌា) ម.ក និងក្រុមហ៊ុន ហ្វតតេ ឡាយហ្វ៍ អឹសួរ៉ិនស៍ (ខេមបូឌា) ម.ក នៅថ្ងៃទី ១៩ ខែសីហា ឆ្នាំ២០២៦ នៅការិយាល័យ ហ្វតតេ អគារ One Park Tower។ សិក្ខាសាលានេះបានផ្តល់ជូនអ្នកចូលរួមនូវចំណេះដឹងដ៏មានតម្លៃអំពី មូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ដែលរួមមានលក្ខណៈសំខាន់របស់មូលនិធិ យុទ្ធសាស្ត្រវិនិយោគ និងឱកាសវិនិយោគតាមរយៈមូលនិធិដែលគ្រប់គ្រងដោយក្រុមហ៊ុនគ្រប់គ្រងមូលនិធិដែលមានវិជ្ជាជីវៈ និងទទួលបានការអនុញ្ញាត ព្រមទាំងស្ថិតក្រោមការគ្រប់គ្រងរបស់ និយ័តករមូលបត្រកម្ពុជា (ន.ម.ក.)។ ក្នុងកម្មវិធីសិក្ខាសាលានេះ លោក សុខ ច័ន្ទតុលា អនុប្រធានផ្នែកលក់ និងទីផ្សារ នៃក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានធ្វើបទបង្ហាញក្រោមប្រធានបទ “តម្លៃនិងអត្ថប្រយោជន៍នៃការវិនិយោគក្នុងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF)” ដោយចែករំលែកចំណេះដឹងអំពីឱកាសវិនិយោគ និងអត្ថប្រយោជន៍នៃ BAEF ដែលជាផ្នែកមួយនៃការរីកចម្រើននៃវិស័យមូលបត្រនៅកម្ពុជា។ សិក្ខាសាលានេះជាជំហានសំខាន់មួយបន្ថែមទៀតក្រោម កិច្ចសហការយុទ្ធសាស្ត្ររវាង ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ក្រុមហ៊ុន មូលបត្រ អេស៊ីលីដា ម.ក ក្រុមហ៊ុន ហ្វតតេ អ៊ិនសួរឹនស៍ (ខេមបូឌា) ម.ក និងក្រុមហ៊ុន ហ្វតតេ ឡាយហ្វ៍ អឹសួរ៉ិនស៍ (ខេមបូឌា) ម.ក ក្នុងគោលបំណងលើកកម្ពស់ការយល់ដឹងផ្នែកវិនិយោគ ពង្រឹងកិច្ចសហការរវាងភាគីពាក់ព័ន្ធ និងបង្កើតឱកាសសម្រាប់ការរីកចម្រើននៃកិច្ចសហការអាជីវកម្មនាពេលអនាគត។
សិក្ខាសាលាវិនិយោគមូលបត្រ ក្នុងកម្មវិធីរ៉ូដសូ លើកទី៣ នៅខេត្តសៀមរាប
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុនមូលបត្រ អេស៊ីលីដា ម.ក សាខាក្រុមហ៊ុនក្នុងស្រុកធនាគារអេស៊ីលីដា ភីអិលស៊ី (ក្រុងសៀមរាប សង្កាត់ស្លក្រាម) និងសាខាក្រុមហ៊ុនក្នុងស្រុកធនាគារអេស៊ីលីដា ភីអិលស៊ី (ក្រុងសៀមរាប សង្កាត់ស្វាយដង្គំ) បានរៀបចំដោយជោគជ័យនូវសិក្ខាសាលាស្តីពី “ឱកាសមាសនៃការវិនិយោគមូលបត្រ” ដែលជាផ្នែកមួយនៃដំណើរការផ្សព្វផ្សាយកម្មវិធីរ៉ូដសូ លើកទី៣។ សិក្ខាសាលានេះបានរៀបចំឡើងនៅសាលប្រជុំរបស់សាខាក្រុមហ៊ុនក្នុងស្រុកធនាគារអេស៊ីលីដា ភីអិលស៊ី (ក្រុងសៀមរាប សង្កាត់ស្លក្រាម) កាលពីព្រឹកថ្ងៃទី១៥ ខែសីហា ឆ្នាំ២០២៦។ សិក្ខាសាលានេះរៀបចំឡើងក្នុងគោលបំណងលើកកម្ពស់ការយល់ដឹងអំពីការវិនិយោគក្នុងទីផ្សារមូលធននិងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ដែលជាគម្រោងវិនិយោគរួម (CIS)។ យើងខ្ញុំសូមថ្លែងអំណរគុណយ៉ាងជ្រាលជ្រៅចំពោះដៃគូសហការនិងសិក្ខាកាមទាំងអស់ ដែលបានចូលរួមនិងគាំទ្រដល់ការរៀបចំសិក្ខាសាលានេះប្រកបដោយជោគជ័យ។ សូមថ្លែងអំណរគុណជាពិសេសចំពោះលោក សុខ ច័ន្ទតុលា អនុប្រធានផ្នែកលក់និងទីផ្សារ នៃក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ដែលបានចូលរួមជាវាគ្មិនសម្រាប់បទបង្ហាញដ៏មានអត្ថន័យនិងខ្លឹមសារយ៉ាងមានសារៈសំខាន់អំពី “តម្លៃនិងអត្ថប្រយោជន៍នៃការវិនិយោគក្នុងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ”។ យើងខ្ញុំរីករាយនិងស្វាគមន៍អ្នកទាំងអស់គ្នាក្នុងកម្មវិធីបន្ទាប់។
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុន មូលបត្រ អេស៊ីលីដា ម.ក បានរៀបចំសិក្ខាសាលាសម្រាប់ថ្នាក់ដឹកនាំ និងបុគ្គលិករបស់ ក្រុមហ៊ុន ហ្វតតេ
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុន មូលបត្រ អេស៊ីលីដា ម.ក បានរៀបចំដោយជោគជ័យនូវសិក្ខាសាលាស្តីពី “ឱកាសមាសនៃការវិនិយោគមូលបត្រ” សម្រាប់ថ្នាក់ដឹកនាំ និងបុគ្គលិករបស់ ក្រុមហ៊ុន ហ្វតតេ អ៊ិនសួរឹនស៍ (ខេមបូឌា) ម.ក និងក្រុមហ៊ុន ហ្វតតេ ឡាយហ្វ៍ អឹសួរ៉ិនស៍ (ខេមបូឌា) ម.ក នៅថ្ងៃទី ១២ ខែសីហា ឆ្នាំ២០២៦ នៅការិយាល័យ ហ្វតតេ អគារ One Park Tower។ សិក្ខាសាលានេះបានផ្តល់ជូនអ្នកចូលរួមនូវចំណេះដឹងដ៏មានតម្លៃអំពី មូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ដែលរួមមានលក្ខណៈសំខាន់របស់មូលនិធិ យុទ្ធសាស្ត្រវិនិយោគ និងឱកាសវិនិយោគតាមរយៈមូលនិធិដែលគ្រប់គ្រងដោយក្រុមហ៊ុនគ្រប់គ្រងមូលនិធិដែលមានវិជ្ជាជីវៈ និងទទួលបានការអនុញ្ញាត ព្រមទាំងស្ថិតក្រោមការគ្រប់គ្រងរបស់ និយ័តករមូលបត្រកម្ពុជា (ន.ម.ក.)។ ក្នុងកម្មវិធីសិក្ខាសាលានេះ លោក សុខ ច័ន្ទតុលា អនុប្រធានផ្នែកលក់ និងទីផ្សារ នៃក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានធ្វើបទបង្ហាញក្រោមប្រធានបទ “តម្លៃនិងអត្ថប្រយោជន៍នៃការវិនិយោគក្នុងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF)” ដោយចែករំលែកចំណេះដឹងអំពីឱកាសវិនិយោគ និងអត្ថប្រយោជន៍នៃ BAEF ដែលជាផ្នែកមួយនៃការរីកចម្រើននៃវិស័យមូលបត្រនៅកម្ពុជា។ សិក្ខាសាលានេះជាជំហានសំខាន់មួយបន្ថែមទៀតក្រោម កិច្ចសហការយុទ្ធសាស្ត្ររវាង ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ក្រុមហ៊ុន មូលបត្រ អេស៊ីលីដា ម.ក ក្រុមហ៊ុន ហ្វតតេ អ៊ិនសួរឹនស៍ (ខេមបូឌា) ម.ក និងក្រុមហ៊ុន ហ្វតតេ ឡាយហ្វ៍ អឹសួរ៉ិនស៍ (ខេមបូឌា) ម.ក ក្នុងគោលបំណងលើកកម្ពស់ការយល់ដឹងផ្នែកវិនិយោគ ពង្រឹងកិច្ចសហការរវាងភាគីពាក់ព័ន្ធ និងបង្កើតឱកាសសម្រាប់ការរីកចម្រើននៃកិច្ចសហការអាជីវកម្មនាពេលអនាគត។
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុន មូលបត្រ អេស៊ីលីដា ម.ក រៀបចំសិក្ខាសាលា “ឱកាសមាសនៃការវិនិយោគមូលបត្រ”
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុន មូលបត្រ អេស៊ីលីដា ម.ក បានរៀបចំដោយជោគជ័យនូវសិក្ខាសាលាស្តីពី “ឱកាសមាសនៃការវិនិយោគមូលបត្រ” សម្រាប់ថ្នាក់ដឹកនាំ និងបុគ្គលិករបស់ ក្រុមហ៊ុន ហ្វតតេ អ៊ិនសួរឹនស៍ (ខេមបូឌា) ម.ក និងក្រុមហ៊ុន ហ្វតតេ ឡាយហ្វ៍ អឹសួរ៉ិនស៍ (ខេមបូឌា) ម.ក នៅថ្ងៃទី ០៦ ខែសីហា ឆ្នាំ២០២៦ នៅការិយាល័យ ហ្វតតេ អគារ One Park Tower។ សិក្ខាសាលានេះបានផ្តល់ជូនអ្នកចូលរួមនូវចំណេះដឹងដ៏មានតម្លៃអំពី មូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ដែលរួមមានលក្ខណៈសំខាន់របស់មូលនិធិ យុទ្ធសាស្ត្រវិនិយោគ និងឱកាសវិនិយោគតាមរយៈមូលនិធិដែលគ្រប់គ្រងដោយក្រុមហ៊ុនគ្រប់គ្រងមូលនិធិដែលមានវិជ្ជាជីវៈ និងទទួលបានការអនុញ្ញាត ព្រមទាំងស្ថិតក្រោមការគ្រប់គ្រងរបស់ និយ័តករមូលបត្រកម្ពុជា (ន.ម.ក.)។ ក្នុងកម្មវិធីសិក្ខាសាលានេះ លោក សុខ ច័ន្ទតុលា អនុប្រធានផ្នែកលក់ និងទីផ្សារ នៃក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានធ្វើបទបង្ហាញក្រោមប្រធានបទ “តម្លៃនិងអត្ថប្រយោជន៍នៃការវិនិយោគក្នុងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF)” ដោយចែករំលែកចំណេះដឹងអំពីឱកាសវិនិយោគ និងអត្ថប្រយោជន៍នៃ BAEF ដែលជាផ្នែកមួយនៃការរីកចម្រើននៃវិស័យមូលបត្រនៅកម្ពុជា។ សិក្ខាសាលានេះជាជំហានសំខាន់មួយបន្ថែមទៀតក្រោម កិច្ចសហការយុទ្ធសាស្ត្ររវាង ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ក្រុមហ៊ុន មូលបត្រ អេស៊ីលីដា ម.ក ក្រុមហ៊ុន ហ្វតតេ អ៊ិនសួរឹនស៍ (ខេមបូឌា) ម.ក និងក្រុមហ៊ុន ហ្វតតេ ឡាយហ្វ៍ អឹសួរ៉ិនស៍ (ខេមបូឌា) ម.ក ក្នុងគោលបំណងលើកកម្ពស់ការយល់ដឹងផ្នែកវិនិយោគ ពង្រឹងកិច្ចសហការរវាងភាគីពាក់ព័ន្ធ និងបង្កើតឱកាសសម្រាប់ការរីកចម្រើននៃកិច្ចសហការអាជីវកម្មនាពេលអនាគត។
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ចូលរួមវេទិកា “Trust Forum 2026”
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក មានកិត្តិយសបានចូលរួមវេទិកា “បរធនបាលកិច្ច ឆ្នាំ២០២៦” ក្រោមមូលបទ “បរធនបាលកិច្ចក្នុងជវភាពនៃប្រព័ន្ធតួអង្គតែមួយ និងសមិទ្ធផលក្នុងរយៈពេល ៥ ឆ្នាំ” ក្រោមអធិបតីភាពដ៏ខ្ពង់ខ្ពស់របស់ ឯកឧត្ដមអគ្គបណ្ឌិតសភាចារ្យ អូន ព័ន្ធមុនីរ័ត្ន ឧបនាយករដ្ឋមន្រ្តី រដ្ឋមន្រ្តីក្រសួងសេដ្ឋកិច្ចនិងហិរញ្ញវត្ថុ និងជាប្រធានក្រុមប្រឹក្សាអាជ្ញាធរសេវាហិរញ្ញវត្ថុមិនមែនធនាគារ ដែលរៀបចំឡើងដោយនិយ័តករបរធនបាលកិច្ច កាលពីថ្ងៃទី៤ ខែកក្កដា ឆ្នាំ២០២៦ នៅសណ្ឋាគារ សុខា ភ្នំពេញ។ វេទិកានេះ ត្រូវបានរៀបចំឡើងដើម្បីប្រមូលផ្ដុំថ្នាក់ដឹកនាំរាជរដ្ឋាភិបាល និយ័តករ ប្រតិបត្តិករក្នុងវិស័យបរធនបាលកិច្ច គ្រឹះស្ថានហិរញ្ញវត្ថុ និងអ្នកជំនាញក្នុងវិស័យ ដើម្បីភ្ជាប់បណ្ដាញទំនាក់ទំនង ផ្លាស់ប្ដូរទស្សនៈ ចំណេះដឹង និងបទពិសោធន៍ ព្រមទាំងរួមចំណែកកំណត់ទិសដៅសម្រាប់បន្តអភិវឌ្ឍវិស័យបរធនបាលកិច្ចនៅកម្ពុជា ប្រកបដោយទំនុកចិត្ត អនុលោមភាព នវានុវត្តន៍ និងចីរភាព។ ថ្លែងក្នុងសុន្ទរកថាស្វាគមន៍ ឯកឧត្តម សុខ ដារ៉ា អគ្គនាយកនៃ និយ័តករបរធនបាលកិច្ច បានគូសរំលេចអំពីសាវតារ វឌ្ឍនភាព និងសមិទ្ធផលសំខាន់ៗនៃវិស័យបរធនបាលកិច្ចក្នុងរយៈពេល ៥ ឆ្នាំកន្លងមក ព្រមទាំងបានបញ្ជាក់ពីការបន្តជំរុញការអភិវឌ្ឍប្រព័ន្ធបរធនបាលកិច្ចប្រកបដោយតម្លាភាព ភាពធន់ និងចីរភាព។ តំណាងក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក លោក Eric Loo នាយកប្រតិបត្តិ និងជាអភិបាលប្រតិបត្តិ នៃក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានអញ្ជើញចូលរួមវេទិកាដ៏មានសារៈសំខាន់នេះ។ ក្នុងនាមជាក្រុមហ៊ុនគ្រប់គ្រងមូលនិធិដែលទទួលបានអាជ្ញាបណ្ណនៅព្រះរាជាណាចក្រកម្ពុជា ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បន្តប្តេជ្ញាសហការយ៉ាងជិតស្និទ្ធជាមួយដៃគូបរធនបាលរបស់ខ្លួន ដើម្បីជំរុញកិច្ចសហប្រតិបត្តិការ ពង្រឹងទំនុកចិត្តលើទីផ្សារ និងរួមចំណែកគាំទ្រដល់ការអភិវឌ្ឍប្រកបដោយចីរភាពនៃវិស័យហិរញ្ញវត្ថុ និងការវិនិយោគនៅព្រះរាជាណាចក្រកម្ពុជា។
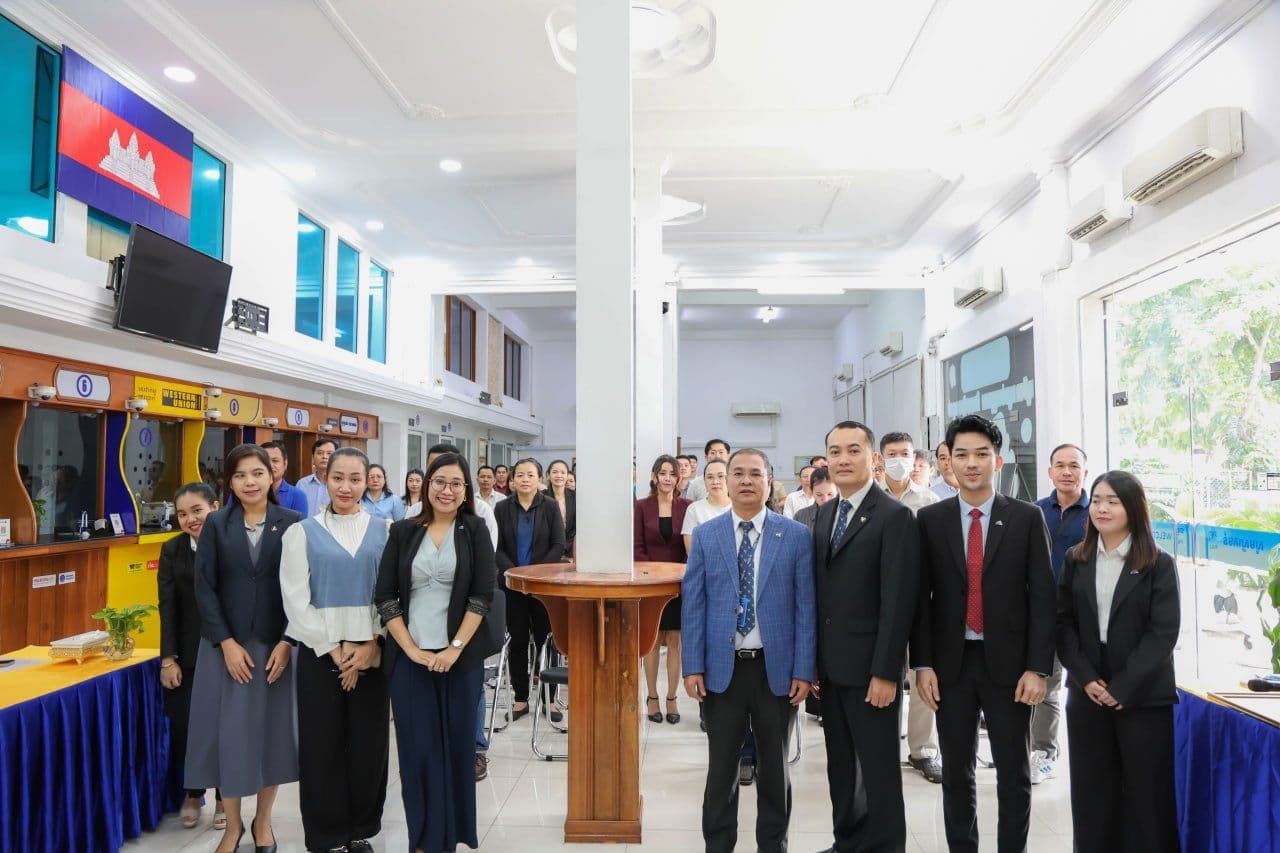
សិក្ខាសាលាឱកាសមាសនៃការវិនិយោគមូលបត្រ នៅសាខាធនាគារ អេស៊ីលីដា – ទួលគោក
ក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុនមូលបត្រ អេស៊ីលីដា ម.ក បានរៀបចំដោយជោគជ័យនូវសិក្ខាសាលាស្តីពី “ឱកាសមាសនៃការវិនិយោគមូលបត្រ” ដែលជាផ្នែកមួយនៃដំណើរការផ្សព្វផ្សាយកម្មវិធីរ៉ូដសូ លើកទី៣ ដែលបានរៀបចំឡើងនៅសាខាក្រុមហ៊ុនក្នុងស្រុកធនាគារអេស៊ីលីដា ភីអិលស៊ី (ខណ្ឌទួលគោក សង្កាត់បឹងកក់ទី១) កាលពីព្រឹកថ្ងៃទី១ ខែសីហា ឆ្នាំ២០២៦។ សិក្ខាសាលានេះរៀបចំឡើងក្នុងគោលបំណងលើកកម្ពស់ការយល់ដឹងអំពីការវិនិយោគក្នុងទីផ្សារមូលធននិងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ដែលជាគម្រោងវិនិយោគរួម (CIS)។ យើងខ្ញុំសូមថ្លែងអំណរគុណយ៉ាងជ្រាលជ្រៅចំពោះដៃគូសហការនិងសិក្ខាកាមទាំងអស់ ដែលបានចូលរួមនិងគាំទ្រដល់ការរៀបចំសិក្ខាសាលានេះប្រកបដោយជោគជ័យ។ សូមថ្លែងអំណរគុណជាពិសេសចំពោះលោក សុខ ច័ន្ទតុលា អនុប្រធានផ្នែកលក់និងទីផ្សារ នៃក្រុមហ៊ុន បេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ដែលបានចូលរួមជាវាគ្មិនសម្រាប់បទបង្ហាញដ៏មានអត្ថន័យនិងខ្លឹមសារយ៉ាងមានសារៈសំខាន់អំពី “តម្លៃនិងអត្ថប្រយោជន៍នៃការវិនិយោគក្នុងមូលនិធិមូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី (BAEF) ”។ យើងខ្ញុំរីករាយនិងស្វាគមន៍អ្នកទាំងអស់គ្នាក្នុងកម្មវិធីបន្ទាប់។
ទស្សនៈទីផ្សារ
2024 April, Market Outlook: Navigating Volatility Amidst Inflation, Interest Rates, and Geopolitical Risks
Recently, both the bond and stock markets have experienced heightened volatility, driven by inflation and retail sales in the US consistently exceeding expectations. In response, the Federal Reserve once again opted to hold off on lowering interest rates, waiting for more comprehensive data before making further policy decisions. This cautious approach led investors to adjust their interest rate forecasts aggressively, which directly impacted equity markets. We believe these concerns are justified, especially as commodity prices have surged, potentially contributing to higher inflation in the months ahead. At present, we assess that the recent equity price movements may be a short-term reaction to rising bond yields, and we will continue to monitor these trends closely. In China, the government's initiative to support "whitelist" property projects has made significant progress, with funds raised reaching RMB 469 billion by the end of March—more than double the RMB 200 billion previously reported. Given the size of China’s residential property sector, we anticipate further substantial disbursements. Additionally, there is an expectation that the People’s Bank of China will gradually increase government bond trading through its open market operations, signaling a form of monetary policy easing. These developments, along with China's Q1 GDP growth and improved PMI numbers, offer positive signals for the economy. However, we recognize initial signs of a slowdown in key economic indicators, such as retail sales and industrial production, reflecting lingering sluggishness in the domestic economy. We will continue to track these factors in the coming months. On the geopolitical front, tensions between Iran and Israel are escalating, with Israel considering its response to recent drone strikes by Iran. This situation could significantly impact crude oil prices, introducing further inflationary risks in the near term. Meanwhile, the ongoing US-China tensions remain a long-term issue. Recently, US lawmakers introduced a bill that would bar mutual funds from investing in indices that include Chinese stocks. This follows a broader trend of global portfolio allocations shifting away from China over the past year. As a result, we have observed a substantial valuation premium in the US market relative to China, far exceeding historical norms. We believe that once the Chinese economy stabilizes and returns to sustainable growth, this valuation gap may narrow. In the near term, inflationary risks in the US and uncertainty in China could present challenges for equity markets. However, our analysis of current data suggests that this may be a temporary correction, largely driven by high valuations in developed markets. We remain focused on identifying attractive opportunities as they emerge in the evolving market landscape.
2024 March, Market Outlook: Navigating Elevated Interest Rates, China’s Economic Measures, and Corporate Earnings
Throughout the month, the Federal Reserve reinforced its stance that there is no urgency to lower interest rates during the first half of 2024. Notably, the Fed addressed growing concerns within the commercial real estate sector, acknowledging that while the situation remains manageable for now, it may lead to further banking failures. This dovetails with our cautious outlook on the potential consequences of keeping interest rates elevated for too long, especially if policy missteps occur. High rates for an extended period could stress certain sectors, particularly real estate, heightening risks within financial markets. In China, the government has begun to take action to support previously announced “whitelist” property projects. Major commercial banks have approved over RMB 200 billion in loans to facilitate the completion of these projects. While this is a positive step, further financing will likely be necessary to ensure sufficient liquidity for the real estate sector's recovery. We will continue to monitor further policy announcements and their impact on property sales and prices in the coming months. The recently concluded "Two Sessions" meeting of the Chinese Communist Party revealed economic targets similar to those set last year. The 5.0% GDP growth target for 2024 appears ambitious, especially in light of the modest 3.0% deficit target and the conservative spending habits of Chinese consumers. However, we believe this growth target is achievable, given the gradual shift in consumer behavior towards increased spending. Furthermore, growth outside of the real estate sector remains robust, offering a positive outlook for broader economic recovery. In the corporate world, recent earnings reports from leading companies have generally shown strong growth for Q4 2023, with some projecting modest top-line expansion in 2024. However, US stocks that missed earnings expectations and guidance experienced sharp declines, a consequence of their elevated valuations. Given the uncertain economic outlook, we will closely monitor both economic and industry-specific data to inform our next portfolio decisions. Despite these short-term uncertainties, we remain positive about the long-term potential of our holdings. In conclusion, as central banks maintain a cautious stance on interest rates and China accelerates its economic support, global markets face a delicate balancing act in 2024. Careful navigation through these challenges will be key for investors seeking sustainable growth opportunities.
2024 February, Market Outlook: Navigating Central Bank Strategies and Growth Opportunities in Asia
As we step into 2024, initial hopes for early interest rate cuts by the US Federal Reserve (FED) and the European Central Bank (ECB) are fading. Both central banks have downplayed the likelihood of reducing rates anytime soon, largely due to strong economic data released in recent months. The US economy continues to display resilience, with sustained expansion indicating that the FED must tread carefully. Lowering interest rates too soon could risk reigniting inflation, which the central bank is keen to avoid. At the same time, there are pockets of weakening growth within the economy, signaling the potential for a broader slowdown. This delicate balancing act places the FED in a challenging position, where policy mistakes could have significant consequences for both the US economy and global financial markets. In line with our earlier expectations, the Eurozone also faces similar inflationary pressures, with energy prices remaining persistently high. As a result, inflation remains sticky, preventing the ECB from easing rates. We foresee that both central banks will need to remain vigilant in navigating the complex dynamics of their respective economies, weighing inflation risks against the threat of economic slowdowns. Meanwhile, China's approach to monetary policy has taken a markedly different turn. The Chinese government recently lowered the 5-year loan prime rate by 25 basis points to 3.95%, signaling its determination to stimulate the economy and support the real estate sector. Under the “whitelist” initiative, commercial banks are encouraged to provide lending to property projects approved by local governments. These rapid, proactive measures underscore the government's commitment to front-loading stimulus to prevent weak sentiment in the housing market from deepening. We believe these policies will continue to evolve progressively, ensuring that the real estate sector stabilizes and recovers on a sustainable path. Signs of improvement are already emerging in China’s economy. Recent data on monetary aggregates indicate positive movement, and domestic travel and spending during the Lunar New Year suggest a rebound in consumer activity. On the global stage, China’s exports have grown for the second consecutive month in December 2023, further reinforcing the positive outlook for 2024. These rapid policy moves come as the State Council calls for "forceful measures" to restore confidence in both the economy and financial markets. Japan is also showing signs of strength, with the economy benefiting from long-anticipated corporate reforms. After decades of deflation, Japan appears to be breaking free from this prolonged economic phase. Reforms aimed at improving corporate profit margins and shareholder returns are finally coming to fruition, marking the end of the country's 30-year deflationary struggle. We believe these developments will unlock significant value for shareholders, creating opportunities for growth in the Japanese market. In summary, we remain optimistic about the prospects for the Asian markets, particularly as China and Japan implement aggressive economic measures. Conversely, we approach the US markets with caution, given the headwinds presented by inflationary pressures and an overconcentration in the technology sector. As we move forward, the balancing act between growth, inflation, and central bank policy will continue to shape the global market landscape, with Asia emerging as a bright spot for investors in 2024.
2024 January, Market Outlook - Navigating 2024 Amid Geopolitical Tensions and Economic Shifts
As we enter 2024, the global financial landscape is expected to shift focus from rising bond yields to interest rate stabilization and potential easing, particularly by the US Federal Reserve. After three years of tightening policies, we anticipate that both the US and Europe will experience sharply slower economic activity and increased unemployment. Europe, in particular, faces heightened risks of a prolonged recession. While interest rates in the US may hold steady for now, primarily due to persistent inflation pressures in areas like housing, rising geopolitical risks, such as recent airstrikes by the US and UK in response to Houthi rebel attacks, could lead to disruptions in global trade and shipping costs. Geopolitical Tensions: The US-China Factor Geopolitical developments, especially the enduring US-China tension, will be a critical driver in assessing global economic and financial market performances. The ongoing decoupling between the two economic giants, particularly in the semiconductor industry, presents both challenges and investment opportunities. We foresee increased innovation stemming from this geopolitical divide, providing promising prospects in certain sectors. The AI Revolution: A Long-Term Investment Opportunity The advent of generative artificial intelligence (AI), epitomized by innovations like ChatGPT, has sparked widespread interest in AI-driven technologies across industries. While the global addressable market for AI is still being estimated, we remain optimistic about its long-term growth potential. AI companies in our portfolio have already shown promise, and we continue to explore new investment opportunities in this space as AI applications expand. China's Economic Recovery: Stabilization Efforts China's economic recovery is gaining momentum, though the real estate sector remains a drag. However, recent fiscal and monetary policies have helped stabilize the situation. The Central Economic Work Conference's call for proactive fiscal expansion and real estate policy adjustments are positive signs for the market. China's central bank has also introduced liquidity-boosting measures, such as a 50 basis point reduction in the reserve requirement ratio and lower rates for loans to small firms. We believe these are incremental steps toward further stabilization, and we are optimistic about China's economic and market outlook in 2024. US Presidential Election: Market Implications This year’s US Presidential Election will undoubtedly shape economic policies and market directions, though we refrain from speculating on political outcomes. Instead, our focus remains on the data-driven economic and market trends, with a view that the US economy will increasingly look inward as the election approaches. Overall, we believe Asia, particularly China, remains a bright spot in the global economy, while the US and Europe may face slower growth and recessionary pressures. We remain vigilant in assessing geopolitical risks and continue to focus on sectors like AI and innovation, which offer long-term growth opportunities.
2023 December, Market Outlook: Asia Emerges as a Bright Spot Amid Global Economic Shifts
As 2023 draws to a close, the equity market has remained largely stable, with investors maintaining a preference for developed markets. While Asia Pacific markets have also posted positive returns, their performance still trails behind other regions despite notable improvements in economic data. This disparity is likely due to end-of-year dynamics such as tax-loss harvesting and institutional portfolio adjustments, or "window dressing," a common phenomenon seen during this period. Historically, such short-term volatility tends to carry over into January as fund managers rebalance their portfolios for year-end reporting. In developed markets, equity markets have experienced significant optimism since the Federal Reserve opted to hold interest rates steady for two consecutive meetings. This move has signaled to investors that the Fed's interest rate hike cycle may have peaked, fueling market euphoria. Additionally, concerns about a looming US recession have eased, with many economists now revising their forecasts toward a "soft landing" scenario, where economic activity slows but avoids a severe downturn. However, inflation in the US remains persistently above the Fed's 2% target, indicating that interest rates may stay elevated for an extended period. The future economic outlook remains uncertain, especially as housing inflation cools, but we believe that while the risk of a recession is still moderately high, it is unlikely to escalate into a systemic crisis. On the geopolitical front, China’s recent diplomatic overtures toward the US have been a positive development. Following Chinese President Xi Jinping's visit to the US last month, both nations have expressed a renewed commitment to peaceful cooperation. The resumption of military dialogue, after months of silence, signals China's intention to restore political ties with the US. Additionally, President Xi’s meeting with top US business leaders highlighted strong corporate support for continued engagement with China, despite ongoing geopolitical tensions. For instance, Mastercard's new joint venture with China's national transaction processor, NetsUnion Clearing, demonstrates the long-term business potential between the two countries, allowing Mastercard cardholders to enjoy seamless payments in China. Nevertheless, while these diplomatic efforts are encouraging, further reciprocal actions from the US government will be crucial to reducing geopolitical risks in the long term. With the US presidential elections on the horizon in late 2024, we expect China to remain a central theme in American political discourse, with both parties likely positioning the country as a major national security threat to garner electoral support. This political climate may perpetuate tensions, and as a result, we anticipate that geopolitical risks will remain elevated through 2024. Looking beyond the US, other significant elections, such as Taiwan's, will also play a key role in shaping geopolitical dynamics. As global security concerns intensify, we foresee a gradual restructuring of global supply chains, with capital and business operations increasingly shifting to countries deemed safer or more politically stable. This trend toward economic fragmentation will favor companies capable of maintaining market share and operational efficiency amid the reshoring of industries. In China, the recent Central Economic Work Conference concluded with the government setting a clear pro-growth agenda for 2024. Chinese policymakers are focusing on reviving confidence and stimulating economic growth through a series of supportive measures, including monetary, fiscal, and administrative interventions. These initiatives have been ramping up in intensity, and we anticipate additional measures in the coming months, particularly aimed at addressing risks in the real estate sector. Given these developments, we continue to see Asia, particularly China, as a bright spot for economic growth in the global economy. A lower interest rate environment, coupled with increased liquidity, should help alleviate financial pressures and reduce the debt burdens of companies and individuals. As the world economy navigates through geopolitical tensions and inflationary pressures, Asia remains well-positioned to drive global growth in the near term, making it a focal point for investors looking to capitalize on emerging market opportunities. In summary, while global economic conditions remain uncertain, Asia’s resilience, supported by pro-growth policies and improving economic indicators, offers a compelling investment case, even as geopolitical risks loom on the horizon.
2023 November, Market Outlook: Resilience, Stimulus, and Global Shifts
As we look ahead, the global market outlook remains shaped by several key developments. Despite geopolitical tensions and ongoing conflicts, such as the humanitarian crisis between Israel and Hamas, we expect limited broader economic impact due to stabilizing military presence and containment measures. The risk of a wider regional conflict appears low, preserving global market stability for the time being. US Economic Resilience and Slowdown Expectations In the US, resilience continues to be a dominant theme. While the Federal Reserve’s tightening measures have been in place since 2022, the financial system remains robust, supported by the aftereffects of COVID-19 stimulus and substantial fiscal spending by the US government. This liquidity, however, is expected to taper, with a corresponding economic slowdown projected over the medium term. Current forecasts suggest GDP growth of 0.7% in Q4 2023 and 0.3% in Q1 2024, indicating a likely deceleration in the coming quarters. China’s Recovery Gains Momentum China’s economy has begun to gain notable momentum, driven by improving retail sales, imports, and industrial output. The government has recently announced a significant RMB 1 trillion stimulus package to further bolster the recovery. However, investor sentiment remains cautious, keeping valuations suppressed relative to the US. We believe that this discrepancy is unsustainable and anticipate that over the medium term, valuations in China will close the gap, driven by stronger economic fundamentals. Japan’s Stimulus and Growth Prospects Japan is emerging as an intriguing opportunity as it moves away from years of deflation, with inflation now supported by demand. In response to weakening economic data, the Japanese government has introduced a US$ 110 billion stimulus package aimed at boosting private consumption. This should translate into economic growth in the near-to-medium term, further enhancing Japan’s market potential. Focus on Asia Amid Geopolitical Stability Asia remains our primary focus, especially in light of recent positive developments in China’s economic data and a decrease in US-China geopolitical tensions following the Biden-Xi meeting in San Francisco. Agreements between both countries signal a more stable relationship, reducing trade war fears and enhancing the region’s investment appeal. Overall, we maintain a cautiously optimistic view, focusing on opportunities in Asia while monitoring the evolving macroeconomic landscape.