

វិចារណកថា
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
បន្ទប់ព័ត៌មាន
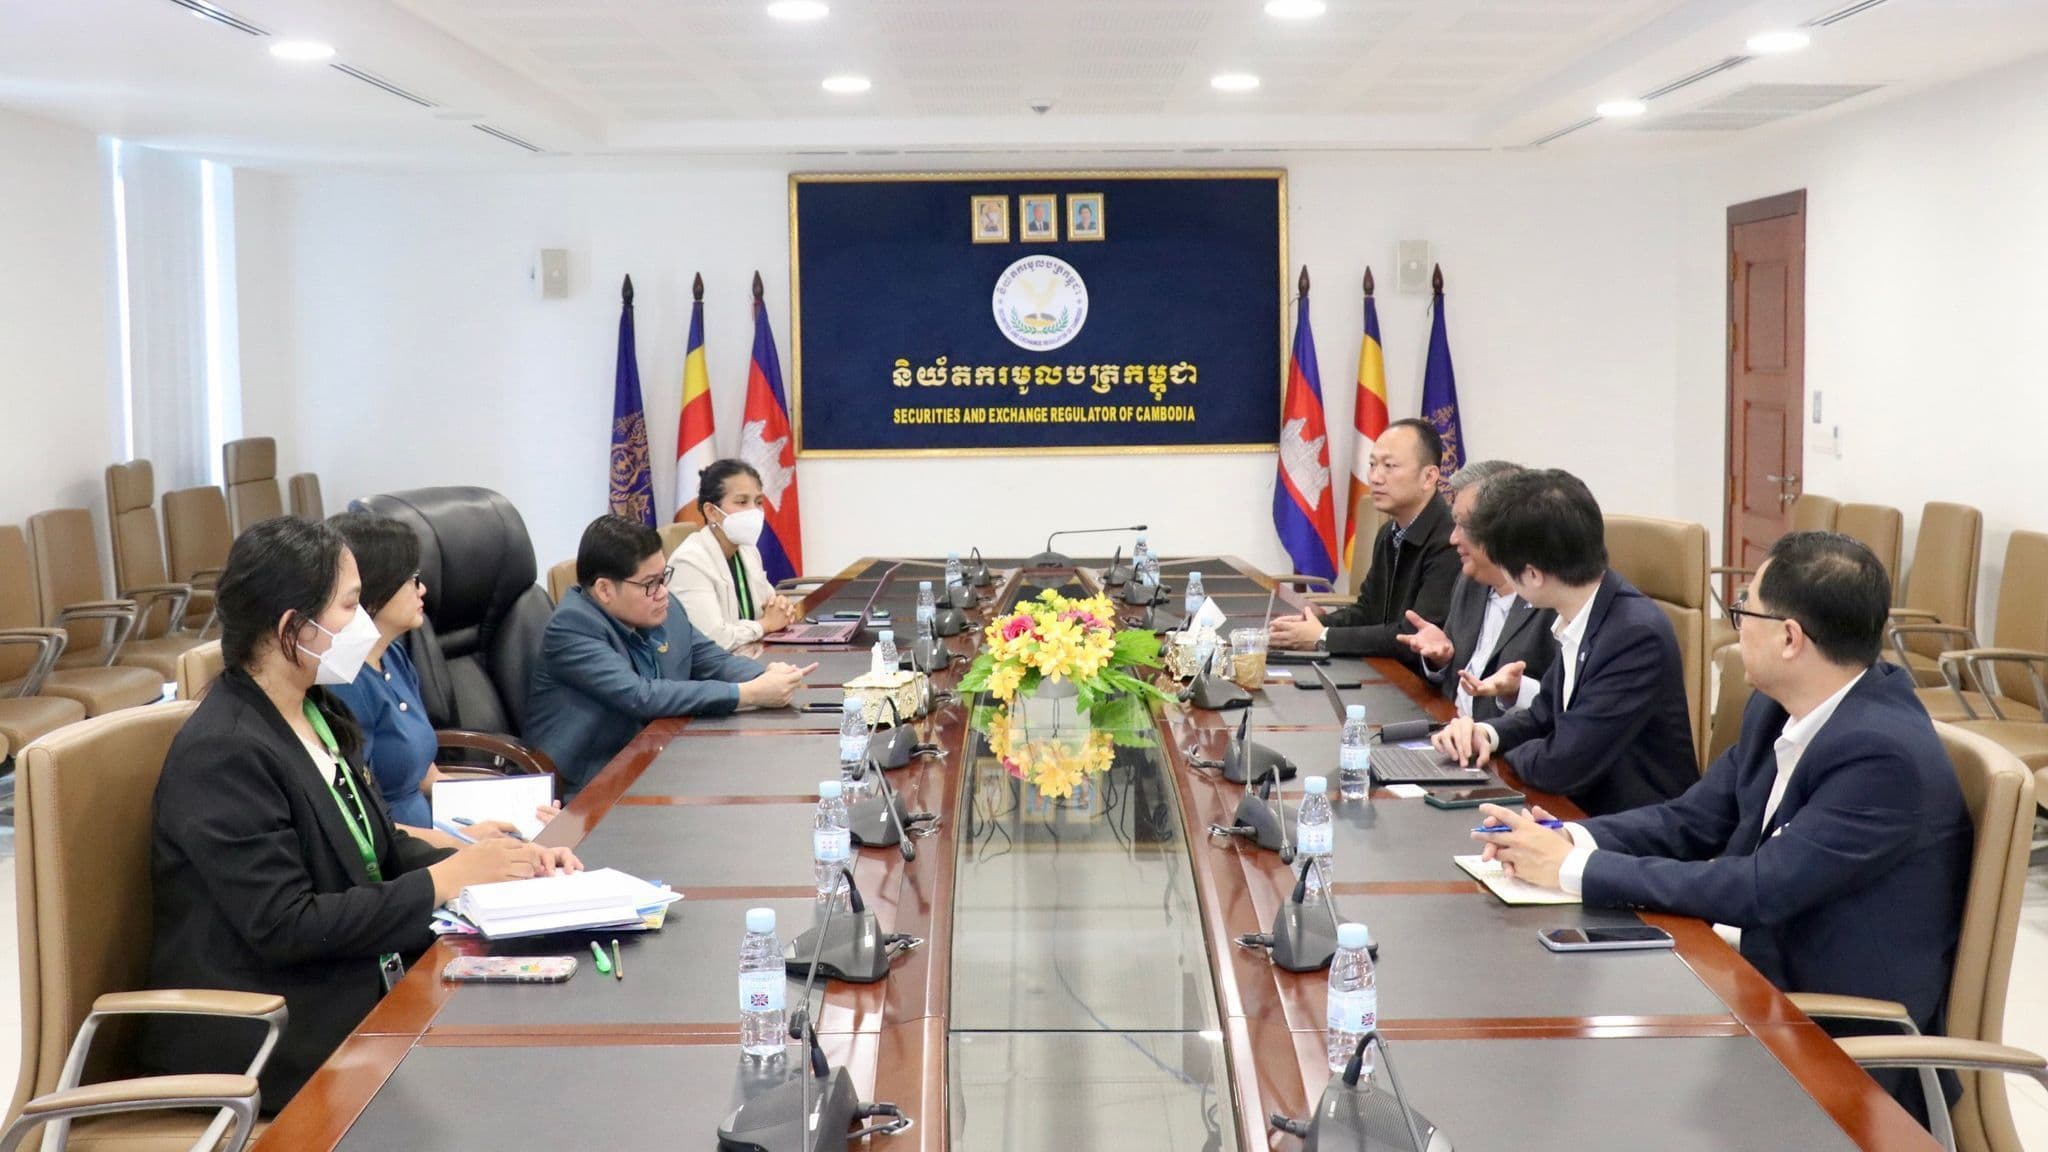
Government and Banjaran Asset Management Hold Productive Talks on New Collective Investment Scheme Fund
Phnom Penh, Cambodia - A significant meeting took place between His Excellency Su Sochet, the Director General of the Securities and Exchange Regulator of Cambodia (SERC), and representatives from Banjaran Asset Management (Cambodia) PLC. The delegation, led by H.E. Su Sochet, met to discuss the establishment and future prospects of Banjaran’s new Collective Investment Scheme (CIS) fund. This crucial dialogue aimed to align regulatory frameworks with the goals of the fund, ensuring its compliance with Cambodian financial regulations. The new CIS fund is expected to provide Cambodian investors with a broader range of investment options, allowing them access to international markets and enhanced financial growth opportunities. The discussions were highly productive, with both parties expressing optimism about the future of the fund and its potential to drive growth within Cambodia’s burgeoning financial services sector. The meeting also reinforced Banjaran Asset Management’s commitment to promoting robust investment solutions while adhering to the highest standards of governance and transparency. This marks a significant milestone for Banjaran Asset Management (Cambodia) PLC as it continues to collaborate closely with the SERC, bringing innovative investment opportunities to the Cambodian market. More Securities and Exchange Regulator of Cambodia
Investment Education Series related to Collective Investment Scheme (Part Three)
The Investment in Collective Investment Scheme In part two of the Investment Education Series, we discussed the needs and merits of investing as well as the benefits of investment diversification. The article concluded that an investment fund, or Collective Investment Scheme fund offers the best option for individuals to invest and grow their wealth steadily over time. A fund also helps to lower investment risk through diversification, all while keeping investing affordable to the public. In this article, we will share the real case study of the first Investment fund that was approved by the Securities and Exchange Regulator of Cambodia (SERC) on 15 November 2023, the BAMC Asia Equity Fund (BAEF). BAEF is managed by Banjaran Asset Management (Cambodia) PLC (BAMC), a SERC-licensed asset management company based in Cambodia. The fund lawyer is HBS Law and the fund auditor is Crowe (KH) Co., Ltd, both of which got the accreditation from the SERC. The fund trustee is Stronghold Trustee Co., Ltd which is also a SERC-licensed CIS trustee. In summary, in the ecosystem of the CIS, all players shall get a license, approval, or accreditation from the SERC. About BAMC Asia Equity Fund BAEF is a fund investing in a diversified portfolio of 30 or more companies listed on major stock exchanges across Asia Pacific Ex-Japan. The fund targets to provide the benefits of investing in Asia, which economists globally see as the premier growth region in the coming years. The fund’s tagline is “The Rise of Asia”. According to the disclosure documents, BAEF targets a return of 7% to 10% per annum over the medium to long term, yet this return is not guaranteed. The investment in fund is considered as a form of a regular savings plan. The invested amount can eventually be used for children's education, healthcare, to part fund the purchase of a house, or for retirement. To invest in the fund, the investor shall obtain an investor ID from the SERC first. However, for those who already have the investor ID, they do not need to re-apply for the investor ID. Below is a term sheet for the BAEF fund: Key Consideration Before Making Investment Decision Generally, fund managers make investments using basic approaches like the top-down approach and bottom-up approach. A top-down approach is when the fund manager looks at macro factors such as, economic cycles, inflation, interest rates, global trends, etc. The bottom-up approach is when the fund manager looks at the features of the individual securities that they invest in such as, the balance sheet, profit and loss statement, management, products, and services, etc. The BAEF adopts both approaches in making their investments. Bottom-up Approach: Sustainable Growth in the Long-term The fund manager will select companies that have proven sustainable business models and have proven track records. The fund manager will look at audited financial statements, valuation, and quality of management amongst other things. Top-down Approach: Why Invest in Asia? Stable Productive Population in the coming 10 to 20 years Asia has a large population base and a favorable demographics. It has a large segment of the younger population which will translate to a stable productive workforce over the next 10 to 20 years. This will result in higher income and higher consumption. These factors will help to drive the region’s economy and its businesses to grow. Relative to poor demographics from regions like the US and Europe, Asia is preferred. Strong Economic Growth In terms of economic growth, Asia is also growing faster and is bigger than the EU and North America. According to an IMF report dated Oct 2023, real GDP growth in 2023 is highest in Asia Pacific at 4.4% vs EU at 1% and North America at 2.1%. As % a share of the total world’s GDP, Asia Pacific share is 45.6%, the EU at 21.0% and North America at 18.7%. Benefits from the World’s Largest Free-Trade Agreement and Pro-Business Governments Asia’s economic growth will be further enhanced after 15 Asian countries recently signed a free-trade agreement known as the Regional Comprehensive Economic Partnership (RCEP), which will be the world’s largest free-trading bloc. The free-trade agreement should enhance trading activities and thus further drive GDP growth as a result. In its forecast, IMF projected Asia to remain as the strongest GDP growth region in 2028 at 3.9% vs EU at 1.6% and North America at 2.1%. Investment Education Series related to Collective Investment Scheme (Part Three) Asian Companies are Recognizable Globally Asia now has many homegrown listed companies which are recognizable globally. These companies are well-managed and have strong financials. They include companies like Singapore Airlines, Alibaba, Tencent, Samsung Electronics, TSMC, Grab, BYD and many others. Asia Markets Remain Cheap Despite Asia’s bigger population base and stronger economic growth, Asian stocks trade at much lower levels as compared to EU and US stocks based on valuation ratios like price-to-earnings, price-to-book value, and price-to-sales. These ratios are financial metrics that measure and analyze stock prices in unit terms and compare them with those of peers or competitors. The lower the financial ratio, typically the more attractive is the stock market or a particular stock. Furthermore, Asia ex-Japan accounts for 58% of the world’s population, and 48% of the world's economy, yet it accounts for only 12.42% of the investments made in the stock markets globally. BAMC views that the under-representation of Asian stock investments will have to be adjusted upwards eventually. Is it the Right Time to Invest Now? There is no right or wrong time to invest in the stock markets. Investing is a disciplined approach to set aside the savings and put them regularly into investments like an investment fund. Past market cycles show that each time markets fall, they will rebound. And when they rebound, they will set a new market high. In other words, stock markets tend to rise over the long term though in between, they may correct according to economic cycle or on non-economic-related events like war, pandemic, etc. In the current situation, stock markets in general have fallen since the beginning of 2022 on the back of several key events like the Russian-Ukraine war and the sharp increase in US interest rate. Is this an opportune time to invest? BAMC has analyzed the past market cycles and noted that after each significant event that had caused stocks to fall, they had rebounded sharply after riding out that event: Asian Financial Crisis in 1997 – the collapse of Asian currencies led by the Thai Baht and which spread to other Asian currencies, caused Asian markets to tumble. But they rebounded some 155% from the low in 1997 until 2000. Dot.com Bust 2000 and September 2001 – global markets fell when the US dot.com bubble went bust in 2000, and it was further made worse by the September 2001 bombing of the Twin Towers in the US. A couple of years later in 2003, Asian markets started to recover and moved higher. It rebounded some 360% since 2003. Global Financial Crisis in 2007 – the collapse of US banks Bear Stearns and Lehman Brothers in 2007 caused global markets to take a sharp tumble. The fall was rather short-lived and within less than two years, global markets recovered sharply by 236%. COVID-19 in 2020 – again global markets took a nosedive when the pandemic started. However decisive action by global central banks to provide funding to businesses affected by the pandemic caused the markets to again rebound very quickly. The markets fell but rebounded within a short span of six months by some 90%. Russia-Ukraine war and spike in inflation and interest rate hike in 2022 – markets have since fallen. Is it time to buy? An article from the Securities & Exchange Regulator of Cambodia (SERC)
Investment Education Series related to Collective Investment Scheme (Part Two)
Why Invest and the Importance of Investment Diversification Investment diversification across different asset classes would lower the risks compared to traditional investment portfolios. With the launch of the first Collective Investment Scheme (CIS), which was approved by the Securities and Exchange Regulator of Cambodia (SERC) recently, Cambodians now have an opportunity to further protect their investments. The CIS scheme now allows Cambodians to diversify their asset types into more legitimate investments across different countries which in turn lowers the risks. A further line of protection is with the investments being carried out only with fund managers licensed by SERC. The SERC recently approved Cambodia’s first SERC-approved CIS fund – the BAMC Asia Equity Fund, managed by Banjaran Asset Management Cambodia. Diversification of investment is not a new concept and is something that is propagated and recommended even by the world financial leaders. According to the world’s 6th richest man and famous investor Warren Buffet, “Never depend on a single income. Make an investment to create a second source”. There are many benefits to investing whereby it helps wealth creation with investors making more money. For Cambodians, it also paves the way for financial independence, eventually leading to them not worrying about their financial stability. It can also be a solid source of additional income to top up their regular income. Importantly, it could also serve as a protection against inflation, giving the investor the freedom of affordability when prices of goods increase. The positive wealth-creation effect of investing is illustrated in Figure 1 below: Investors, naturally would expect their assets to grow over time as they continue to maintain their investments. However, it is also important to note that all investments come with a certain amount of risk. The higher the return, the higher the risk. These risks can be moderated through a simple action of diversifying the investment in the regulated financial products. Currently, Cambodians tend to grow their wealth primarily through two forms of investments: bank fixed deposits and land-related investments. According to CEIC Data, in August 2023, Cambodia saw a record high of US$40.9 billion in total bank deposits. This was an increase from US$37 billion recorded a year ago. ❖ Other Types of Investment There are many investment options available for investors, ranging from lower-risk investments like bank deposits and investment-grade bonds to the extremely high-risk investments like private debt and private equities where investors may potentially lose all their invested capital. ❖ Investment Diversification Investment diversification is the process of spreading your investments across different asset classes (bank deposits, stocks, bonds, real estate, etc), across different countries (HK/China, US, Japan, Singapore, Thailand, etc), and across different industry sectors (banking, consumer, technology, property, etc). The main objective is to spread the risk such that if one investment goes bad, it should not affect the overall investment. When investments are diversified, the risk is lower. In an equities collective investment scheme fund, for example, the risk of investing in stocks can be reduced through diversification. This is done by creating a basket of stocks (known as a portfolio) comprising of 30 different stocks. The diversification benefits include not just from an increase in the number of stocks invested, but also by investing in different countries and across different industry sectors such as banking, property, consumer, telecoms, technology, etc. Through diversification by adding more stocks to a fund, the risk is greatly reduced. The illustration below shows the diversification benefit-risk reduces as more stocks are added to the portfolio: One point to note is that while adding more stocks to a portfolio will reduce risk, it will come to a point where the residual risk cannot be further reduced as more stocks are added. This residual risk is known as the market risk (indicated by * in Figure 3), which cannot be diversified away. An example of market risk is when a major war breaks out, or a global pandemic that goes out of control, on a scale that is worse than COVID-19. For an individual, it is troublesome to practice investment diversification. Firstly, the investment amount may be too small to diversify into different asset classes, or to buy too many stocks. Secondly, transaction costs may be high and will affect the investment return as a result. Thirdly, the investor may not have time or knowledge to track the different investments and this may lead to taking no action as a result. And lastly, investors may lack the discipline to maintain proper investments. Likewise, Cambodians generally should diversify their asset types into more legitimate investments. A good diversification would be to invest some in fixed deposits, land-related investments, and collective investment scheme funds. Collective Investment Scheme (CIS) fund collects monies from different investors and pools them together for investment purposes. Each investor retains ownership and control of his own units in the fund. The fund then invests in assets like stocks, bonds, real estate, etc. For an equities CIS fund, for example, a professional fund manager licensed by the SERC does the investment work. Investors can choose when to invest or exit the fund. Funds come with different investment strategies and objectives and appeal to different investors with different risk appetites. Investing in a CIS fund should offer investors an easy way to meet their investment and investment diversification objectives. An investment fund offers multiple benefits. This includes it being professionally managed by a SERC-licensed fund manager and the fund is separately approved by the SERC for sale to the investing public. It may offer diversification benefits as some CIS funds will invest in a diversified portfolio of stocks across different countries and different industry sectors The initial investment amount can be set at an affordable level, for example as low as US$500. With this small amount of investment, an investor can own units in a portfolio of approximately 30 stocks or more. It also gives Investors the right to buy and sell the fund on a daily basis with the pricing of the fund being transparent and published daily in the local media. Investing should generate a reasonable, positive return with a manageable degree of risk. Individuals should generally invest in products that are regulated by the SERC, and managed by SERC-licensed fund managers. To be able to invest in a fund unit, the investor shall obtain the Investor Identification Number (ID) from the SERC first. Investors should also practice investment diversification to minimize investment risk. CIS fund offers investors the ease of investing, and also provides the other benefits from investment including diversification. An article from the Securities & Exchange Regulator of Cambodia (SERC)
Joins Global "#WeThe15" Movement at National Centre of Disabled
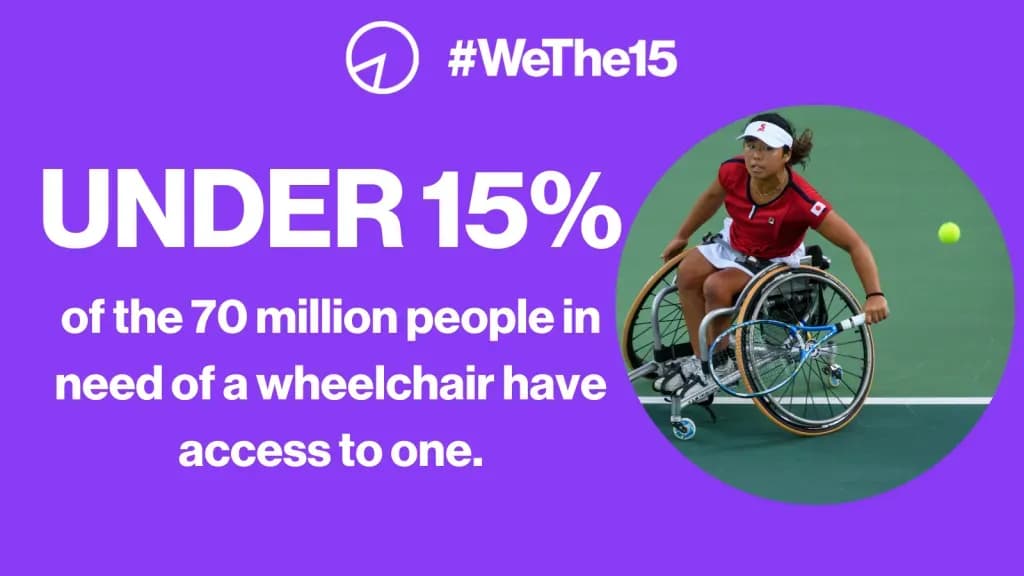
Phnom Penh, Cambodia – Banjaran Asset Management (Cambodia) PLC. participated in the global "#WeThe15" event held at the National Centre of Disabled. This event, part of the worldwide campaign to represent the 1.2 billion people living with disabilities, aims to advocate for their inclusion, rights, and visibility. As part of the "#WeThe15" movement, Banjaran Asset Management (Cambodia) PLC stood alongside other organizations in promoting greater awareness and support for persons with disabilities. The event featured a series of engaging activities, discussions, and initiatives focused on driving equal opportunities and improving accessibility for those with disabilities. Banjaran Asset Management (Cambodia) PLC's involvement in this global initiative highlights its dedication to corporate social responsibility, fostering an inclusive community, and supporting efforts toward equality and empowerment. Through initiatives like "#WeThe15," the company remains committed to making a positive impact both locally and globally.
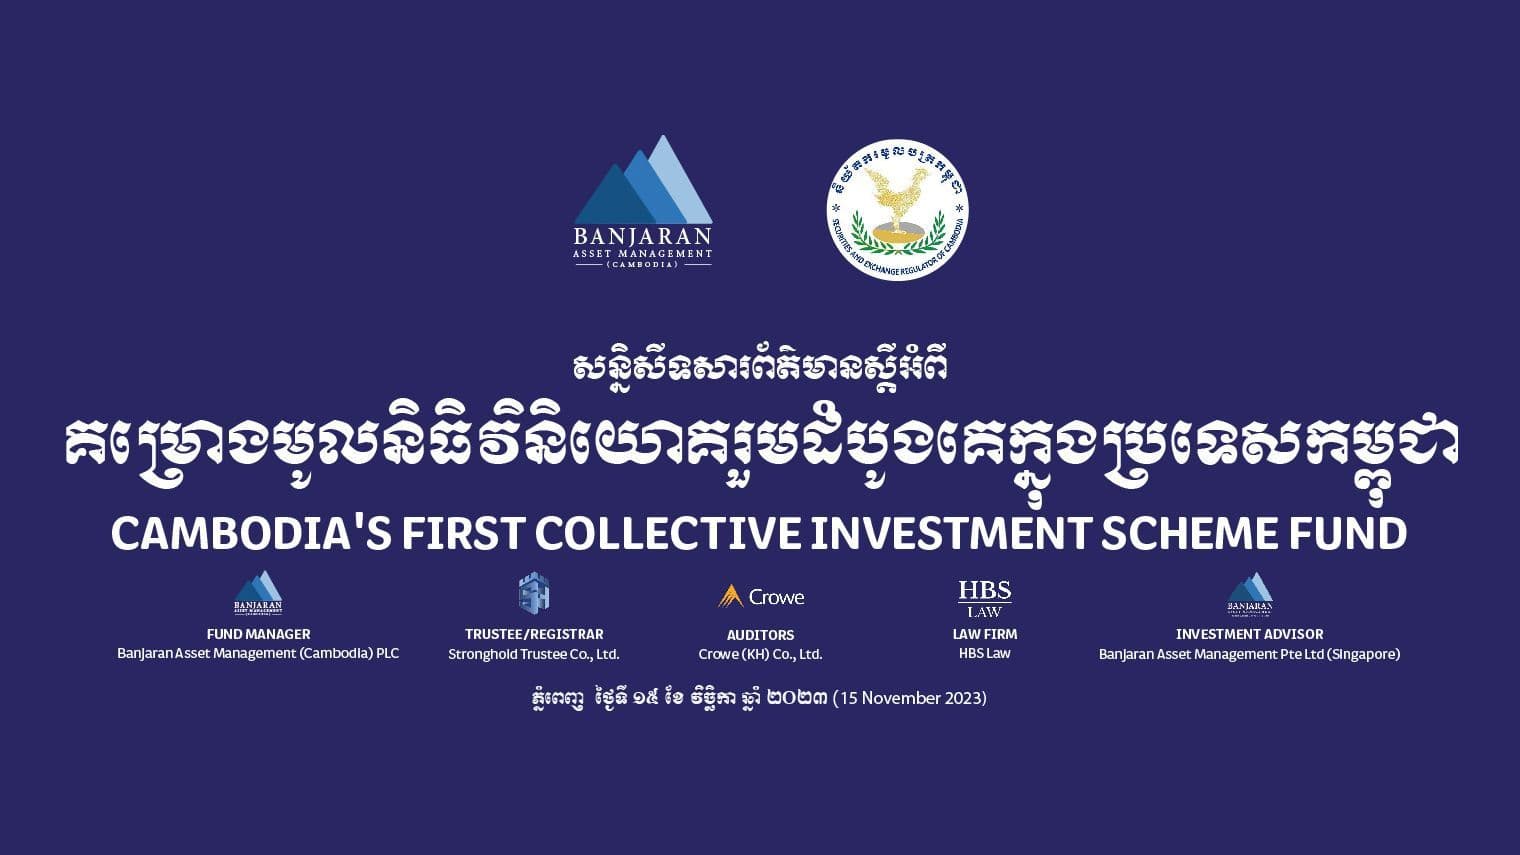
Press Conference - Cambodia First Collective Investment Scheme Fund
Press Release Banjaran Asset Management (Cambodia) PLC (“BAMC”) has successfully obtained approval from the Securities and Exchange Regulator of Cambodia (“SERC”) to launch the BAMC Asia Equity Fund (“BAEF”) in the Kingdom of Cambodia. BAEF is the first retail fund to launch for sale in the Kingdom which the public will be able to invest in. BAEF is an investment fund investing in a diversified portfolio of companies listed on major stock exchanges across Asia Pacific Ex-Japan. The fund targets to provide the benefits of investing in Asia, which economists globally see as the premier growth region in the coming years. The fund’s tagline is “The Rise of Asia”. Being the first SERC-approved retail fund to launch in Cambodia, BAMC will give Cambodian investors, who to date have narrowly relied on bank deposits to grow their wealth, an opportunity to diversify their investments. In addition, Cambodians would no longer need to travel to foreign financial centers to access investment opportunities outside the Kingdom. BAEF is the first of a series of funds that BAMC plans to bring to the investing public in Cambodia. To make the fund accessible to all investors, BAMC has set the minimum investment amount at just US$500. BAMC is the fund manager of BAEF with Banjaran Asset Management Pte Ltd (“BAMPL”) of Singapore as the investment advisor. Stronghold Trustee Co., Ltd (“ST”) is the trustee of the fund. Her Excellency Chan Theany (“HE Theany”), Chairwoman of BAMC said: “We are honored and happy to be the first fund management company in Cambodia to successfully launch a SERC-approved public collective investment fund. I am proud to report that in the process of obtaining the various licenses and approvals, we have trained a team of local Cambodians to take on various roles in the areas of asset management. For the launch of BAEF, we have brought in international fund management expertise and its best governance practices. We hope this will set a high standard for the asset management industry going forward.” Mr. Aaron Ng (“Aaron”), CEO of BAMPL said: “BAMPL is proud to be the investment advisor to BAEF, Cambodia’s first approved public investment fund. We have extended our experiences, international practices, and best governance practices to BAMC. We offer our best wishes to BAMC on this launch.” About BAMC Asia Equity Fund (“BAEF”) The BAEF is an investment fund that invests in stocks listed in major stock exchanges in Asia Pacific Ex-Japan. It aims to deliver an expected return of 7-10%* per annum over the medium to long term. The Fund is expected to be diversified with at least 30 stocks across Asia (eg. Singapore, Hong Kong/China, Australia, Thailand, Malaysia, Indonesia, Philippines, etc.) and across various sectors (eg. Banking, Property, Industrials, Consumer, Telecoms, Technology, etc.). The Fund is domiciled in the Kingdom of Cambodia and is USD-denominated. The Fund will accept subscriptions and redemptions daily and the daily unit price of the Fund will be available on various media channels. *- Investment return is not guaranteed. About Banjaran Asset Management (Cambodia) PLC (“BAMC”) BAMC was incorporated in the Kingdom of Cambodia in 2022 and holds a fund management license issued by the SERC to establish and manage a public funds of collective investment scheme. BAMC is a joint venture between Banjaran Holdings Pte Ltd from Singapore, Best Magnet Capital Co., Ltd, and Primo Plus Co., Ltd. Banjaran Holdings and BAMPL are related companies. About Stronghold Trustee Co., Ltd (“ST”) ST is the first Full-Licensed Trustee licensed by the Securities and Exchange Regulator of Cambodia and registered with the Trust Regulator. It specializes in trust services, including Collective Investment Scheme and Personal and Commercial trusts tailored to clients’ needs. ST is part of the Stronghold Group of Companies and has its roots in Taiwan. About Banjaran Asset Management Pte Ltd (“BAMPL”) BAMPL was incorporated in Singapore in 2014 and currently holds a Capital Market Services license in fund management issued by the Monetary Authority of Singapore. BAMPL’s main business activities are in investment management and its funds are distributed through private banks and investment banks across Asia and the UK. BAMPL is also a leading provider of multifamily office services in Singapore. BAMPL’s assets under management are approximately US$ 5 billion (as of 30 June 2023) in a variety of asset classes. These include private and listed equities, private and listed debts, alternative investments, ESG-focused investments, and real estate investments. More News EAC News Kampuchea Thmey Fresh News Asia TNAOT Jia Hua Daily Cambodia Express News Khmer Times Phnom Penh Post Sabay News Kiri Post Securities and Exchange Regulator of Cambodia (SERC) Cambodia Investment Review BTV News
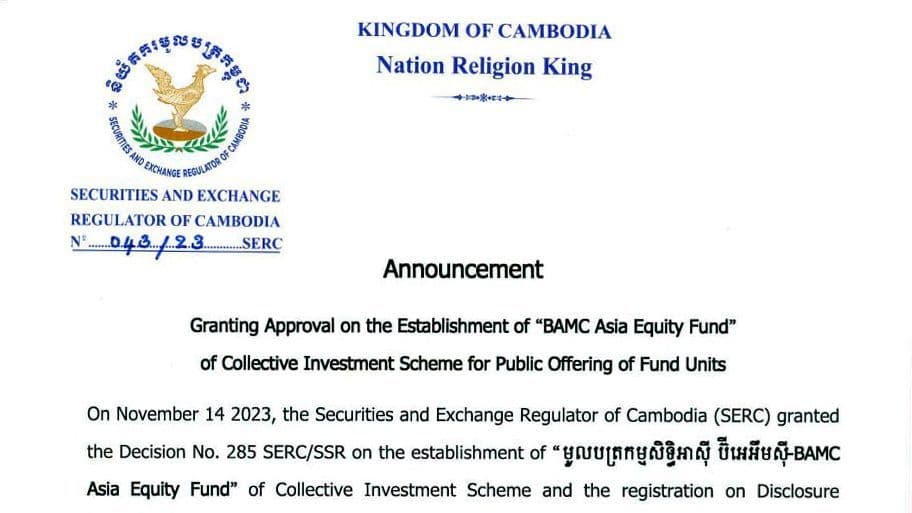
SERC Approves BAMC Asia Equity Fund for Public Offering
Phnom Penh, Cambodia – The Securities and Exchange Regulator of Cambodia (SERC) has officially granted Decision No. 285 SERC/SSR for the establishment of the “មូលបត្រកម្មសិទ្ធិអាស៊ី ប៊ីអេអឹមស៊ី - BAMC Asia Equity Fund” as part of the Collective Investment Scheme. This landmark decision also includes the registration of the Disclosure Document (Prospectus) for the public offering of fund units managed by Banjaran Asset Management (Cambodia) Plc. The BAMC Asia Equity Fund marks a significant advancement in Cambodia's financial landscape, providing local and international investors with diverse investment opportunities. This fund is designed to enhance access to capital markets and promote economic growth in the region. Banjaran Asset Management (Cambodia) Plc is committed to upholding the highest standards of fund management and governance practices. With the approval of the BAMC Asia Equity Fund, the company aims to contribute positively to the development of Cambodia’s capital markets and provide investors with innovative investment solutions. The launch of the BAMC Asia Equity Fund is expected to set new benchmarks for collective investment schemes in the Kingdom, fostering a more vibrant and inclusive financial services sector. Further updates regarding the fund's public offering will be announced soon.
Investment Education Series related to Collective Investment Scheme (Part One)
Investing in Legitimate Investment Products According to published figures by the World Bank, Cambodia's GDP per capita has risen from US$783 (2010) to US$1,625 (2021). Statista.com projected that its GDP will continue to grow to approximately US$2,656 by 2028. The growth in the middle income and increase in wealth of the average Cambodian will naturally bring about the need for investing. However, recently we have also seen a spike in cases of reported fraudulent and failed investment schemes, as well as some which are outright scams. When investing, investors are traditionally enticed by high returns and a sense of familiarity. Very often they ignore what is perhaps the most important factor when investing, which are the risk factors. Risk comes in many forms, to name a few: Counterparty Risk Market Risk Currency Risk Liquidity Risk Regulatory Risk Specific Risk Environmental Risk Bankruptcy Risk Operational Risk Based on past data, it is evident that there is a direct relationship between risk and return. The higher the return from a particular investment, the risk becomes higher. We can illustrate this in a simple graph. Generally, to mitigate the risk, investments should be made on or above the line. Furthermore, investors should select legitimate investment products. ❖ Legitimate investment products (Regulated) When investing, investors should consider whether the investment scheme is regulated, unregulated, or an outright scam. Regulated investment products are generally subject to onerous supervision by the country’s regulators. This makes regulated investment products safer choices compared to the others. A regulated investment product will generally have these features: Approval from the regulator Managed by a licensed fund manager Proper legal documentation and disclosures and will normally be audited by an audit firm accredited by the regulator. Therefore, the risk of a regulated investment scheme being a fraud is very low. ❖ The update of the Cambodia Collective Investment Scheme Market Acknowledging the potential of the collective investment scheme market for economic growth, the Securities and Exchange Regulator of Cambodia (SERC), a sole regulator to regulate, supervise, and develop the securities market in Cambodia has developed the infrastructure to launch this market through the adoption of the Prakas to regulate this market. As a result, on May 29, 2018, SERC adopted the Prakas on “Licensing and Supervision of Collective Investment Scheme Business” to allow companies to apply for a license or approval from the SERC to conduct the Collective Investment Scheme Business. As of Q3 2023, SERC has provided license/approval to 16 fund management companies, 8 trustees, 5 fund distribution companies, and 3 fund administrators. In addition, on July 20, 2023, SERC also adopted the Prakas on “The Issuance of Fund Unit of Collective Investment Scheme”. This Prakas determines the condition and requirement to issue fund units of the collective investment scheme and the post-issuance operation to ensure the orderliness, accountability, and transparency in the market and, most importantly to protect all market stakeholders including investors. ❖ Unregulated Investment Products Unregulated investment schemes are generally operating companies offering high returns and are only governed by the basic corporate regulations. Scams and unregulated investment schemes are often difficult to differentiate. These investment schemes generally have the following features: The promise of unusually high returns (too good to be true because the risk may be extremely high), Poor documentation (hidden risks and hidden costs are not disclosed), Managed by a small team of individuals (usually with exaggerated backgrounds), No proper third-party verification (not audited – all done by one company). Most importantly, there are no regulators to supervise the legitimacy of the investment schemes. ❖ Scams or Fraudulent Investment Schemes These are recent cases of unregulated investment schemes that have gone bad in Cambodia: The International Forex Trading case of 2019, in which the scheme was operated by a small group of individuals making promises of very high returns. There were no checks and balances and the company was in charge of both making the investment as well as issuing cheques to investors. Such unregulated companies, when unchecked by an independent third party can make false and exaggerated claims. In the Empire Big Capital Limited and Investment Consultant Association case of 2017, again this scheme was operated by a small group of individuals making promises of very high returns (10% per month). Similar to the previous case, there were no checks and balances, the company basically did everything internally. There were also reports of land investment schemes that have turned sour and were alleged to be fraudulent. Some of these operators have been arrested and charged, and some jailed. The alleged land investment scheme always promised high returns. There is a lack of transparency in how the funds were invested and with regard to the progress of the projects and their cashflows. It is important to note that there is a difference between an investment scheme going bad and it being an investment scam. All investments have to take risks to generate returns. There are many examples of investments going bad due to poor market conditions and other reasons. Scams happen when there is no real intent to channel money collected from investors into the stated investment. Instead, profits are fictitiously generated by using money from new investors to pay previous investors. This is known as a Ponzi scheme. Scam operators are in all instances not approved by regulators. ❖ Conclusion In seeking legitimate investments, investors should consider the following: Is the company regulated by the relevant authorities? Is the product approved by the relevant authorities? Does the investment reasonably justify the return that is promised? Does the collective investment scheme have basic checks and balances, like independent lawyers, auditors, and other professionals? Lastly, trust your instincts. If an investment sounds too good to be true, you should investigate further and ask more questions. In selecting a legitimate investment that fits your risk profile, the investment should diversify your risk and at the same time help you grow your wealth over time. An article from the Securities & Exchange Regulator of Cambodia (SERC)
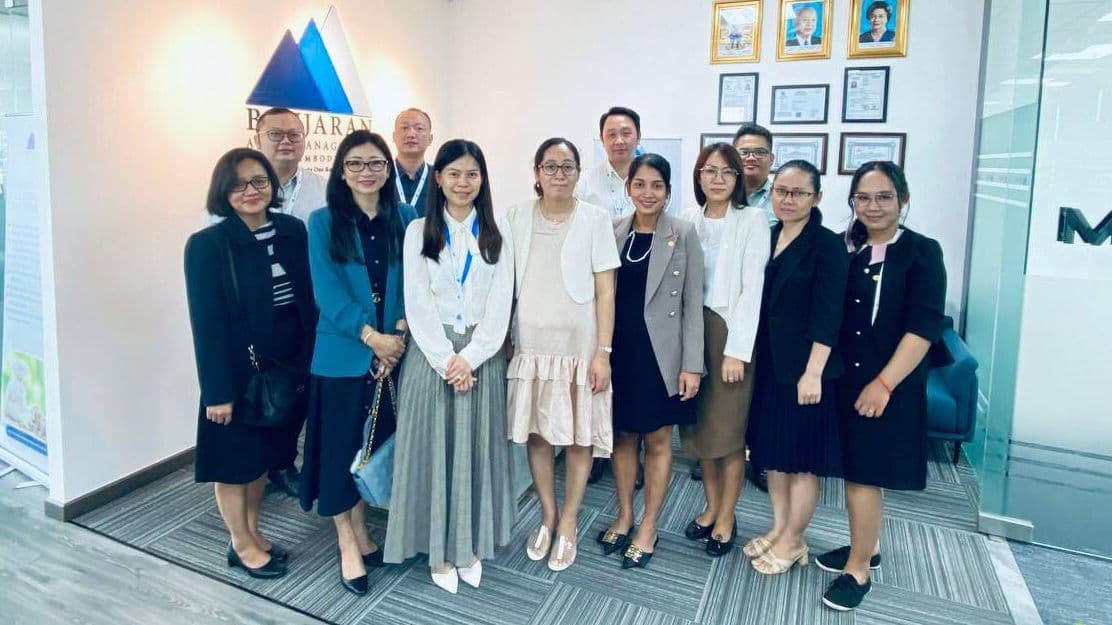
Banjaran Asset Management Submits BAMC Asia Equity Fund for Collective Investment Scheme Approval to SERC
Phnom Penh, Cambodia – Banjaran Asset Management (Cambodia) Plc. has taken a significant step forward in the financial sector by submitting the application for its BAMC Asia Equity Fund for fund unit offering approval. The submission falls under Cambodia's Collective Investment Scheme (CIS) regulatory framework, reflecting the company's commitment to providing robust investment opportunities in the region. The inspection of the application was conducted by Her Excellency Thay Sokphalline, Director of the Securities Issuance Department, along with a team of officials from the Securities and Exchange Regulator of Cambodia (SERC). The comprehensive review marks an important milestone for the BAMC Asia Equity Fund, which aims to broaden access to diverse investment portfolios, catering to the growing demand for equity investment solutions in Asia. The BAMC Asia Equity Fund represents a pioneering effort in Cambodia’s capital market landscape. Banjaran Asset Management remains confident that this offering will contribute to the country’s economic growth by attracting both domestic and international investors. With a strategic focus on high-growth sectors across the Asia region, the fund is poised to deliver long-term returns for investors while strengthening Cambodia’s position in the global financial market. Banjaran Asset Management (Cambodia) Plc. continues to work closely with regulatory bodies to ensure compliance with all legal and financial guidelines. Pending approval, the BAMC Asia Equity Fund will be the first of its kind in the Cambodian market, marking a significant achievement in the country's financial sector development. For further updates and details, please stay tuned for official announcements from Banjaran Asset Management and the Securities and Exchange Regulator of Cambodia (SERC).
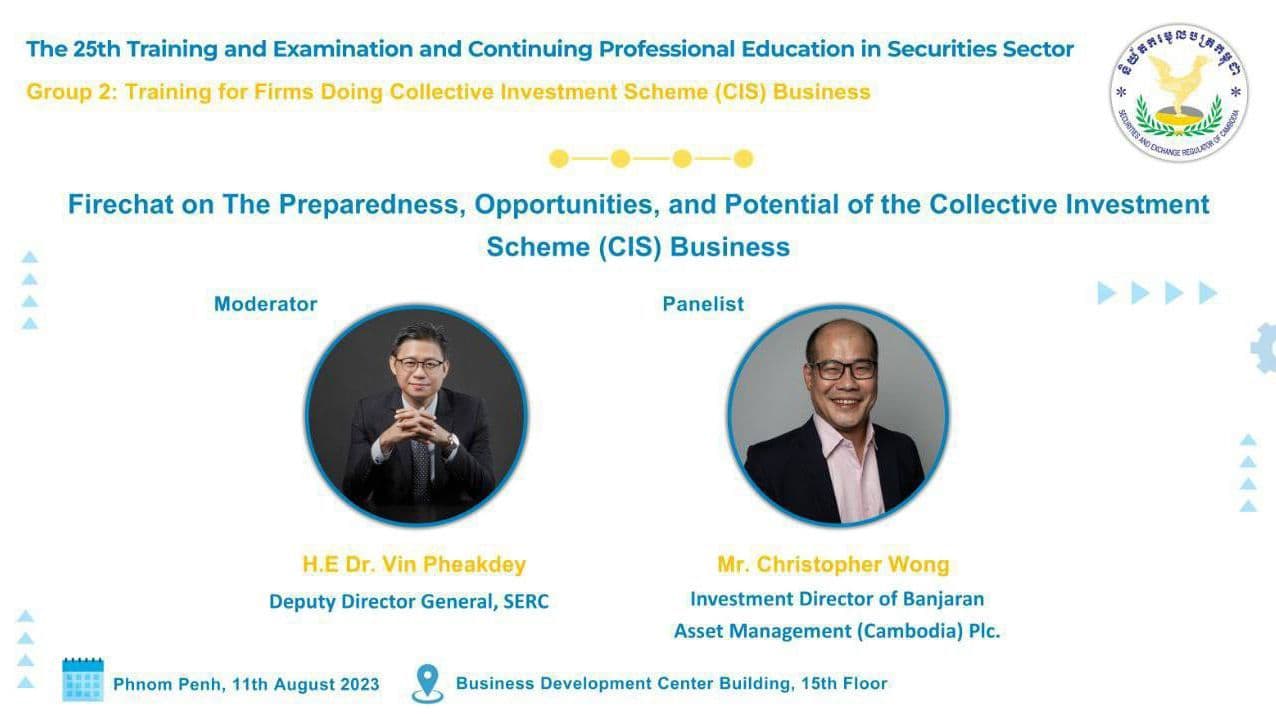
Firechat on The Preparedness, Opportunities, and Potential of the Collective Investment Scheme (CIS) Business
Phnom Penh, Cambodia – Mr. Christopher Wong, Investment Director of Banjaran Asset Management (Cambodia) PLC, participated in a dynamic discussion titled “Firechat on The Preparedness, Opportunities, and Potential of the Collective Investment Scheme (CIS).” The event was moderated by H.E. Dr. Vin Pheakdey, Deputy Director General of the Securities and Exchange Regulator of Cambodia (SERC). The discussion focused on the evolving landscape of collective investment schemes in Cambodia, emphasizing the importance of regulatory preparedness and the potential for economic growth through these investment vehicles. Wong shared his expertise on the opportunities that CIS presents for both local and international investors, highlighting its role in enhancing capital access and promoting financial inclusion in the country. The event also provided a platform for industry stakeholders to engage in dialogue about the challenges and opportunities within the investment sector. Wong's insights contributed to a deeper understanding of how collective investment schemes can be leveraged to strengthen Cambodia's financial markets. As the country continues to develop its capital markets, such discussions are crucial for fostering collaboration among regulators, investors, and industry leaders. Banjaran Asset Management (Cambodia) remains committed to participating in initiatives that promote a robust investment environment and advance the nation’s financial services sector. Firechat on The Preparedness, Opportunities, and Potential of the Collective Investment Scheme (CIS) Business.
ទស្សនៈទីផ្សារ
2024 April, Market Outlook: Navigating Volatility Amidst Inflation, Interest Rates, and Geopolitical Risks
Recently, both the bond and stock markets have experienced heightened volatility, driven by inflation and retail sales in the US consistently exceeding expectations. In response, the Federal Reserve once again opted to hold off on lowering interest rates, waiting for more comprehensive data before making further policy decisions. This cautious approach led investors to adjust their interest rate forecasts aggressively, which directly impacted equity markets. We believe these concerns are justified, especially as commodity prices have surged, potentially contributing to higher inflation in the months ahead. At present, we assess that the recent equity price movements may be a short-term reaction to rising bond yields, and we will continue to monitor these trends closely. In China, the government's initiative to support "whitelist" property projects has made significant progress, with funds raised reaching RMB 469 billion by the end of March—more than double the RMB 200 billion previously reported. Given the size of China’s residential property sector, we anticipate further substantial disbursements. Additionally, there is an expectation that the People’s Bank of China will gradually increase government bond trading through its open market operations, signaling a form of monetary policy easing. These developments, along with China's Q1 GDP growth and improved PMI numbers, offer positive signals for the economy. However, we recognize initial signs of a slowdown in key economic indicators, such as retail sales and industrial production, reflecting lingering sluggishness in the domestic economy. We will continue to track these factors in the coming months. On the geopolitical front, tensions between Iran and Israel are escalating, with Israel considering its response to recent drone strikes by Iran. This situation could significantly impact crude oil prices, introducing further inflationary risks in the near term. Meanwhile, the ongoing US-China tensions remain a long-term issue. Recently, US lawmakers introduced a bill that would bar mutual funds from investing in indices that include Chinese stocks. This follows a broader trend of global portfolio allocations shifting away from China over the past year. As a result, we have observed a substantial valuation premium in the US market relative to China, far exceeding historical norms. We believe that once the Chinese economy stabilizes and returns to sustainable growth, this valuation gap may narrow. In the near term, inflationary risks in the US and uncertainty in China could present challenges for equity markets. However, our analysis of current data suggests that this may be a temporary correction, largely driven by high valuations in developed markets. We remain focused on identifying attractive opportunities as they emerge in the evolving market landscape.
2024 March, Market Outlook: Navigating Elevated Interest Rates, China’s Economic Measures, and Corporate Earnings
Throughout the month, the Federal Reserve reinforced its stance that there is no urgency to lower interest rates during the first half of 2024. Notably, the Fed addressed growing concerns within the commercial real estate sector, acknowledging that while the situation remains manageable for now, it may lead to further banking failures. This dovetails with our cautious outlook on the potential consequences of keeping interest rates elevated for too long, especially if policy missteps occur. High rates for an extended period could stress certain sectors, particularly real estate, heightening risks within financial markets. In China, the government has begun to take action to support previously announced “whitelist” property projects. Major commercial banks have approved over RMB 200 billion in loans to facilitate the completion of these projects. While this is a positive step, further financing will likely be necessary to ensure sufficient liquidity for the real estate sector's recovery. We will continue to monitor further policy announcements and their impact on property sales and prices in the coming months. The recently concluded "Two Sessions" meeting of the Chinese Communist Party revealed economic targets similar to those set last year. The 5.0% GDP growth target for 2024 appears ambitious, especially in light of the modest 3.0% deficit target and the conservative spending habits of Chinese consumers. However, we believe this growth target is achievable, given the gradual shift in consumer behavior towards increased spending. Furthermore, growth outside of the real estate sector remains robust, offering a positive outlook for broader economic recovery. In the corporate world, recent earnings reports from leading companies have generally shown strong growth for Q4 2023, with some projecting modest top-line expansion in 2024. However, US stocks that missed earnings expectations and guidance experienced sharp declines, a consequence of their elevated valuations. Given the uncertain economic outlook, we will closely monitor both economic and industry-specific data to inform our next portfolio decisions. Despite these short-term uncertainties, we remain positive about the long-term potential of our holdings. In conclusion, as central banks maintain a cautious stance on interest rates and China accelerates its economic support, global markets face a delicate balancing act in 2024. Careful navigation through these challenges will be key for investors seeking sustainable growth opportunities.
2024 February, Market Outlook: Navigating Central Bank Strategies and Growth Opportunities in Asia
As we step into 2024, initial hopes for early interest rate cuts by the US Federal Reserve (FED) and the European Central Bank (ECB) are fading. Both central banks have downplayed the likelihood of reducing rates anytime soon, largely due to strong economic data released in recent months. The US economy continues to display resilience, with sustained expansion indicating that the FED must tread carefully. Lowering interest rates too soon could risk reigniting inflation, which the central bank is keen to avoid. At the same time, there are pockets of weakening growth within the economy, signaling the potential for a broader slowdown. This delicate balancing act places the FED in a challenging position, where policy mistakes could have significant consequences for both the US economy and global financial markets. In line with our earlier expectations, the Eurozone also faces similar inflationary pressures, with energy prices remaining persistently high. As a result, inflation remains sticky, preventing the ECB from easing rates. We foresee that both central banks will need to remain vigilant in navigating the complex dynamics of their respective economies, weighing inflation risks against the threat of economic slowdowns. Meanwhile, China's approach to monetary policy has taken a markedly different turn. The Chinese government recently lowered the 5-year loan prime rate by 25 basis points to 3.95%, signaling its determination to stimulate the economy and support the real estate sector. Under the “whitelist” initiative, commercial banks are encouraged to provide lending to property projects approved by local governments. These rapid, proactive measures underscore the government's commitment to front-loading stimulus to prevent weak sentiment in the housing market from deepening. We believe these policies will continue to evolve progressively, ensuring that the real estate sector stabilizes and recovers on a sustainable path. Signs of improvement are already emerging in China’s economy. Recent data on monetary aggregates indicate positive movement, and domestic travel and spending during the Lunar New Year suggest a rebound in consumer activity. On the global stage, China’s exports have grown for the second consecutive month in December 2023, further reinforcing the positive outlook for 2024. These rapid policy moves come as the State Council calls for "forceful measures" to restore confidence in both the economy and financial markets. Japan is also showing signs of strength, with the economy benefiting from long-anticipated corporate reforms. After decades of deflation, Japan appears to be breaking free from this prolonged economic phase. Reforms aimed at improving corporate profit margins and shareholder returns are finally coming to fruition, marking the end of the country's 30-year deflationary struggle. We believe these developments will unlock significant value for shareholders, creating opportunities for growth in the Japanese market. In summary, we remain optimistic about the prospects for the Asian markets, particularly as China and Japan implement aggressive economic measures. Conversely, we approach the US markets with caution, given the headwinds presented by inflationary pressures and an overconcentration in the technology sector. As we move forward, the balancing act between growth, inflation, and central bank policy will continue to shape the global market landscape, with Asia emerging as a bright spot for investors in 2024.
2024 January, Market Outlook - Navigating 2024 Amid Geopolitical Tensions and Economic Shifts
As we enter 2024, the global financial landscape is expected to shift focus from rising bond yields to interest rate stabilization and potential easing, particularly by the US Federal Reserve. After three years of tightening policies, we anticipate that both the US and Europe will experience sharply slower economic activity and increased unemployment. Europe, in particular, faces heightened risks of a prolonged recession. While interest rates in the US may hold steady for now, primarily due to persistent inflation pressures in areas like housing, rising geopolitical risks, such as recent airstrikes by the US and UK in response to Houthi rebel attacks, could lead to disruptions in global trade and shipping costs. Geopolitical Tensions: The US-China Factor Geopolitical developments, especially the enduring US-China tension, will be a critical driver in assessing global economic and financial market performances. The ongoing decoupling between the two economic giants, particularly in the semiconductor industry, presents both challenges and investment opportunities. We foresee increased innovation stemming from this geopolitical divide, providing promising prospects in certain sectors. The AI Revolution: A Long-Term Investment Opportunity The advent of generative artificial intelligence (AI), epitomized by innovations like ChatGPT, has sparked widespread interest in AI-driven technologies across industries. While the global addressable market for AI is still being estimated, we remain optimistic about its long-term growth potential. AI companies in our portfolio have already shown promise, and we continue to explore new investment opportunities in this space as AI applications expand. China's Economic Recovery: Stabilization Efforts China's economic recovery is gaining momentum, though the real estate sector remains a drag. However, recent fiscal and monetary policies have helped stabilize the situation. The Central Economic Work Conference's call for proactive fiscal expansion and real estate policy adjustments are positive signs for the market. China's central bank has also introduced liquidity-boosting measures, such as a 50 basis point reduction in the reserve requirement ratio and lower rates for loans to small firms. We believe these are incremental steps toward further stabilization, and we are optimistic about China's economic and market outlook in 2024. US Presidential Election: Market Implications This year’s US Presidential Election will undoubtedly shape economic policies and market directions, though we refrain from speculating on political outcomes. Instead, our focus remains on the data-driven economic and market trends, with a view that the US economy will increasingly look inward as the election approaches. Overall, we believe Asia, particularly China, remains a bright spot in the global economy, while the US and Europe may face slower growth and recessionary pressures. We remain vigilant in assessing geopolitical risks and continue to focus on sectors like AI and innovation, which offer long-term growth opportunities.
2023 December, Market Outlook: Asia Emerges as a Bright Spot Amid Global Economic Shifts
As 2023 draws to a close, the equity market has remained largely stable, with investors maintaining a preference for developed markets. While Asia Pacific markets have also posted positive returns, their performance still trails behind other regions despite notable improvements in economic data. This disparity is likely due to end-of-year dynamics such as tax-loss harvesting and institutional portfolio adjustments, or "window dressing," a common phenomenon seen during this period. Historically, such short-term volatility tends to carry over into January as fund managers rebalance their portfolios for year-end reporting. In developed markets, equity markets have experienced significant optimism since the Federal Reserve opted to hold interest rates steady for two consecutive meetings. This move has signaled to investors that the Fed's interest rate hike cycle may have peaked, fueling market euphoria. Additionally, concerns about a looming US recession have eased, with many economists now revising their forecasts toward a "soft landing" scenario, where economic activity slows but avoids a severe downturn. However, inflation in the US remains persistently above the Fed's 2% target, indicating that interest rates may stay elevated for an extended period. The future economic outlook remains uncertain, especially as housing inflation cools, but we believe that while the risk of a recession is still moderately high, it is unlikely to escalate into a systemic crisis. On the geopolitical front, China’s recent diplomatic overtures toward the US have been a positive development. Following Chinese President Xi Jinping's visit to the US last month, both nations have expressed a renewed commitment to peaceful cooperation. The resumption of military dialogue, after months of silence, signals China's intention to restore political ties with the US. Additionally, President Xi’s meeting with top US business leaders highlighted strong corporate support for continued engagement with China, despite ongoing geopolitical tensions. For instance, Mastercard's new joint venture with China's national transaction processor, NetsUnion Clearing, demonstrates the long-term business potential between the two countries, allowing Mastercard cardholders to enjoy seamless payments in China. Nevertheless, while these diplomatic efforts are encouraging, further reciprocal actions from the US government will be crucial to reducing geopolitical risks in the long term. With the US presidential elections on the horizon in late 2024, we expect China to remain a central theme in American political discourse, with both parties likely positioning the country as a major national security threat to garner electoral support. This political climate may perpetuate tensions, and as a result, we anticipate that geopolitical risks will remain elevated through 2024. Looking beyond the US, other significant elections, such as Taiwan's, will also play a key role in shaping geopolitical dynamics. As global security concerns intensify, we foresee a gradual restructuring of global supply chains, with capital and business operations increasingly shifting to countries deemed safer or more politically stable. This trend toward economic fragmentation will favor companies capable of maintaining market share and operational efficiency amid the reshoring of industries. In China, the recent Central Economic Work Conference concluded with the government setting a clear pro-growth agenda for 2024. Chinese policymakers are focusing on reviving confidence and stimulating economic growth through a series of supportive measures, including monetary, fiscal, and administrative interventions. These initiatives have been ramping up in intensity, and we anticipate additional measures in the coming months, particularly aimed at addressing risks in the real estate sector. Given these developments, we continue to see Asia, particularly China, as a bright spot for economic growth in the global economy. A lower interest rate environment, coupled with increased liquidity, should help alleviate financial pressures and reduce the debt burdens of companies and individuals. As the world economy navigates through geopolitical tensions and inflationary pressures, Asia remains well-positioned to drive global growth in the near term, making it a focal point for investors looking to capitalize on emerging market opportunities. In summary, while global economic conditions remain uncertain, Asia’s resilience, supported by pro-growth policies and improving economic indicators, offers a compelling investment case, even as geopolitical risks loom on the horizon.
2023 November, Market Outlook: Resilience, Stimulus, and Global Shifts
As we look ahead, the global market outlook remains shaped by several key developments. Despite geopolitical tensions and ongoing conflicts, such as the humanitarian crisis between Israel and Hamas, we expect limited broader economic impact due to stabilizing military presence and containment measures. The risk of a wider regional conflict appears low, preserving global market stability for the time being. US Economic Resilience and Slowdown Expectations In the US, resilience continues to be a dominant theme. While the Federal Reserve’s tightening measures have been in place since 2022, the financial system remains robust, supported by the aftereffects of COVID-19 stimulus and substantial fiscal spending by the US government. This liquidity, however, is expected to taper, with a corresponding economic slowdown projected over the medium term. Current forecasts suggest GDP growth of 0.7% in Q4 2023 and 0.3% in Q1 2024, indicating a likely deceleration in the coming quarters. China’s Recovery Gains Momentum China’s economy has begun to gain notable momentum, driven by improving retail sales, imports, and industrial output. The government has recently announced a significant RMB 1 trillion stimulus package to further bolster the recovery. However, investor sentiment remains cautious, keeping valuations suppressed relative to the US. We believe that this discrepancy is unsustainable and anticipate that over the medium term, valuations in China will close the gap, driven by stronger economic fundamentals. Japan’s Stimulus and Growth Prospects Japan is emerging as an intriguing opportunity as it moves away from years of deflation, with inflation now supported by demand. In response to weakening economic data, the Japanese government has introduced a US$ 110 billion stimulus package aimed at boosting private consumption. This should translate into economic growth in the near-to-medium term, further enhancing Japan’s market potential. Focus on Asia Amid Geopolitical Stability Asia remains our primary focus, especially in light of recent positive developments in China’s economic data and a decrease in US-China geopolitical tensions following the Biden-Xi meeting in San Francisco. Agreements between both countries signal a more stable relationship, reducing trade war fears and enhancing the region’s investment appeal. Overall, we maintain a cautiously optimistic view, focusing on opportunities in Asia while monitoring the evolving macroeconomic landscape.