

វិចារណកថា
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
បន្ទប់ព័ត៌មាន
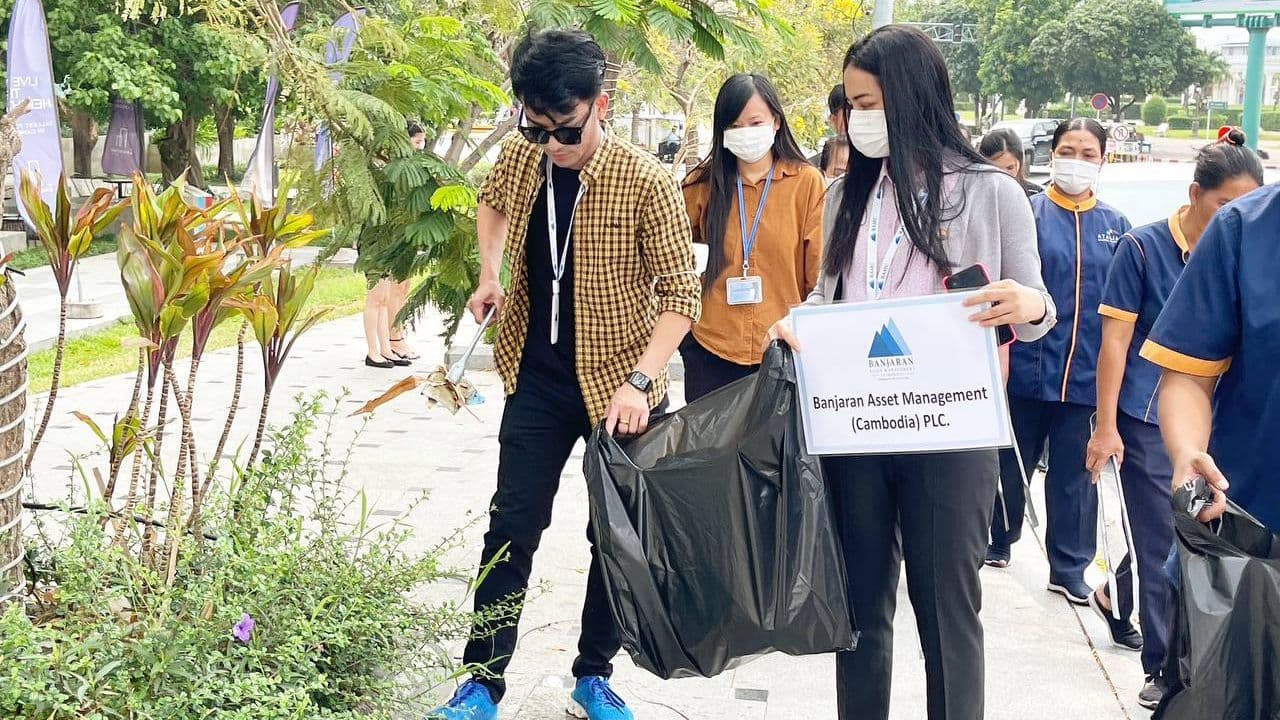
Banjaran Asset Management (Cambodia) Participates in Green Cleaning Event
Koh Pich, Phnom Penh – Banjaran Asset Management (Cambodia) PLC proudly participated in a Green Cleaning Event held on Diamond Island, reinforcing its commitment to environmental protection and sustainability. The event aimed to raise awareness about the importance of maintaining clean and green spaces while encouraging community involvement in environmental initiatives. During the event, employees from Banjaran Asset Management joined local volunteers and community members in various cleaning activities, including litter collection and environmental education sessions. This hands-on approach not only contributed to the beautification of Diamond Island but also served to educate participants about the principles of environmental stewardship and the necessity of preserving natural resources for future generations. “We believe that corporate responsibility extends beyond financial success; it includes being active stewards of our environment. By taking part in events like this, we hope to inspire others in the business community to contribute to a cleaner and greener Cambodia.” Ben Lee, Managing Director of Banjaran Asset Management (Cambodia), expressed pride in the company’s participation. The Green Cleaning Event showcased the importance of collective efforts in promoting sustainability, with various organizations and local government representatives coming together to set a positive example. Banjaran Asset Management’s involvement highlights its dedication to not only advancing financial services but also fostering a culture of environmental consciousness within the Kingdom. As part of its broader corporate social responsibility strategy, Banjaran Asset Management (Cambodia) aims to continue engaging in initiatives that benefit both the community and the environment, further establishing itself as a responsible leader in Cambodia’s financial sector.
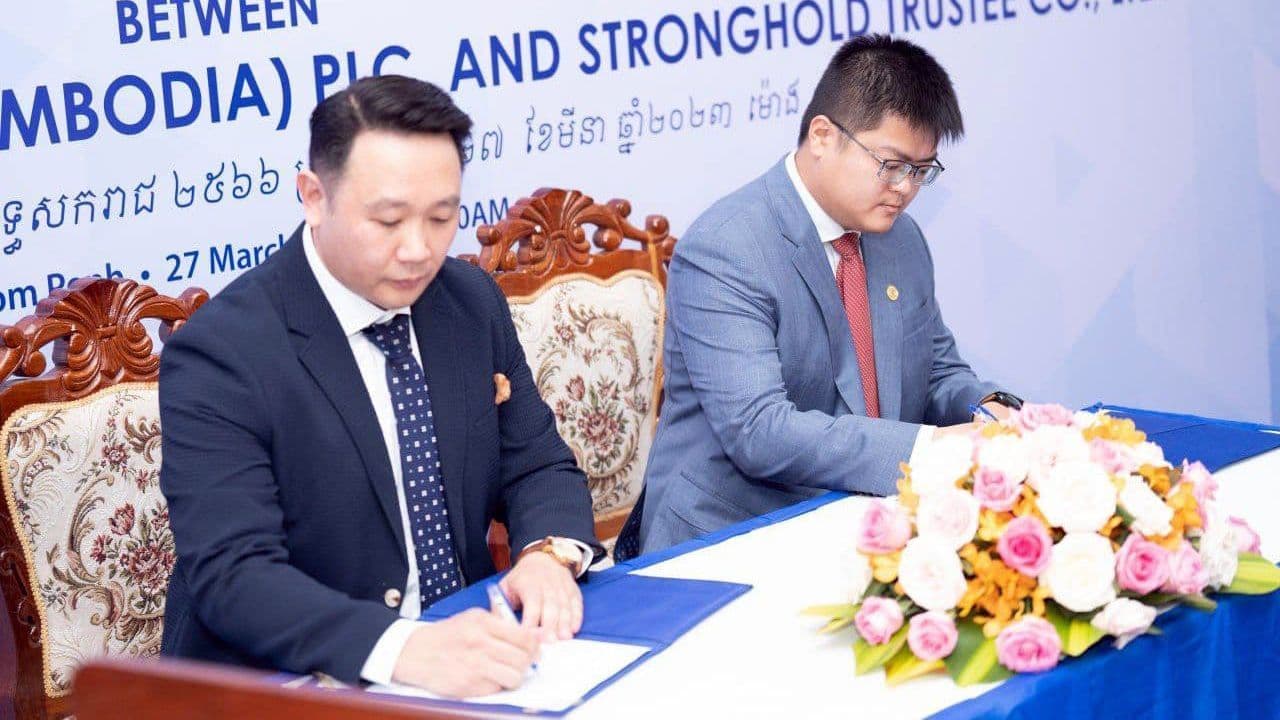
Banjaran Asset Management (Cambodia) and Stronghold Trustee Collaborate on Market-Leading Public Investment Fund
Phnom Penh - A significant signing ceremony took place between Banjaran Asset Management (Cambodia) PLC and Stronghold Trustee Co., Ltd. The event, presided over by H.E. SOU Socheat, Director General of the Securities and Exchange Regulator of Cambodia (SERC), alongside other key officials, marked the collaboration for launching Cambodia’s first public fund and collective investment scheme. Pending approval from the SERC, this initiative will be a landmark achievement in the Kingdom’s financial services sector, providing retail investors with alternative investment options beyond traditional bank deposits. The fund will be managed by Banjaran Asset Management (Cambodia), with Stronghold Trustee serving as the trustee and Singapore-based Banjaran Asset Management as the investment adviser. This collaboration will offer Cambodian investors access to international markets without the need to travel to financial centers like Hong Kong and Singapore. Hans Chen, CEO of Stronghold, expressed excitement for the launch, emphasizing the professionalism and expertise that Stronghold brings to the initiative. Ben Lee, Managing Director of Banjaran Asset Management (Cambodia), highlighted the incorporation of international fund management practices and the training provided to local professionals in the fund management ecosystem. Established in 2022, Banjaran Asset Management (Cambodia) operates under a fund management license issued by the SERC, as part of a joint venture with Banjaran Holdings Pte Ltd, Best Magnet Capital Co., Ltd, and Primo Plus Co., Ltd. Stronghold Trustee, the first licensed trustee under the Cambodian Trust Law, specializes in trust services tailored to client needs. With approximately $5 billion in assets under management, Banjaran Asset Management Pte Ltd (BAMPL) in Singapore further solidifies its expertise in investment management, offering a variety of asset classes. The launch of this public investment fund represents a pivotal step in Cambodia’s financial landscape, providing new wealth growth opportunities for local investors and setting the stage for future advancements in the sector. More News Cambodia Investment Review Securities and Exchange Regulator of Cambodia Trust Regulator
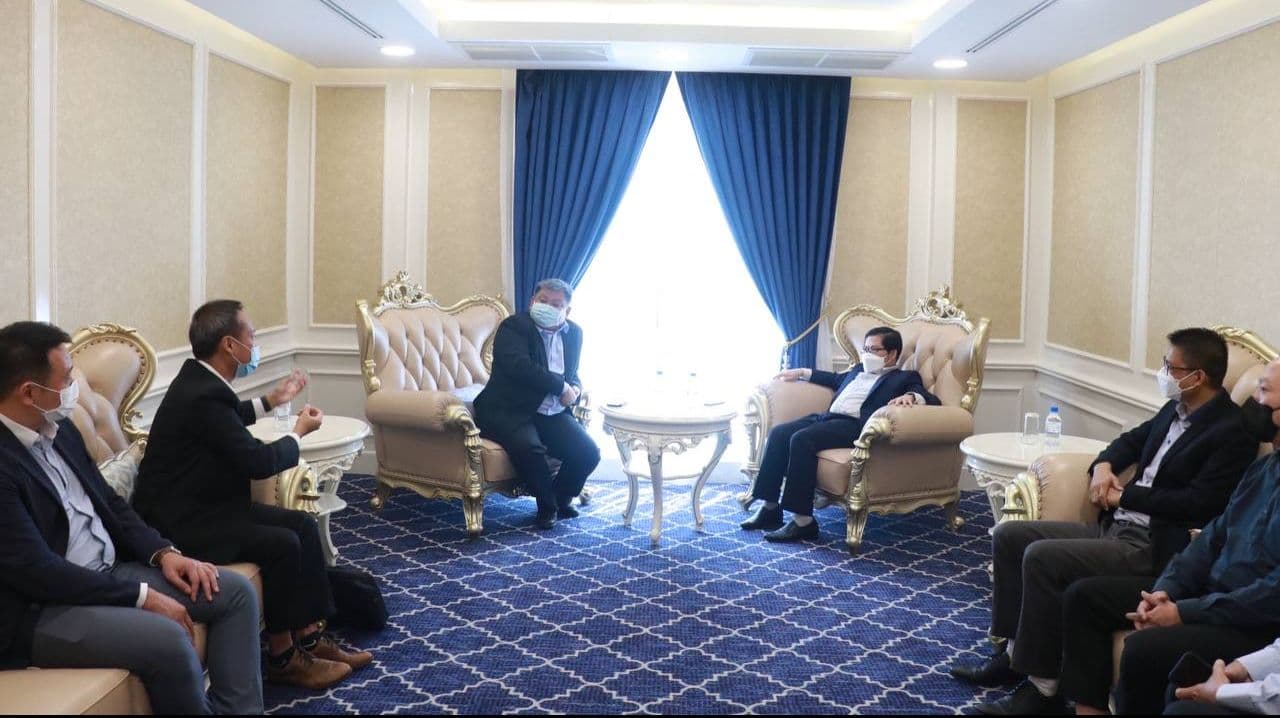
SERC Welcomes Singapore’s Banjaran Asset Management for Strategic Talks on Cambodia’s Securities Sector
04 May 2022, Phnom Penh In a notable demonstration of Cambodia's ongoing commitment to fostering the growth and modernization of its capital markets, His Excellency Sou Socheat , Delegate of the Royal Government in charge as Director General of the Securities and Exchange Regulator of Cambodia (SERC), together with His Excellency Dr. Vin Pheakdey , Deputy Director General of SERC, officially welcomed the executive leadership team from Banjaran Asset Management Pte Ltd (BAMPL), a Singapore-based asset management firm, during their visit to the Kingdom of Cambodia in May 04 2022. The visiting delegation was led by Mr. Aaron Ng , BAMPL CEO, and Mr. Low Hon-Yu Low , BAMPL Executive Director. The meeting served as a crucial platform to discuss strategic cooperation and potential business opportunities within Cambodia's developing securities sector. H.E. Sou Socheat provided a comprehensive overview of Cambodia's capital market, detailing its regulatory frameworks, investment climate, and institutional infrastructure. He underscored the government’s ongoing reforms aimed at ensuring transparency, protecting investors, and achieving international compliance, all designed to position Cambodia as an attractive emerging market. Discussions also focused on Cambodia's initiatives to deepen its market by diversifying financial instruments and encouraging participation from both domestic and international players. BAMPL expressed significant interest in exploring investment and operational opportunities in Cambodia, aligning with their broader Asia-Pacific strategy to expand their presence and offer diversified market access to investors. H.E. Dr. Vin Pheakdey further emphasized the importance of regulatory compliance, robust risk management standards, and continuous investor education. He assured BAMPL of SERC's support in facilitating responsible market entry for reputable foreign institutions. The BAMPL team shared insights into their business model, regional experiences, and their vision for contributing to Cambodia's capital markets. Their proposed business plan, including fund management and distribution services, were reviewed in detail. H.E. Sou Socheat concluded the meeting by providing constructive feedback and outlining the key regulatory requirements for licensing and operational approval. He offered practical guidance on navigating the legal and procedural aspects of establishing a presence in Cambodia’s securities sector, reaffirming SERC’s openness to engaging with serious investors and partners who align with Cambodia’s financial development goals. This meeting underscored Cambodia’s proactive efforts to foster a dynamic, inclusive, and internationally connected capital market, signaling its readiness for greater integration into the broader Asia-Pacific financial ecosystem. This paves the way for increased foreign investment, product innovation, and accelerated long-term economic growth beneficial to both local and global investors.
ទស្សនៈទីផ្សារ
2024 October Market Outlook: Hong Kong and China Stocks Await Policy Boost as AI Growth Persists in the US
Since the initial surge in the Hong Kong and Chinese stock market, significant profit taking has followed. Despite this, we maintain our view that company valuations in the region remains attractive. The main event that we are monitoring is towards the end of this month, where China holds their Politburo Standing Committee. We expect major stimulus measures to be announced given the state of their economy, and this should result in a positive impact to stock valuations. In the absence of strong stimulus measures, we will be reassessing our view on the region. We remain confident that investments in artificial intelligence (“AI”) applications will remain strong through 2025, driven by the industry's continued high-growth potential. While sales momentum has moderated, we believe this cycle has several more quarters of growth ahead. As a result, we believe that modest selloffs in the US technology sector are potentially attractive entry points.
2024 September Market Outlook: Tech Stocks Face Headwinds as AI Valuations Come Under Scrutiny
Since the last newsletter, technology stocks continued to underperform as investors began to question the premium valuations that these companies command since the start of the artificial intelligence (“AI”) narrative. There is no doubt that AI will result in long-term productivity gains as more companies begin to announce standalone AI products. Additionally, continued improvements in AI hardware will likely accelerate development going forward. As we assess the current investment landscape, we anticipate the road forward for AI-related opportunities to be less smooth than the past year as investors increasingly scrutinize the potential for these AI investments and applications to deliver solid returns. We believe that the first to see widespread AI adoption would be in areas that provide support in pattern recognition and personal assistance. These applications, while not entirely new, have progressed significantly over the past year. To illustrate, Salesforce has recently announced Agent Force, a client servicing bot that is easily customizable for different industry applications. Compared to older chatbots, early adopters of Agent Force have seen a 40% improvement in customer query resolution. In healthcare, doctors are also increasingly using AI to assist with effective diagnosis and drug development. We are well positioned to benefit from increasing AI adoption over the long-term on this front. Where we are looking to gain additional exposure is in AI-related hardware. We are tracking several data center equipment and power management companies. However, these sectors in general are trading at a high premium and are already well-invested. We believe we should take a more considered approach prior to initiating a significant position given the high valuations. The AI landscape is undoubtedly changing very quickly, and we will be flexible on our positions depending on the developments that unfold going forward.
2024 August Market Outlook: Yen Carry Trade Unwinds, Sparking Global Market Shifts
Early in August, equity markets experienced a sudden spike in volatility, where volatility reached levels unseen since the COVID-19 crash. This was caused by a significant unwinding of the Yen carry trade. The unwinding was triggered after the Bank of Japan (“BOJ”) unexpectedly raised interest rates, where a sharp appreciation in the Japanese Yen followed. Traders who borrowed Yen cheaply then had to sell off their investments to pay back their borrowings. The situation worsened when weaker-than-expected US employment data caused the greenback to depreciate further against the Yen. Shortly after the sharp market decline, the BOJ has given comfort to the public that they will not hike interest rates further while financial markets are unstable. Thus, we are of the opinion that as of now, the carry trade should not cause further volatility. We are cautiously optimistic about the market consolidation. The reason for the caution is due to the still high valuation of the broad US equity market despite increasingly slowing fundamentals and economic data. We will continue to watch near-term trends given that a broad recovery in equity markets normally results in bullish short-term sentiment.
2024 July, Market Outlook: Mixed Signals from China and Cautious Optimism in the US
China’s economic landscape continues to be buoyed by its manufacturing sector, while consumer spending remains notably sluggish. Recent data reveals that retail sales growth has fallen short of expectations, with the latest Q2 Gross Domestic Product (GDP) reading showing a deceleration to just 4.7% year-on-year. However, there are encouraging signs in the property market; easing measures on homebuying has resulted in a significant uptick in secondary property sales in tier-one cities, which jumped by double digits. While this early data is promising, we remain cautious. Our previous observations indicate that any increase in home sales following the significant relaxation of restrictions in 2023 was short-lived. Therefore, we will closely monitor the outcomes of the upcoming Third Plenary Session, which will shed light on the policies that will shape China’s economic future. In the United States, we maintain a cautious stance regarding the medium-term economic outlook. The deceleration in growth and rising unemployment trends have yet to raise alarms among investors, primarily due to the robust inflow of investments related to artificial intelligence. Over the long term, we believe that fiscal dominance will be a critical factor, as the Congressional Budget Office projects that debt-to-GDP ratios could soar from around 120% today to 200% within the next 30 years. This projection raises valid concerns about the sustainability of the US economy. However, we posit that the current status quo could persist longer than anticipated. History shows that attempts to time market peaks often lead to substantial opportunity costs. Thus, we will continue to invest in US firms while remaining vigilant about potential de-dollarization and long-term debt risks. Following recent testimonies from the Federal Reserve regarding their readiness to lower interest rates, combined with market expectations of a potential Donald Trump victory in the upcoming presidential election, we have witnessed a noticeable rotation into smaller-capitalization stocks. These stocks have underperformed the Standard & Poor’s 500 Index since the COVID-19 pandemic heavily impacted their operations. Market sentiment seems to be favoring a "no landing" scenario, where small businesses could benefit more from lower borrowing costs and increased fiscal spending compared to larger firms. However, we approach this sector with caution, particularly concerning smaller companies that have significant debt exposure, given our apprehensions about a global slowdown in demand. In conclusion, while China shows signs of resilience through its manufacturing sector and initial recoveries in property sales, the broader economic outlook remains mixed, requiring careful observation of forthcoming policy changes. Meanwhile, the US market, bolstered by AI investments and potential shifts in fiscal policy, is experiencing volatility as investors reassess their strategies in light of evolving economic indicators. As we navigate these complexities, our focus remains on identifying solid investment opportunities while balancing risks in an uncertain environment.
2024 June, Market Outlook: Semiconductor Surge, Fed Caution, and AI's Future Potential
The equity markets have continued to reach new highs, largely driven by the exceptional outperformance of semiconductor stocks. This concentrated movement suggests that investors are placing heavy bets on a few sectors, which may indicate underlying caution about the broader economy. While the semiconductor sector's growth has been impressive, this narrow market rally could be vulnerable to shifts in sentiment, making it essential for investors to stay vigilant. On the macroeconomic front, the US Federal Reserve has remained cautious, withholding any strong indication of interest rate cuts in the near term. Citing robust employment numbers and persistently high inflation, the Fed has expressed that it needs to see more data before making any moves. As businesses and consumers have so far shown resilience, many market analysts have pushed back their expectations of a potential recession. However, there are signs of softening in the labor market, with the US unemployment rate gradually climbing to 4%, up from a low of 3.4% in 2023. This could be a precursor to broader economic weakness, aligning with our view that the Fed may have room for at least one interest rate cut later this year. China’s market performance, by contrast, has started to lag after the initial wave of optimism following the government’s policy interventions aimed at stabilizing the property market. Profit-taking has emerged as a natural response to the sharp upward momentum in Chinese equities earlier in the year. While market participants are now in a holding pattern, awaiting further updates on the property industry, we maintain the view that China’s real estate challenges are unlikely to result in systemic risk. The Chinese government has shown a clear commitment to managing the situation and is expected to introduce further targeted measures as needed. In the technology sector, we are particularly optimistic about the long-term productivity gains that could arise from AI applications. For example, a recent study found that software developers using Microsoft's GitHub CoPilot—an AI-powered coding assistant—completed tasks up to 56% faster than those without the tool. This significant efficiency boost highlights the transformative potential of AI in the workplace. Expectations for AI are sky-high, with investment in hyperscalers projected to grow at an annual rate of at least 20% through 2030. While AI-driven automation in areas such as customer service, email summarization, and image generation is expected to yield cost savings, we believe the next major economic leap will come from advancements toward Artificial General Intelligence (AGI). Current generative AI models have made substantial progress in recent years but are still limited by their inability to adapt effectively when faced with queries outside their training data. The evolution toward AGI would address this limitation, enabling AI to perform a broader range of tasks with greater accuracy and versatility. Additionally, consumer applications of AI are somewhat constrained at present, as mobile hardware lacks the processing power needed to run AI-driven tasks efficiently. However, the sustained investment in AI technologies is already leading to rapid improvements, and we continue to monitor developments for potential investment opportunities as companies push the boundaries of innovation and find new ways to monetize AI advancements. In summary, while semiconductor stocks have driven much of the equity market gains in 2024, a cautious stance is warranted due to the concentration of market activity. The Fed's hesitance to cut rates amid a weakening labor market adds another layer of complexity. Meanwhile, China's property market stabilization efforts are ongoing, and AI’s long-term promise continues to excite, but its full potential may take years to materialize. As we navigate these shifting dynamics, we remain focused on identifying selective opportunities across sectors and regions.
2024 May, Market Outlook: Navigating Global Volatility and Strategic Opportunities
Global equity markets have staged a strong recovery from April's decline, buoyed by cooling US economic data and a wave of significant share buyback programs. We anticipate that this erratic market behavior will persist until there's more certainty regarding the timing of interest rate cuts, as investors eagerly respond to any hints of monetary easing. With the US elections approaching, we also expect heightened volatility as uncertainty around future government policies grows. In China, the government has taken direct action to restore confidence in the property sector. Restrictions on home-buying have been fully lifted in major cities like Xi’an, Hangzhou, and Chengdu, with further easing measures introduced elsewhere. More notably, the administration has launched a 300 billion RMB facility for local governments to acquire excess property inventory and convert it into affordable housing. This initiative has been well-received by market participants, leading to sharp price appreciation in China’s equity markets. However, we believe that for the facility to have a meaningful impact on the broader property sector, it will likely need to be expanded further. If these efforts are scaled up, property prices could stabilize, and consumer confidence may return. In addition, the Chinese government’s push for large-scale equipment renewals and trade-ins of durable consumer goods is aimed at boosting private consumption growth over the next few years. Other recent measures, such as removing mortgage rate floors and lowering downpayment rates, further signal China's commitment to supporting its economy. As Q1 earnings season concludes, we’ve observed mixed results from major US corporations. Consumer discretionary firms report slowing spending and a more selective consumer base, while companies with international exposure have commented on a slower-than-expected recovery from Chinese consumers. In contrast, US technology firms have maintained robust growth, particularly those benefiting from AI adoption. In China, a similar trend emerges: technology firms are expanding, while consumer spending remains tepid in most sectors. However, China's consumer base is on an upward trajectory, whereas the US is seeing a slowdown. Given the potential turning points in major global economies, we plan to be highly selective in both US and Chinese markets based on our current exposures. While economic data in Japan remains weak, we remain optimistic about the ongoing corporate governance reforms, which we believe will drive improved shareholder returns over the long term. Looking ahead, we remain focused on navigating these uncertainties and positioning ourselves to take advantage of selective opportunities in the evolving market landscape.