

វិចារណកថា
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
បន្ទប់ព័ត៌មាន
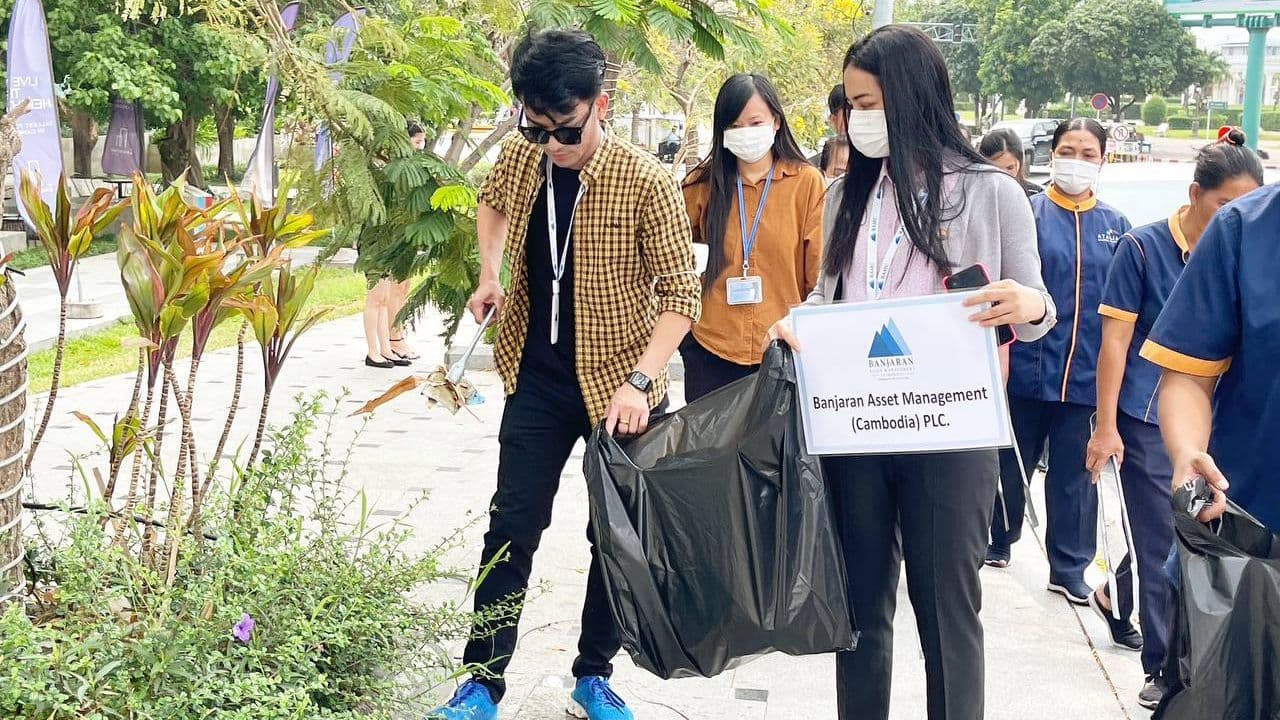
Banjaran Asset Management (Cambodia) Participates in Green Cleaning Event
Koh Pich, Phnom Penh – Banjaran Asset Management (Cambodia) PLC proudly participated in a Green Cleaning Event held on Diamond Island, reinforcing its commitment to environmental protection and sustainability. The event aimed to raise awareness about the importance of maintaining clean and green spaces while encouraging community involvement in environmental initiatives. During the event, employees from Banjaran Asset Management joined local volunteers and community members in various cleaning activities, including litter collection and environmental education sessions. This hands-on approach not only contributed to the beautification of Diamond Island but also served to educate participants about the principles of environmental stewardship and the necessity of preserving natural resources for future generations. “We believe that corporate responsibility extends beyond financial success; it includes being active stewards of our environment. By taking part in events like this, we hope to inspire others in the business community to contribute to a cleaner and greener Cambodia.” Ben Lee, Managing Director of Banjaran Asset Management (Cambodia), expressed pride in the company’s participation. The Green Cleaning Event showcased the importance of collective efforts in promoting sustainability, with various organizations and local government representatives coming together to set a positive example. Banjaran Asset Management’s involvement highlights its dedication to not only advancing financial services but also fostering a culture of environmental consciousness within the Kingdom. As part of its broader corporate social responsibility strategy, Banjaran Asset Management (Cambodia) aims to continue engaging in initiatives that benefit both the community and the environment, further establishing itself as a responsible leader in Cambodia’s financial sector.
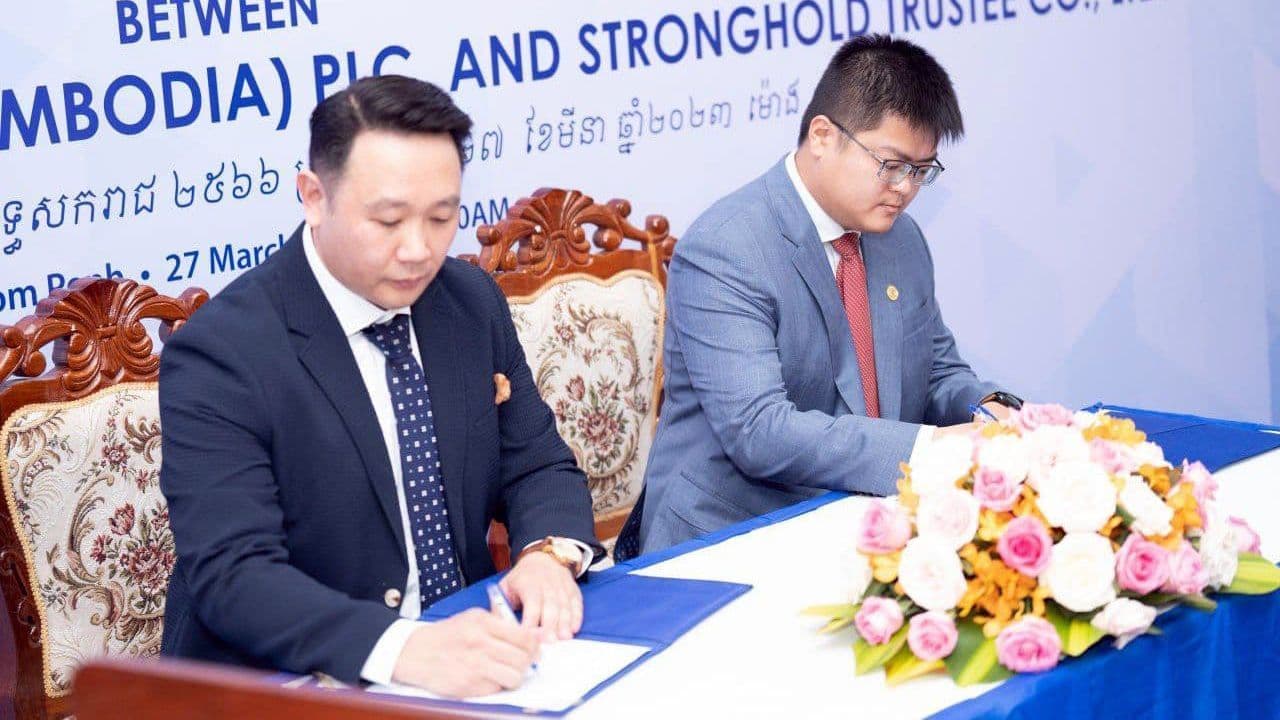
Banjaran Asset Management (Cambodia) and Stronghold Trustee Collaborate on Market-Leading Public Investment Fund
Phnom Penh - A significant signing ceremony took place between Banjaran Asset Management (Cambodia) PLC and Stronghold Trustee Co., Ltd. The event, presided over by H.E. SOU Socheat, Director General of the Securities and Exchange Regulator of Cambodia (SERC), alongside other key officials, marked the collaboration for launching Cambodia’s first public fund and collective investment scheme. Pending approval from the SERC, this initiative will be a landmark achievement in the Kingdom’s financial services sector, providing retail investors with alternative investment options beyond traditional bank deposits. The fund will be managed by Banjaran Asset Management (Cambodia), with Stronghold Trustee serving as the trustee and Singapore-based Banjaran Asset Management as the investment adviser. This collaboration will offer Cambodian investors access to international markets without the need to travel to financial centers like Hong Kong and Singapore. Hans Chen, CEO of Stronghold, expressed excitement for the launch, emphasizing the professionalism and expertise that Stronghold brings to the initiative. Ben Lee, Managing Director of Banjaran Asset Management (Cambodia), highlighted the incorporation of international fund management practices and the training provided to local professionals in the fund management ecosystem. Established in 2022, Banjaran Asset Management (Cambodia) operates under a fund management license issued by the SERC, as part of a joint venture with Banjaran Holdings Pte Ltd, Best Magnet Capital Co., Ltd, and Primo Plus Co., Ltd. Stronghold Trustee, the first licensed trustee under the Cambodian Trust Law, specializes in trust services tailored to client needs. With approximately $5 billion in assets under management, Banjaran Asset Management Pte Ltd (BAMPL) in Singapore further solidifies its expertise in investment management, offering a variety of asset classes. The launch of this public investment fund represents a pivotal step in Cambodia’s financial landscape, providing new wealth growth opportunities for local investors and setting the stage for future advancements in the sector. More News Cambodia Investment Review Securities and Exchange Regulator of Cambodia Trust Regulator
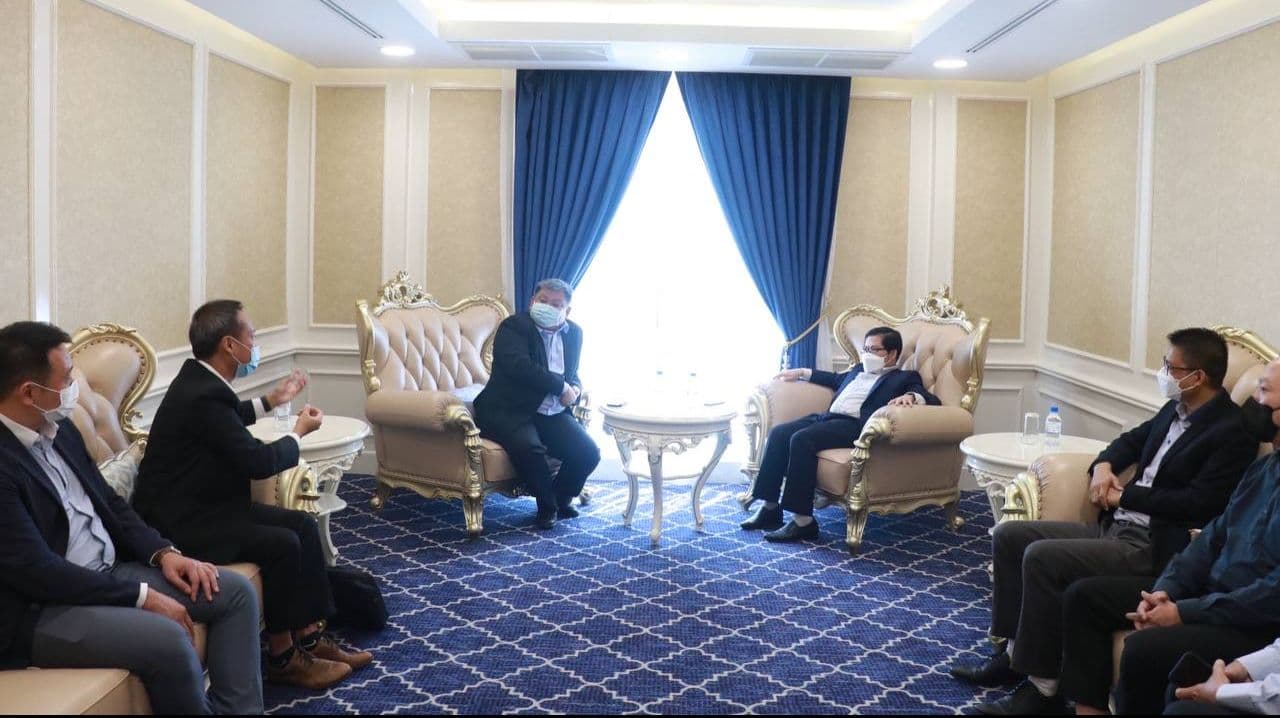
SERC Welcomes Singapore’s Banjaran Asset Management for Strategic Talks on Cambodia’s Securities Sector
04 May 2022, Phnom Penh In a notable demonstration of Cambodia's ongoing commitment to fostering the growth and modernization of its capital markets, His Excellency Sou Socheat , Delegate of the Royal Government in charge as Director General of the Securities and Exchange Regulator of Cambodia (SERC), together with His Excellency Dr. Vin Pheakdey , Deputy Director General of SERC, officially welcomed the executive leadership team from Banjaran Asset Management Pte Ltd (BAMPL), a Singapore-based asset management firm, during their visit to the Kingdom of Cambodia in May 04 2022. The visiting delegation was led by Mr. Aaron Ng , BAMPL CEO, and Mr. Low Hon-Yu Low , BAMPL Executive Director. The meeting served as a crucial platform to discuss strategic cooperation and potential business opportunities within Cambodia's developing securities sector. H.E. Sou Socheat provided a comprehensive overview of Cambodia's capital market, detailing its regulatory frameworks, investment climate, and institutional infrastructure. He underscored the government’s ongoing reforms aimed at ensuring transparency, protecting investors, and achieving international compliance, all designed to position Cambodia as an attractive emerging market. Discussions also focused on Cambodia's initiatives to deepen its market by diversifying financial instruments and encouraging participation from both domestic and international players. BAMPL expressed significant interest in exploring investment and operational opportunities in Cambodia, aligning with their broader Asia-Pacific strategy to expand their presence and offer diversified market access to investors. H.E. Dr. Vin Pheakdey further emphasized the importance of regulatory compliance, robust risk management standards, and continuous investor education. He assured BAMPL of SERC's support in facilitating responsible market entry for reputable foreign institutions. The BAMPL team shared insights into their business model, regional experiences, and their vision for contributing to Cambodia's capital markets. Their proposed business plan, including fund management and distribution services, were reviewed in detail. H.E. Sou Socheat concluded the meeting by providing constructive feedback and outlining the key regulatory requirements for licensing and operational approval. He offered practical guidance on navigating the legal and procedural aspects of establishing a presence in Cambodia’s securities sector, reaffirming SERC’s openness to engaging with serious investors and partners who align with Cambodia’s financial development goals. This meeting underscored Cambodia’s proactive efforts to foster a dynamic, inclusive, and internationally connected capital market, signaling its readiness for greater integration into the broader Asia-Pacific financial ecosystem. This paves the way for increased foreign investment, product innovation, and accelerated long-term economic growth beneficial to both local and global investors.
ទស្សនៈទីផ្សារ
2026 October Market Outlook: Asia Markets – AI Valuation Concerns and Rising Geopolitical Risks
The direction of US monetary policy remains a key source of uncertainty. Minutes from the September Federal Open Market Committee (“FOMC”) meeting indicated that a further rate increase before year-end remains possible. However, Chair Warsh has declined to commit to a path, identifying the October and December meetings as the key decision points. Ahead of the next FOMC meeting on 27–28 October, the International Monetary Fund has cautioned that uncertainty over US monetary policy could keep Asian financial markets volatile. The recent sell-off has also brought the financing of AI investment into sharper focus. Chair Warsh noted that large technology companies raising funds in the bond market are adding to competition for capital. In our view, investors are likely to place greater scrutiny on the returns these companies generate from their AI spending. Developments in the Middle East remain a key swing factor for oil prices and inflation. Before the conflict began in late February, the Strait of Hormuz carried around one-fifth of global oil supply. Within Asia, the most significant development has been in Indonesia. On 15 October, index provider MSCI Inc. launched a consultation on reclassifying Indonesia from Emerging Market to Standalone Market status, citing insufficient progress on market transparency, concentrated shareholdings and weak enforcement. This contrasts with FTSE Russell, which reaffirmed Indonesia’s emerging market status. The Jakarta Composite Index fell 8.0% following the announcement, which triggered a trading halt. MSCI has also frozen certain index changes for Indonesian securities, including new additions, until further notice. The announcement adds to a difficult year for Indonesia, whose stock market has fallen more than 30% to become the world’s worst performing this year, according to Bloomberg, while Moody’s and Fitch have both revised the sovereign rating outlook to negative. With the consultation open until 30 April 2027, analysts expect foreign outflows to continue. In North Asia, the October sell-off highlighted how exposed South Korea and Taiwan have become to swings in AI sentiment after very strong gains over the past year. The KOSPI and TAIEX rose 86.7% and 80.6% respectively over the past year, and the TAIEX’s price-to-earnings ratio has expanded to 27.9 times from 23.1 times. Singapore again demonstrated its defensive qualities, with the Straits Times Index declining only 0.5% on 15 October, a far smaller fall than its North Asian peers. Overall, investor sentiment has shifted from chasing AI momentum towards greater caution on valuations, funding costs, and geopolitical risk. In this environment, we remain focused on businesses with strong balance sheets, sustainable earnings and pricing power, which we believe are better positioned to navigate persistent inflation and energy price shocks. We continue to apply a disciplined, bottom-up approach to stock selection and to maintain diversification across geographies and themes.
2026 September Market Outlook: Navigating Market Divergence
The Fed maintained a restrictive, data-dependent stance through August and subsequently raised the federal funds target range by 25 basis points to 3.75-4.00% citing persistent inflationary pressures. Updated projections point to the possibility of one further increase in 2026. Elevated long-dated US Treasury yields continue to present a valuation risk particularly for growth, technology and AI-related companies, whose expected cash flows lie further in the future. At the same time, continued corporate earnings delivery and investments in strategic technologies along the tech supply chain have so far helped the global economy absorb tighter financial conditions. Strong earnings guidance from major global technology companies supports the view that investment in data centres, advanced chips and supporting infrastructure remains resilient. Within Asia, performance has diverged meaningfully across countries. Singapore remains the region’s defensible market, with strong banking profitability and wealth management inflows attracting investor interest amid global uncertainty. Taiwan and South Korea’s technology sector continues to be major beneficiaries of surging AI-related demand. On the other hand, confidence towards China’s and Indonesia’s growth outlook remains fragile. China’s slow economic momentum is a result of a weak property market and slow domestic consumption, while Indonesia’s commodity price normalisation and concerns over capital outflows weigh on sentiment. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macroeconomic uncertainty.
2026 August Market Outlook: Navigating Volatility
Concerns around the durability of AI-related capital expenditure and intensifying competition triggered a sharp sector sell-off after a mid-July peak. Investor sentiment turned more discerning on the back of earnings season, and questions arose regarding how sustainable the AI investment pace is without eating into cash generation. Capital rotated out of semiconductors and into energy, financials and value stocks, shifting to markets and names seen as less exposed to a single-theme correction. Layered on top was renewed Middle East escalation and its effect on rates expectations. Brent crude spiked back above $100/barrel intermittently after the US reinstated a naval blockade on Iran and announced plans to impose a levy on cargo transiting Hormuz, although the levy was never implemented. This revived inflation concerns and caused markets to price a reduced likelihood of further Fed easing. Elevated US bond yields further weighed on stocks. Looking ahead, renewed conflict or another AI-related pullback could swiftly unwind recent sentiment gains and force a repricing of both rates and earnings expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.
2026 July Market Outlook: Navigating Crosscurrents
Central banks broadly maintained a data-dependent stance through the period and remained watchful even as global energy-driven inflation eased. The Federal Reserve reaffirmed its commitment to price stability even as growth prospects softened, while the European Central Bank similarly balanced improving headline inflation against still-elevated services prices. Closer to home, the Monetary Authority of Singapore raised its 2026 core inflation forecast on concerns that persistent price pressures could dampen household spending. The Hormuz disruption has driven inflation fears that outweigh traditional safe-haven demand. Gold and silver have moved in an unusual, counterintuitive pattern, falling rather than rallying as fighting escalated. In equities, investor sentiment shifted markedly as the AI-led rally that dominated the first half of the year gave way to a bout of volatility, prompting some rotation into value and cyclicals. Asian equities showed sharp dispersion rather than uniform resilience. In July 2026, Hong Kong’s Hang Seng emerged as the standout performer on continued strength in Chinese technology and AI names, while South Korea’s Kospi and Japan’s Nikkei slipped from June’s rebound as the memory-chip optimism and AI trade cooled. Looking ahead, markets remain caught between two competing narratives, a genuine easing of geopolitical and energy-driven inflation pressure, against the risk of renewed hostilities or a resurgence in AI-related volatility, which could quickly reverse recent gains in sentiment and reprice rate expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.
2026 June Market Outlook: From AI-Led Momentum to Persistent Uncertainty—A Disciplined Path Forward
Stronger than expected inflation in the US led newly installed Fed Chair Kevin Warsh to reinforce expectations that any rate cut is more likely in late 2026 or into 2027. Despite this hawkish view, US equities pushed to fresh highs, led by technology stocks. This period also saw Space Exploration Technologies Corp.’s (“SpaceX”) record-setting initial public offering, becoming a focal point for risk appetite and growth sentiment, which further amplified market enthusiasm. In the near term, the success of the SpaceX listing is likely to add further liquidity into space, artificial intelligence (“AI”) infrastructure and adjacent sectors. Investor sentiment remains heavily concentrated in AI-related and technology names, and some investors view the Asian market as a way to increase exposure at more attractive valuations than US technology leaders. Strong momentum in Asia is led by Korea, Taiwan and Japan, which play a central role in the AI and memory chip supply chain. On the other hand, China continues to lag even with incremental policy support. In other key markets, UK equities underperformed their peers, and Eurozone technology stocks performed moderately amid weak macroeconomic data, where the pullback in oil prices eased some inflationary pressure. Markets remain highly sensitive to developments in the Strait of Hormuz, where disruptions and the current partial normalisation of shipping through the strait weigh on energy prices and inflation expectations. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macroeconomic uncertainty.
2026 May Market Outlook: From Record Highs to Rising Uncertainty—A Selective Path Forward
Major indices have reached new highs since the March dip. Strong corporate earnings have reinforced investor confidence and sustained the ongoing risk-on rotation into AI-related stocks. The technology sector now represents a larger share on the MSCI Emerging Markets Index than the S&P 500, underscoring the central role of Taiwan and South Korea in the AI supply chain. With inflation still elevated and growth looking uneven across regions, central banks are balancing financial stability and energy-driven price pressures. Expectations for rate cuts have been pushed out or replaced by further tightening of monetary policy. The new Federal Reserve Chair, Kevin Warsh, known to favour rate cuts, faces inflationary pressures in the US economy that work against the dovish narrative, making rate cuts unlikely. Other central banks, such as the Bank of Japan and the European Central Bank have kept its policy unchanged, but with upward revisions to inflation forecasts, investors expect rate hikes this year. Though markets have appeared resilient to geopolitical shocks, the continuation of the Strait of Hormuz blockage can dampen economic activity through supply chain disruption and entrenching inflationary pressures. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macro uncertainty.