

វិចារណកថា
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
បន្ទប់ព័ត៌មាន
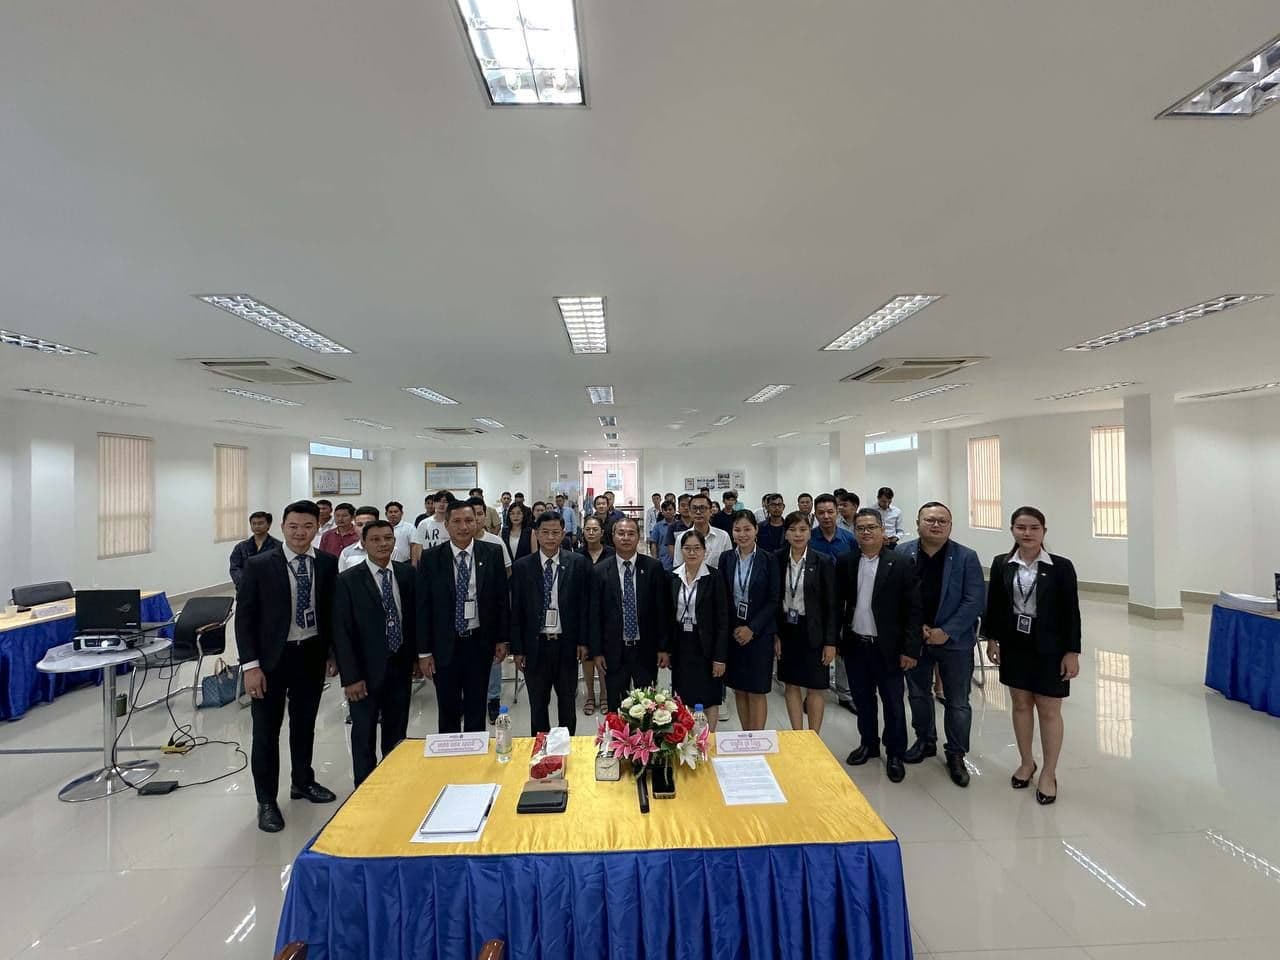
Roadshow Reflections: Insights and Innovations Unveiled
On the morning of December 7, 2024, Banjaran Asset Management (Cambodia) Plc. partnered with ACLEDA Bank Plc., Chamkar Doung Branch, to host the landmark event titled "Cambodia’s First Fund Subscription Roadshow." This pioneering initiative aimed to introduce local investors to the "BAMC Asia Equity Fund (BAEF)," showcasing its potential as a catalyst for capital growth and economic development in Cambodia. The roadshow featured an engaging presentation that outlined the strategic objectives of the "BAMC Asia Equity Fund", emphasizing its focus on high-growth sectors within the region. Attendees were given insights into the fund's investment philosophy, risk management strategies, and expected returns, all tailored to the unique opportunities present in the Cambodian market. Throughout the event, participants had the chance to engage in meaningful discussions with industry experts and gain firsthand knowledge about emerging trends and investment strategies. The roadshow not only highlighted the fund's potential to drive significant economic growth but also reinforced the importance of collaboration between financial institutions and asset management firms in fostering a robust investment landscape in Cambodia. In conclusion, the event served as a pivotal moment for local investors, providing them with valuable resources and insights to navigate the evolving financial market, while highlighting the BAMC Asia Equity Fund's crucial role in driving Cambodia's economic growth, signaling that this is just the beginning, with more exciting opportunities to come.
Cambodia's First Fund Subscription Roadshow
On morning, 23rd November 2024, Banjaran Asset Management (Cambodia) PLC. has participated in "Cambodia's First Fund Subscription Roadshow" hosted by Acleda Securities Plc. Through engaging presentations and topic about BAMC Asia Equity Fund (BAEF), we were able to connect and promote the CIS fund to a wide range of participants, marking another significant milestone in Cambodia’s financial market growth.A heartfelt thank you to the organizers and attendees for making this event a success.
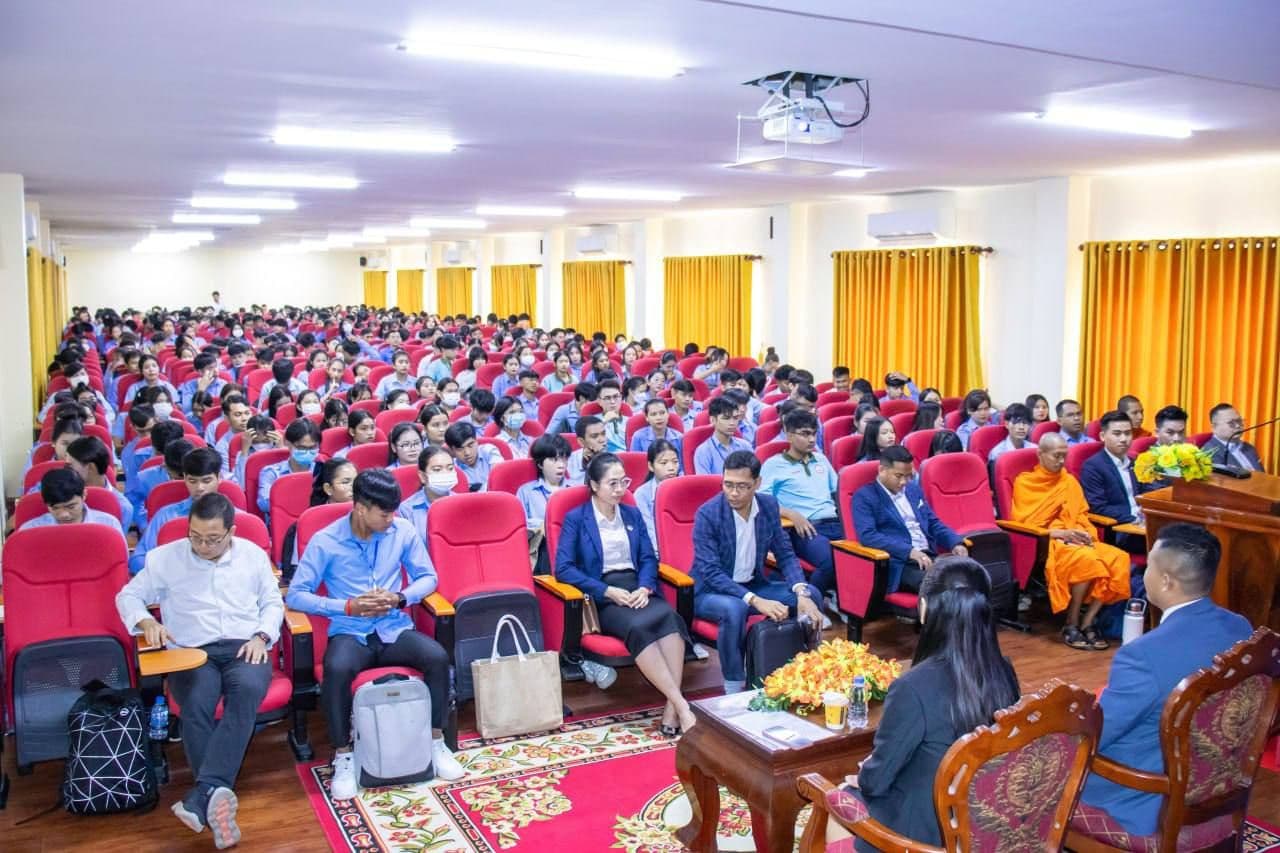
Empowering Future Investors: Banjaran Asset Management's Insightful Collective Investment Scheme (CIS) Fund
On the morning of October 30, 2024, Mr. Sok Chantola, Sales & Marketing Executive of Banjaran Asset Management (Cambodia) Plc., conducted a presentation on the Collective Investment Scheme (CIS) Fund at Preah Sihanouk Raja Buddhist University as part of the “Smart Investing” training program, organized by ACLEDA Securities Plc. The session aimed to deepen attendees’ understanding of CIS investment strategies.
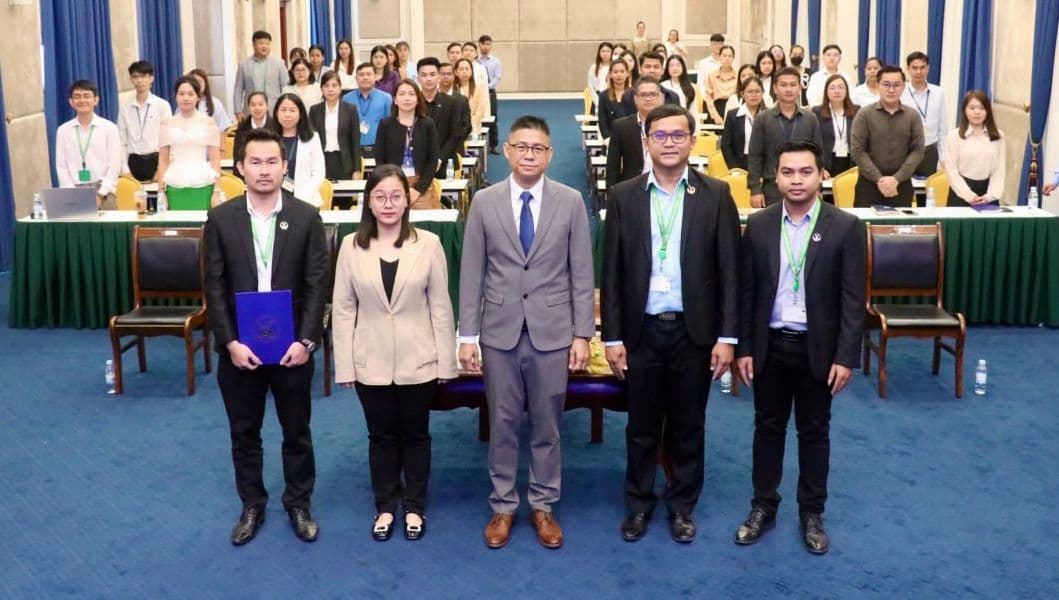
Seminar on Professional Ethics in Collective Investment Schemes with SERC
On the morning of Wednesday, corresponding to October 23rd 2024, the Securities and Exchange Regulator of Cambodia (SERC) organized a seminar to promote “Professional Ethics in Collective Investment Schemes” . This seminar was held for fund management companies, custodians, distributors, and trustees, at the building of the Non-Bank Financial Services Authority. The event was presided over by His Excellency Dr. Vin Pakdey , Deputy Director-General of SERC, representing His Excellency Sou Socheat , the Government Delegate in charge as Director-General of SERC. The seminar was designed to provide an opportunity for fund management companies and related businesses to understand the importance of professional ethics, transparency, and responsibility in the collective investment scheme business. It also aimed to ensure that these entities adhere to high standards in their operations, enhancing investor confidence in the financial market. The gathering covered important topics on how ethical practices contribute to sustainable business growth and regulatory compliance, reinforcing the importance of good governance in the financial sector. More Securities and Exchange Regulator of Cambodia
Explore Joint Investment Fund Opportunities
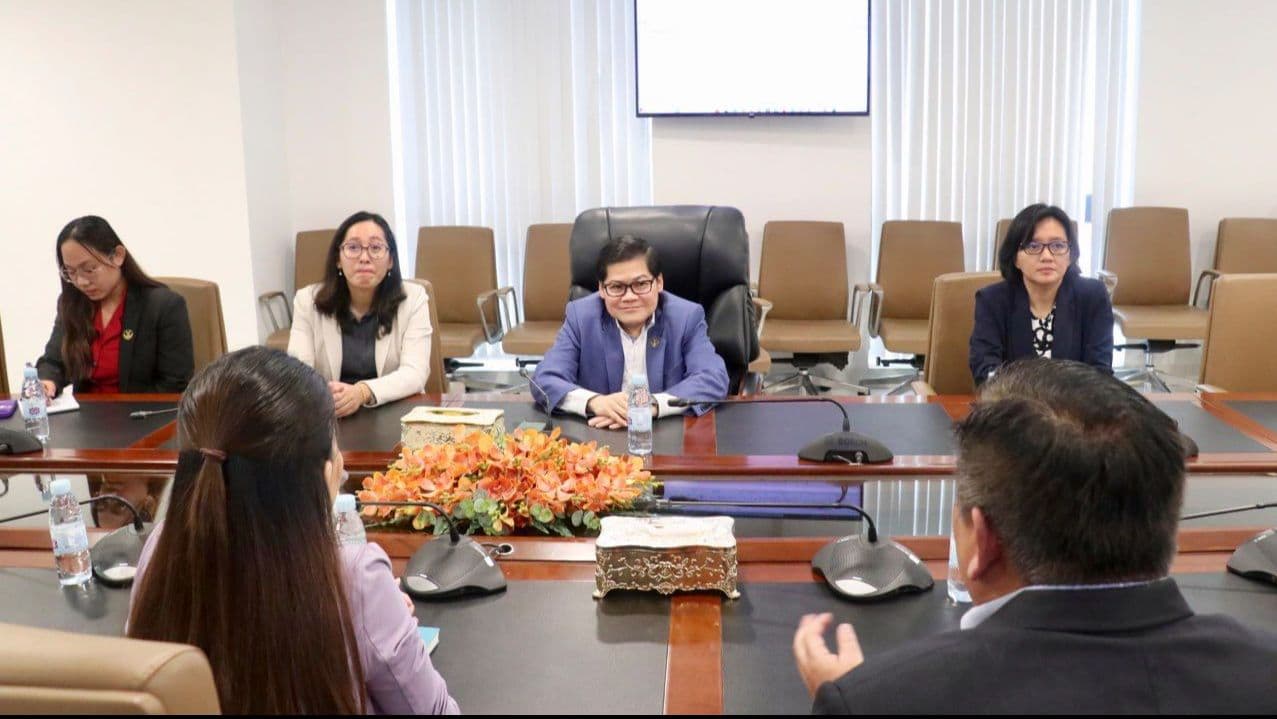
His Excellency Sou Socheat, the Delegate of the Royal Government and Director General of the Securities and Exchange Regulator of Cambodia (SERC), led a delegation to meet with representatives of Banjaran Asset Management (Cambodia) Plc. On the morning of Friday, October 11, 2024, His Excellency Sou Socheat, along with his colleagues, held discussions with representatives of Banjaran Asset Management (Cambodia) Plc regarding joint investment fund projects. The meeting proceeded smoothly with high-level cooperation. More Securities and Exchange Regulator of Cambodia
Roadshow: Cambodia's First CIS Fund Subscription 2024
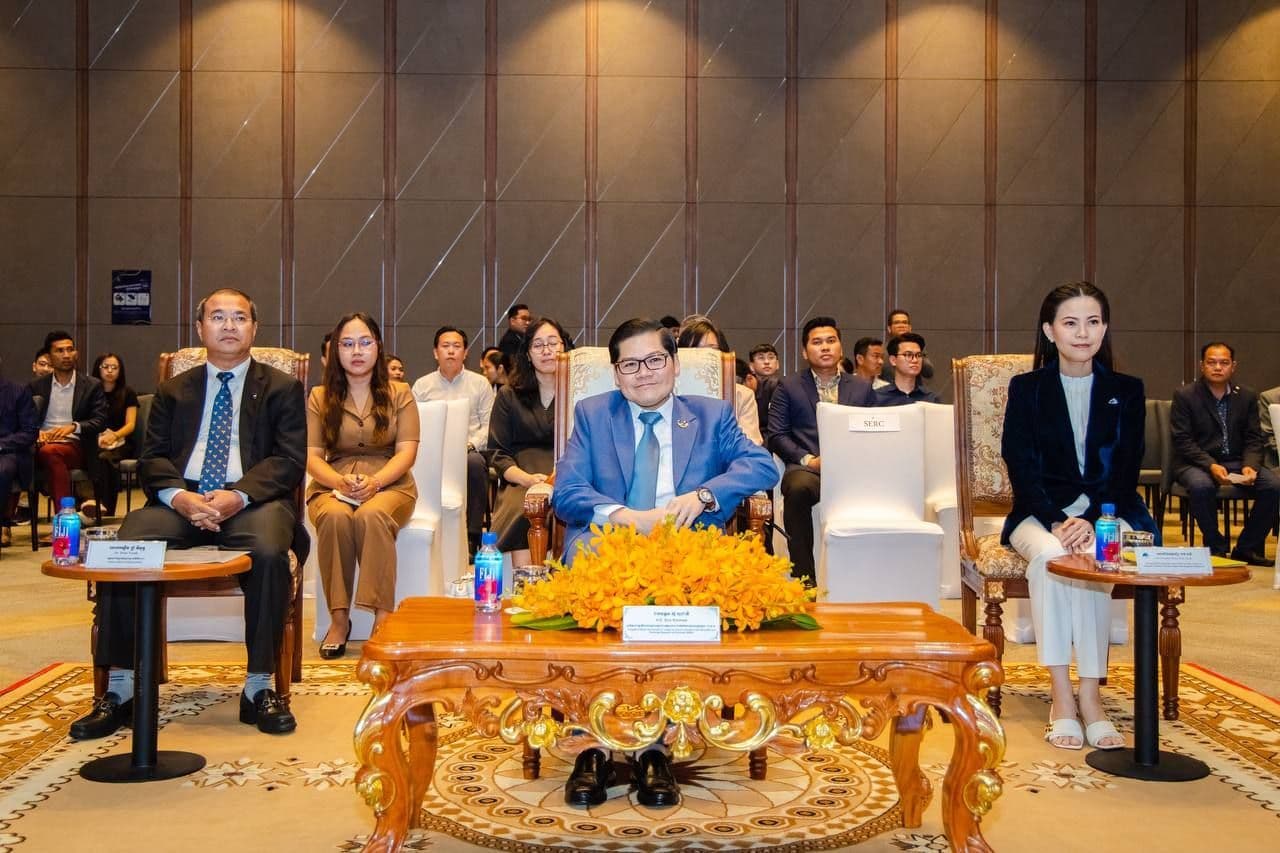
On the morning of 10th October 2024, Banjaran Asset Management (Cambodia) PLC. (BAMC) proudly hosted the First Roadshow for Cambodia’s CIS Fund Subscription 2024, in collaboration with our esteemed partner ACLEDA Securities PLC. The event was honored by the presence of H.E. Sou Socheat , Delegate of the Royal Government in charge as Director General of the Securities and Exchange Regulator of Cambodia (SERC), who graced the occasion with his high presidency. This landmark event marks a pivotal moment in the development of Cambodia’s financial sector, where we officially introduced the BAMC Asia Equity Fund (BAEF) to the public. Through insightful presentations and dynamic discussions, we promoted the potential of the CIS fund to a diverse audience, including institutional investors, industry professionals, and individuals eager to explore new investment opportunities. The roadshow provided participants with a deep dive into the benefits and unique features of the CIS fund, showcasing how it paves the way for broader participation in Cambodia’s growing capital market. It also highlighted our commitment to delivering innovative financial products that cater to the needs of both local and international investors. This event not only signified a significant milestone for Banjaran Asset Management, but also underscored the rapid expansion of Cambodia’s financial markets and the increasing role of the CIS fund in driving economic growth and investment opportunities in the region. We are incredibly grateful for the support and participation of all attendees, and we look forward to continuing our mission to make financial investments accessible to all while contributing to the future growth of Cambodia's economy.
ទិវាអ្នកចម្បាំងផែនដី ឆ្នាំ២០២៤:កម្ពុជាស្អាត អនាគតស្អាត
ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក មានមោទនភាពដែលបានចូលរួមយ៉ាងសកម្មក្នុង “ទិវាអ្នកចម្បាំងផែនដី២០២៤”។ ក្រុមការងាររបស់យើងខ្ញុំបានចូលរួមចំណែកក្នុងការកសាងបរិស្ថានមួយដ៏មានផាសុកភាពនិងស្ថិរភាពអនាម័យ។ ចូលរួមទាំងអស់គ្នា ដើម្បីបន្តសកម្មភាពដ៏ប្រពៃនេះ ក្នុងការរក្សាបានបរិស្ថានមួយដ៏ល្អឥតខ្ចោះសម្រាប់យុវជនជំនាន់ក្រោយ។
BAMC Asia Equity Fund – Cambodia’s First Fund – Fund Distributor Launch Event
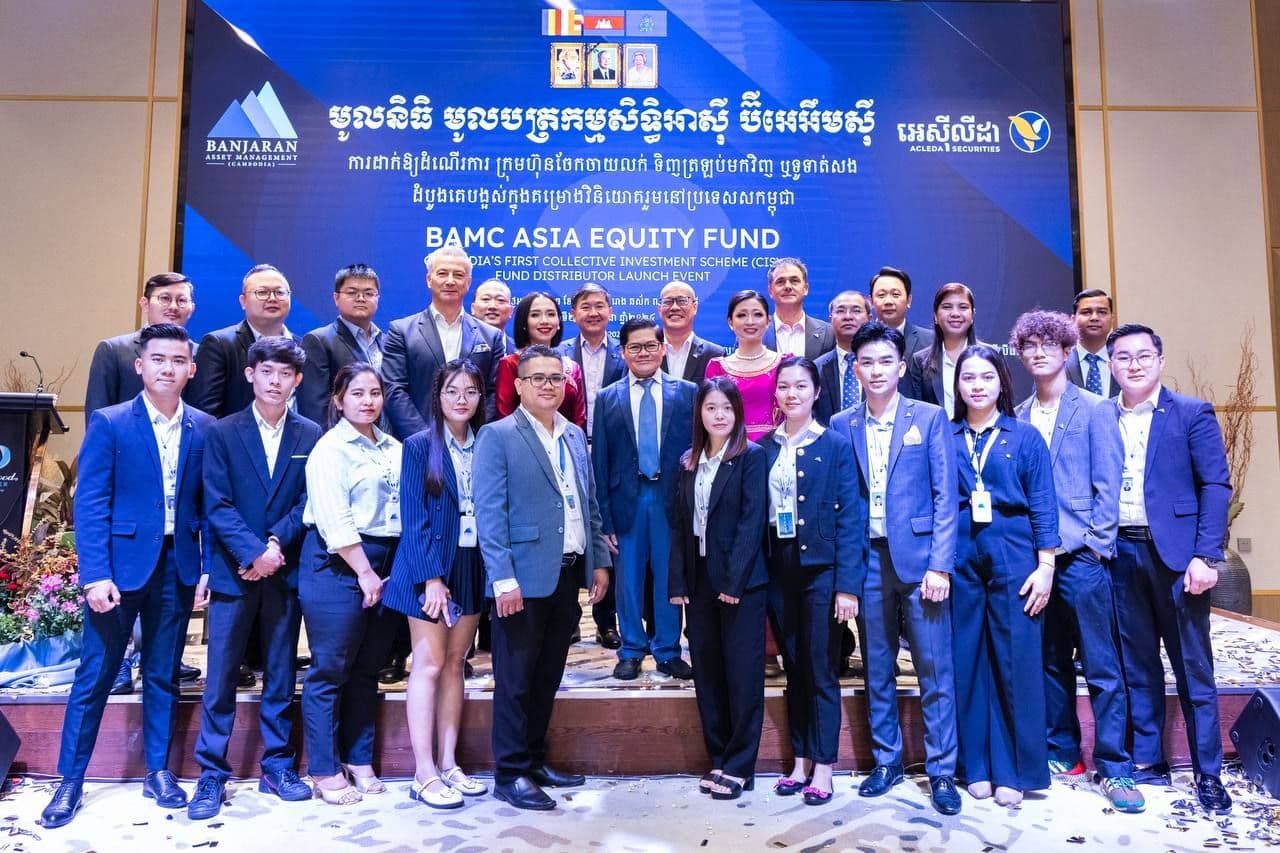
On 23 July 2024, Banjaran Asset Management (Cambodia) PLC. successfully hosted the “BAMC Asia Equity Fund – Cambodia’s First Fund – Fund Distributor Launch Event.” The event marked a significant milestone with the official signing of the Fund Distribution Agreement between Banjaran Asset Management (Cambodia) PLC. and ACLEDA Securities PLC. The ceremony was held under the high presidency of H.E. Sou Socheat , Delegate of the Royal Government in charge as Director General of the Securities and Exchange Regulator of Cambodia (SERC), who was accompanied by associates from the SERC. The launch brought together distinguished guests, regulatory representatives, and valued partners, reflecting strong collaboration and support for the growth of Cambodia’s capital market. This milestone not only represents the introduction of the First Collective Investment Fund in Cambodia but also highlights the commitment of Banjaran AMC and its partners to creating accessible investment opportunities and strengthening the financial sector in this emerging market.
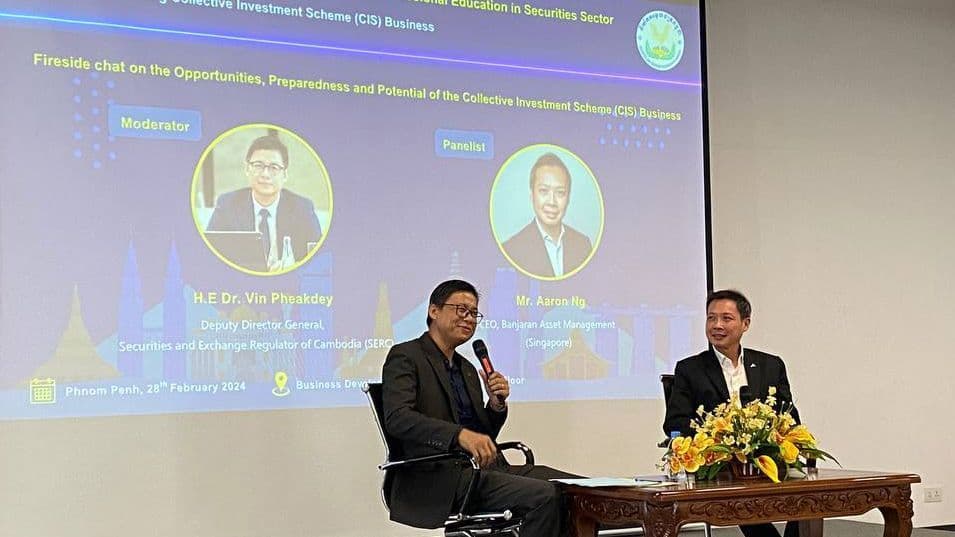
Unlocking Investment Opportunities: Banjaran Asset Management Explores CIS Potential in Cambodia
Phnom Penh, Cambodia – Mr. Aaron NG, CEO of Banjaran Asset Management (Singapore), participated in a lively discussion on the “Fireside Chat on The Opportunities, Preparedness, and Potential of the Collective Investment Scheme (CIS) Business.” The event, moderated by H.E Dr. Vin Pheakdey, Deputy Director General of the Securities and Exchange Regulator of Cambodia (SERC), delved into the evolving landscape of CIS in Cambodia. Mr. NG shared insights on how the CIS business can unlock new opportunities for local and international investors while addressing the preparedness of market participants. The discussion highlighted the potential of CIS to strengthen Cambodia's financial services sector and increase access to investment opportunities across the region.
ទស្សនៈទីផ្សារ
2024 April, Market Outlook: Navigating Volatility Amidst Inflation, Interest Rates, and Geopolitical Risks
Recently, both the bond and stock markets have experienced heightened volatility, driven by inflation and retail sales in the US consistently exceeding expectations. In response, the Federal Reserve once again opted to hold off on lowering interest rates, waiting for more comprehensive data before making further policy decisions. This cautious approach led investors to adjust their interest rate forecasts aggressively, which directly impacted equity markets. We believe these concerns are justified, especially as commodity prices have surged, potentially contributing to higher inflation in the months ahead. At present, we assess that the recent equity price movements may be a short-term reaction to rising bond yields, and we will continue to monitor these trends closely. In China, the government's initiative to support "whitelist" property projects has made significant progress, with funds raised reaching RMB 469 billion by the end of March—more than double the RMB 200 billion previously reported. Given the size of China’s residential property sector, we anticipate further substantial disbursements. Additionally, there is an expectation that the People’s Bank of China will gradually increase government bond trading through its open market operations, signaling a form of monetary policy easing. These developments, along with China's Q1 GDP growth and improved PMI numbers, offer positive signals for the economy. However, we recognize initial signs of a slowdown in key economic indicators, such as retail sales and industrial production, reflecting lingering sluggishness in the domestic economy. We will continue to track these factors in the coming months. On the geopolitical front, tensions between Iran and Israel are escalating, with Israel considering its response to recent drone strikes by Iran. This situation could significantly impact crude oil prices, introducing further inflationary risks in the near term. Meanwhile, the ongoing US-China tensions remain a long-term issue. Recently, US lawmakers introduced a bill that would bar mutual funds from investing in indices that include Chinese stocks. This follows a broader trend of global portfolio allocations shifting away from China over the past year. As a result, we have observed a substantial valuation premium in the US market relative to China, far exceeding historical norms. We believe that once the Chinese economy stabilizes and returns to sustainable growth, this valuation gap may narrow. In the near term, inflationary risks in the US and uncertainty in China could present challenges for equity markets. However, our analysis of current data suggests that this may be a temporary correction, largely driven by high valuations in developed markets. We remain focused on identifying attractive opportunities as they emerge in the evolving market landscape.
2024 March, Market Outlook: Navigating Elevated Interest Rates, China’s Economic Measures, and Corporate Earnings
Throughout the month, the Federal Reserve reinforced its stance that there is no urgency to lower interest rates during the first half of 2024. Notably, the Fed addressed growing concerns within the commercial real estate sector, acknowledging that while the situation remains manageable for now, it may lead to further banking failures. This dovetails with our cautious outlook on the potential consequences of keeping interest rates elevated for too long, especially if policy missteps occur. High rates for an extended period could stress certain sectors, particularly real estate, heightening risks within financial markets. In China, the government has begun to take action to support previously announced “whitelist” property projects. Major commercial banks have approved over RMB 200 billion in loans to facilitate the completion of these projects. While this is a positive step, further financing will likely be necessary to ensure sufficient liquidity for the real estate sector's recovery. We will continue to monitor further policy announcements and their impact on property sales and prices in the coming months. The recently concluded "Two Sessions" meeting of the Chinese Communist Party revealed economic targets similar to those set last year. The 5.0% GDP growth target for 2024 appears ambitious, especially in light of the modest 3.0% deficit target and the conservative spending habits of Chinese consumers. However, we believe this growth target is achievable, given the gradual shift in consumer behavior towards increased spending. Furthermore, growth outside of the real estate sector remains robust, offering a positive outlook for broader economic recovery. In the corporate world, recent earnings reports from leading companies have generally shown strong growth for Q4 2023, with some projecting modest top-line expansion in 2024. However, US stocks that missed earnings expectations and guidance experienced sharp declines, a consequence of their elevated valuations. Given the uncertain economic outlook, we will closely monitor both economic and industry-specific data to inform our next portfolio decisions. Despite these short-term uncertainties, we remain positive about the long-term potential of our holdings. In conclusion, as central banks maintain a cautious stance on interest rates and China accelerates its economic support, global markets face a delicate balancing act in 2024. Careful navigation through these challenges will be key for investors seeking sustainable growth opportunities.
2024 February, Market Outlook: Navigating Central Bank Strategies and Growth Opportunities in Asia
As we step into 2024, initial hopes for early interest rate cuts by the US Federal Reserve (FED) and the European Central Bank (ECB) are fading. Both central banks have downplayed the likelihood of reducing rates anytime soon, largely due to strong economic data released in recent months. The US economy continues to display resilience, with sustained expansion indicating that the FED must tread carefully. Lowering interest rates too soon could risk reigniting inflation, which the central bank is keen to avoid. At the same time, there are pockets of weakening growth within the economy, signaling the potential for a broader slowdown. This delicate balancing act places the FED in a challenging position, where policy mistakes could have significant consequences for both the US economy and global financial markets. In line with our earlier expectations, the Eurozone also faces similar inflationary pressures, with energy prices remaining persistently high. As a result, inflation remains sticky, preventing the ECB from easing rates. We foresee that both central banks will need to remain vigilant in navigating the complex dynamics of their respective economies, weighing inflation risks against the threat of economic slowdowns. Meanwhile, China's approach to monetary policy has taken a markedly different turn. The Chinese government recently lowered the 5-year loan prime rate by 25 basis points to 3.95%, signaling its determination to stimulate the economy and support the real estate sector. Under the “whitelist” initiative, commercial banks are encouraged to provide lending to property projects approved by local governments. These rapid, proactive measures underscore the government's commitment to front-loading stimulus to prevent weak sentiment in the housing market from deepening. We believe these policies will continue to evolve progressively, ensuring that the real estate sector stabilizes and recovers on a sustainable path. Signs of improvement are already emerging in China’s economy. Recent data on monetary aggregates indicate positive movement, and domestic travel and spending during the Lunar New Year suggest a rebound in consumer activity. On the global stage, China’s exports have grown for the second consecutive month in December 2023, further reinforcing the positive outlook for 2024. These rapid policy moves come as the State Council calls for "forceful measures" to restore confidence in both the economy and financial markets. Japan is also showing signs of strength, with the economy benefiting from long-anticipated corporate reforms. After decades of deflation, Japan appears to be breaking free from this prolonged economic phase. Reforms aimed at improving corporate profit margins and shareholder returns are finally coming to fruition, marking the end of the country's 30-year deflationary struggle. We believe these developments will unlock significant value for shareholders, creating opportunities for growth in the Japanese market. In summary, we remain optimistic about the prospects for the Asian markets, particularly as China and Japan implement aggressive economic measures. Conversely, we approach the US markets with caution, given the headwinds presented by inflationary pressures and an overconcentration in the technology sector. As we move forward, the balancing act between growth, inflation, and central bank policy will continue to shape the global market landscape, with Asia emerging as a bright spot for investors in 2024.
2024 January, Market Outlook - Navigating 2024 Amid Geopolitical Tensions and Economic Shifts
As we enter 2024, the global financial landscape is expected to shift focus from rising bond yields to interest rate stabilization and potential easing, particularly by the US Federal Reserve. After three years of tightening policies, we anticipate that both the US and Europe will experience sharply slower economic activity and increased unemployment. Europe, in particular, faces heightened risks of a prolonged recession. While interest rates in the US may hold steady for now, primarily due to persistent inflation pressures in areas like housing, rising geopolitical risks, such as recent airstrikes by the US and UK in response to Houthi rebel attacks, could lead to disruptions in global trade and shipping costs. Geopolitical Tensions: The US-China Factor Geopolitical developments, especially the enduring US-China tension, will be a critical driver in assessing global economic and financial market performances. The ongoing decoupling between the two economic giants, particularly in the semiconductor industry, presents both challenges and investment opportunities. We foresee increased innovation stemming from this geopolitical divide, providing promising prospects in certain sectors. The AI Revolution: A Long-Term Investment Opportunity The advent of generative artificial intelligence (AI), epitomized by innovations like ChatGPT, has sparked widespread interest in AI-driven technologies across industries. While the global addressable market for AI is still being estimated, we remain optimistic about its long-term growth potential. AI companies in our portfolio have already shown promise, and we continue to explore new investment opportunities in this space as AI applications expand. China's Economic Recovery: Stabilization Efforts China's economic recovery is gaining momentum, though the real estate sector remains a drag. However, recent fiscal and monetary policies have helped stabilize the situation. The Central Economic Work Conference's call for proactive fiscal expansion and real estate policy adjustments are positive signs for the market. China's central bank has also introduced liquidity-boosting measures, such as a 50 basis point reduction in the reserve requirement ratio and lower rates for loans to small firms. We believe these are incremental steps toward further stabilization, and we are optimistic about China's economic and market outlook in 2024. US Presidential Election: Market Implications This year’s US Presidential Election will undoubtedly shape economic policies and market directions, though we refrain from speculating on political outcomes. Instead, our focus remains on the data-driven economic and market trends, with a view that the US economy will increasingly look inward as the election approaches. Overall, we believe Asia, particularly China, remains a bright spot in the global economy, while the US and Europe may face slower growth and recessionary pressures. We remain vigilant in assessing geopolitical risks and continue to focus on sectors like AI and innovation, which offer long-term growth opportunities.
2023 December, Market Outlook: Asia Emerges as a Bright Spot Amid Global Economic Shifts
As 2023 draws to a close, the equity market has remained largely stable, with investors maintaining a preference for developed markets. While Asia Pacific markets have also posted positive returns, their performance still trails behind other regions despite notable improvements in economic data. This disparity is likely due to end-of-year dynamics such as tax-loss harvesting and institutional portfolio adjustments, or "window dressing," a common phenomenon seen during this period. Historically, such short-term volatility tends to carry over into January as fund managers rebalance their portfolios for year-end reporting. In developed markets, equity markets have experienced significant optimism since the Federal Reserve opted to hold interest rates steady for two consecutive meetings. This move has signaled to investors that the Fed's interest rate hike cycle may have peaked, fueling market euphoria. Additionally, concerns about a looming US recession have eased, with many economists now revising their forecasts toward a "soft landing" scenario, where economic activity slows but avoids a severe downturn. However, inflation in the US remains persistently above the Fed's 2% target, indicating that interest rates may stay elevated for an extended period. The future economic outlook remains uncertain, especially as housing inflation cools, but we believe that while the risk of a recession is still moderately high, it is unlikely to escalate into a systemic crisis. On the geopolitical front, China’s recent diplomatic overtures toward the US have been a positive development. Following Chinese President Xi Jinping's visit to the US last month, both nations have expressed a renewed commitment to peaceful cooperation. The resumption of military dialogue, after months of silence, signals China's intention to restore political ties with the US. Additionally, President Xi’s meeting with top US business leaders highlighted strong corporate support for continued engagement with China, despite ongoing geopolitical tensions. For instance, Mastercard's new joint venture with China's national transaction processor, NetsUnion Clearing, demonstrates the long-term business potential between the two countries, allowing Mastercard cardholders to enjoy seamless payments in China. Nevertheless, while these diplomatic efforts are encouraging, further reciprocal actions from the US government will be crucial to reducing geopolitical risks in the long term. With the US presidential elections on the horizon in late 2024, we expect China to remain a central theme in American political discourse, with both parties likely positioning the country as a major national security threat to garner electoral support. This political climate may perpetuate tensions, and as a result, we anticipate that geopolitical risks will remain elevated through 2024. Looking beyond the US, other significant elections, such as Taiwan's, will also play a key role in shaping geopolitical dynamics. As global security concerns intensify, we foresee a gradual restructuring of global supply chains, with capital and business operations increasingly shifting to countries deemed safer or more politically stable. This trend toward economic fragmentation will favor companies capable of maintaining market share and operational efficiency amid the reshoring of industries. In China, the recent Central Economic Work Conference concluded with the government setting a clear pro-growth agenda for 2024. Chinese policymakers are focusing on reviving confidence and stimulating economic growth through a series of supportive measures, including monetary, fiscal, and administrative interventions. These initiatives have been ramping up in intensity, and we anticipate additional measures in the coming months, particularly aimed at addressing risks in the real estate sector. Given these developments, we continue to see Asia, particularly China, as a bright spot for economic growth in the global economy. A lower interest rate environment, coupled with increased liquidity, should help alleviate financial pressures and reduce the debt burdens of companies and individuals. As the world economy navigates through geopolitical tensions and inflationary pressures, Asia remains well-positioned to drive global growth in the near term, making it a focal point for investors looking to capitalize on emerging market opportunities. In summary, while global economic conditions remain uncertain, Asia’s resilience, supported by pro-growth policies and improving economic indicators, offers a compelling investment case, even as geopolitical risks loom on the horizon.
2023 November, Market Outlook: Resilience, Stimulus, and Global Shifts
As we look ahead, the global market outlook remains shaped by several key developments. Despite geopolitical tensions and ongoing conflicts, such as the humanitarian crisis between Israel and Hamas, we expect limited broader economic impact due to stabilizing military presence and containment measures. The risk of a wider regional conflict appears low, preserving global market stability for the time being. US Economic Resilience and Slowdown Expectations In the US, resilience continues to be a dominant theme. While the Federal Reserve’s tightening measures have been in place since 2022, the financial system remains robust, supported by the aftereffects of COVID-19 stimulus and substantial fiscal spending by the US government. This liquidity, however, is expected to taper, with a corresponding economic slowdown projected over the medium term. Current forecasts suggest GDP growth of 0.7% in Q4 2023 and 0.3% in Q1 2024, indicating a likely deceleration in the coming quarters. China’s Recovery Gains Momentum China’s economy has begun to gain notable momentum, driven by improving retail sales, imports, and industrial output. The government has recently announced a significant RMB 1 trillion stimulus package to further bolster the recovery. However, investor sentiment remains cautious, keeping valuations suppressed relative to the US. We believe that this discrepancy is unsustainable and anticipate that over the medium term, valuations in China will close the gap, driven by stronger economic fundamentals. Japan’s Stimulus and Growth Prospects Japan is emerging as an intriguing opportunity as it moves away from years of deflation, with inflation now supported by demand. In response to weakening economic data, the Japanese government has introduced a US$ 110 billion stimulus package aimed at boosting private consumption. This should translate into economic growth in the near-to-medium term, further enhancing Japan’s market potential. Focus on Asia Amid Geopolitical Stability Asia remains our primary focus, especially in light of recent positive developments in China’s economic data and a decrease in US-China geopolitical tensions following the Biden-Xi meeting in San Francisco. Agreements between both countries signal a more stable relationship, reducing trade war fears and enhancing the region’s investment appeal. Overall, we maintain a cautiously optimistic view, focusing on opportunities in Asia while monitoring the evolving macroeconomic landscape.