

វិចារណកថា
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
បន្ទប់ព័ត៌មាន
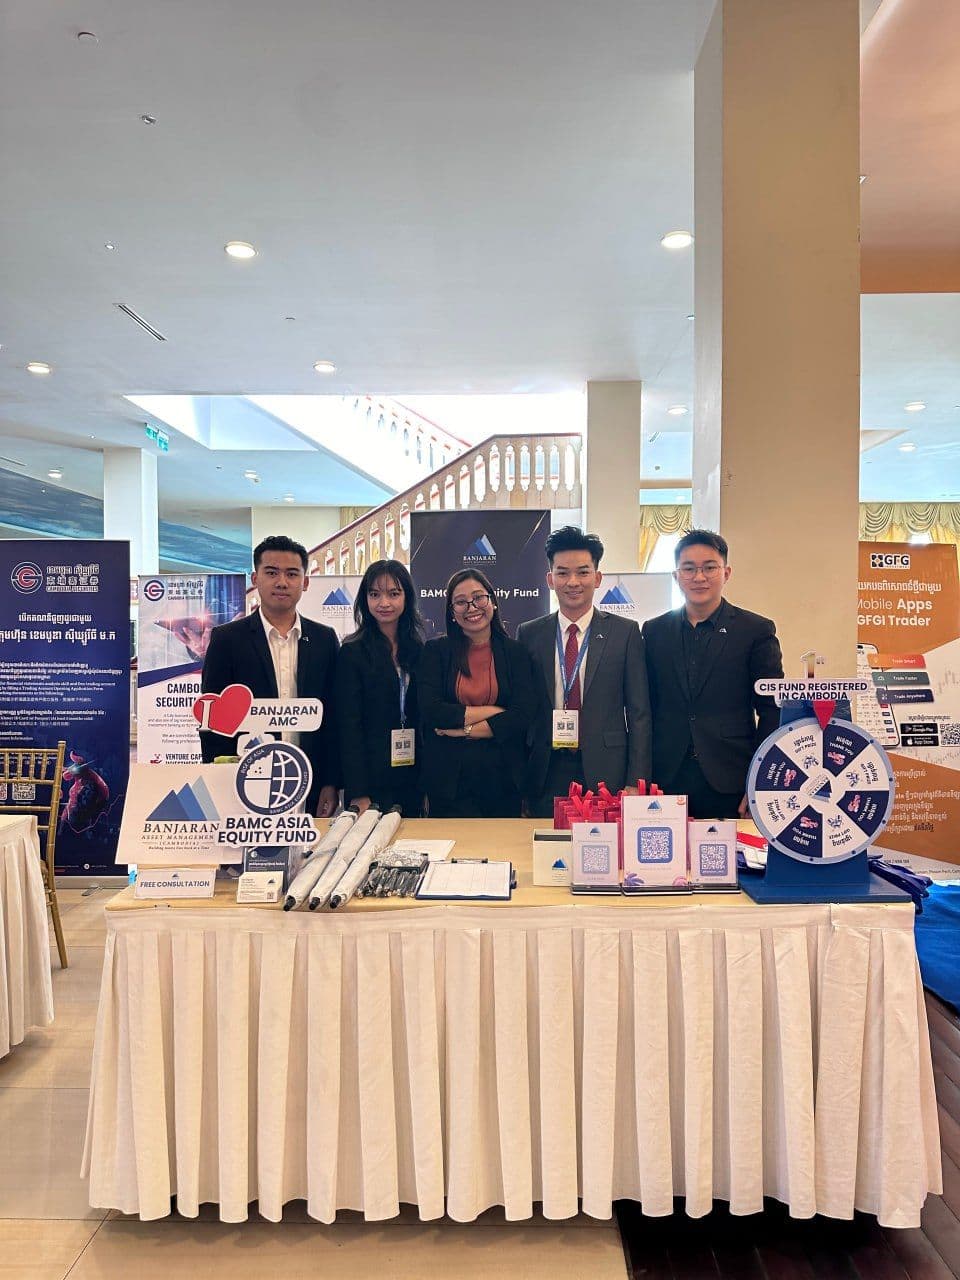
Banjaran AMC Joins the Annual Securities Conference 2025
Banjaran Asset Management (Cambodia) PLC. is honored to participate in the Annual Securities Conference 2025 held on October 7th! We were delighted to engage with participants who visited our booth throughout the event. The event was graced by the presence of H.E. Dr. AUN Pornmoniroth, Deputy Prime Minister, Minister of Economy and Finance, Chairman of the Non-Bank Financial Services Authority, and H.E. Sou Socheat, Delegate of the Royal Government in charge as Director-General of the Securities and Exchange Regulator of Cambodia (SERC).
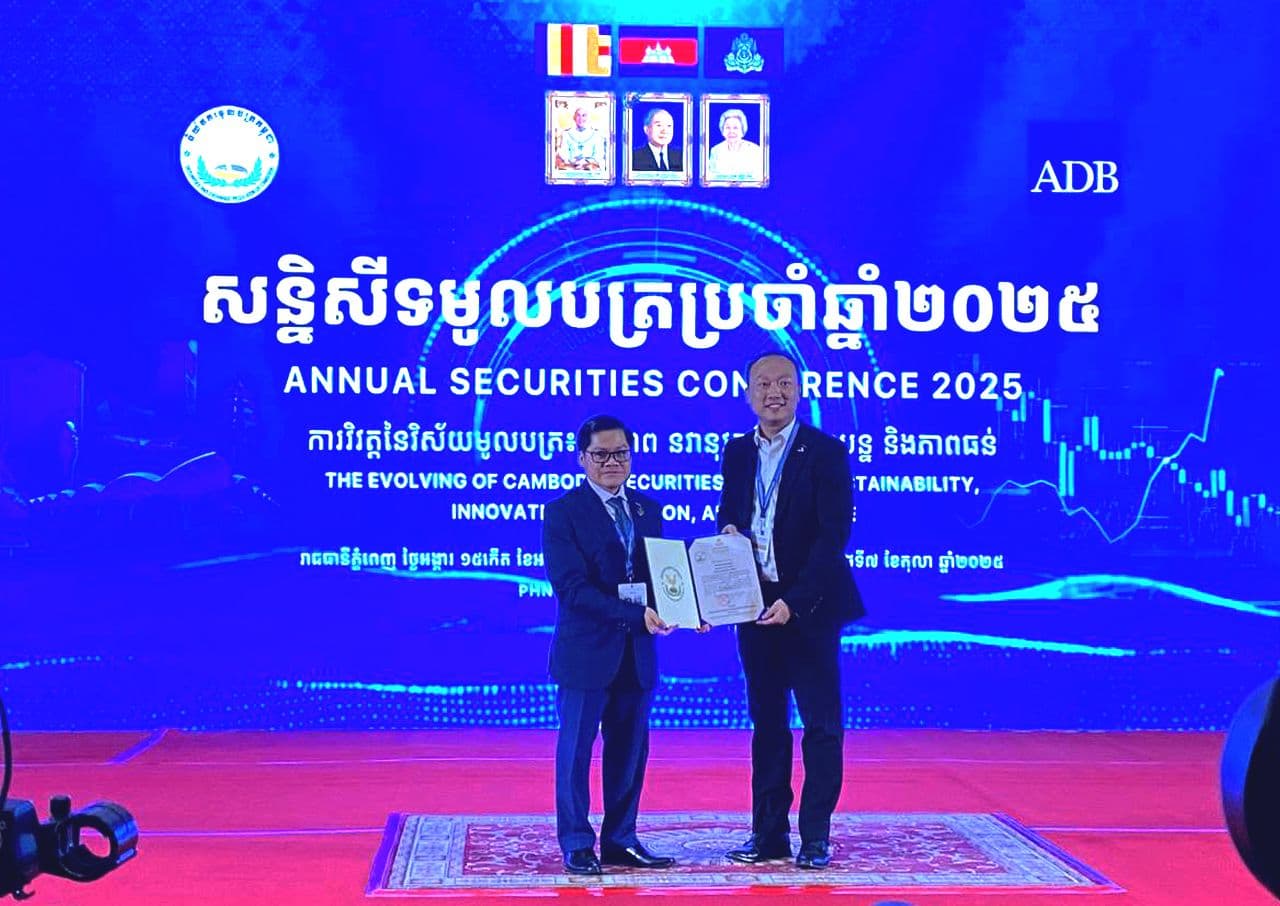
Banjaran Asset Management (Cambodia) Recognized for Its Contribution to Cambodia’s Financial Market
We’re truly honored to be one of the sponsors of the Annual Securities Conference 2025! Held on October 7th, 2025 in the Annual Securities Conference 2025 at Sokha Hotel, Mr. Eric Loo, CEO & Executive Director of Banjaran Asset Management (Cambodia) Plc. received a certificate of recognition from H.E. Sou Socheat, Delegate of the Royal Government in charge as Director General of SERC in this remarkable event—organized by the SERC, brought together leaders and professionals across Cambodia’s securities sector to discuss Sustainability, Innovation, Inclusion, and Resilience. Banjaran Asset Management (Cambodia) PLC. is proud to support the continued growth and innovation of Cambodia’s financial market!
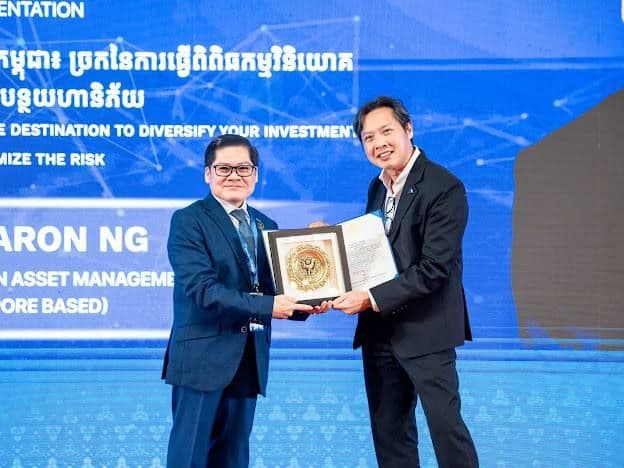
Mr. Aaron Ng Advocates Unit Trust Investment Strategies at the Annual Securities Conference 2025
Mr. Aaron Ng , CEO of Banjaran Asset Management Pte. Ltd. (Singapore), delivered an impactful presentation on “Investing in Unit Trust Funds in Cambodia: Diversity Your Investment And Minimize Your Risks” in the Annual Securities Conference 2025, organized by the Securities and Exchange Regulator of Cambodia (SERC), on October 7th, 2025, Sokha Hotel. Presided over by H.E. Dr. AUN Pornmoniroth , Deputy Prime Minister, Minister of Economy and Finance, and Chairman of the Non-Bank Financial Services Authority. Mr. Aaron session provided valuable perspectives on the growth potential of Cambodia’s capital market and the crucial role of unit trust funds in minimizing risks and diversifying investments
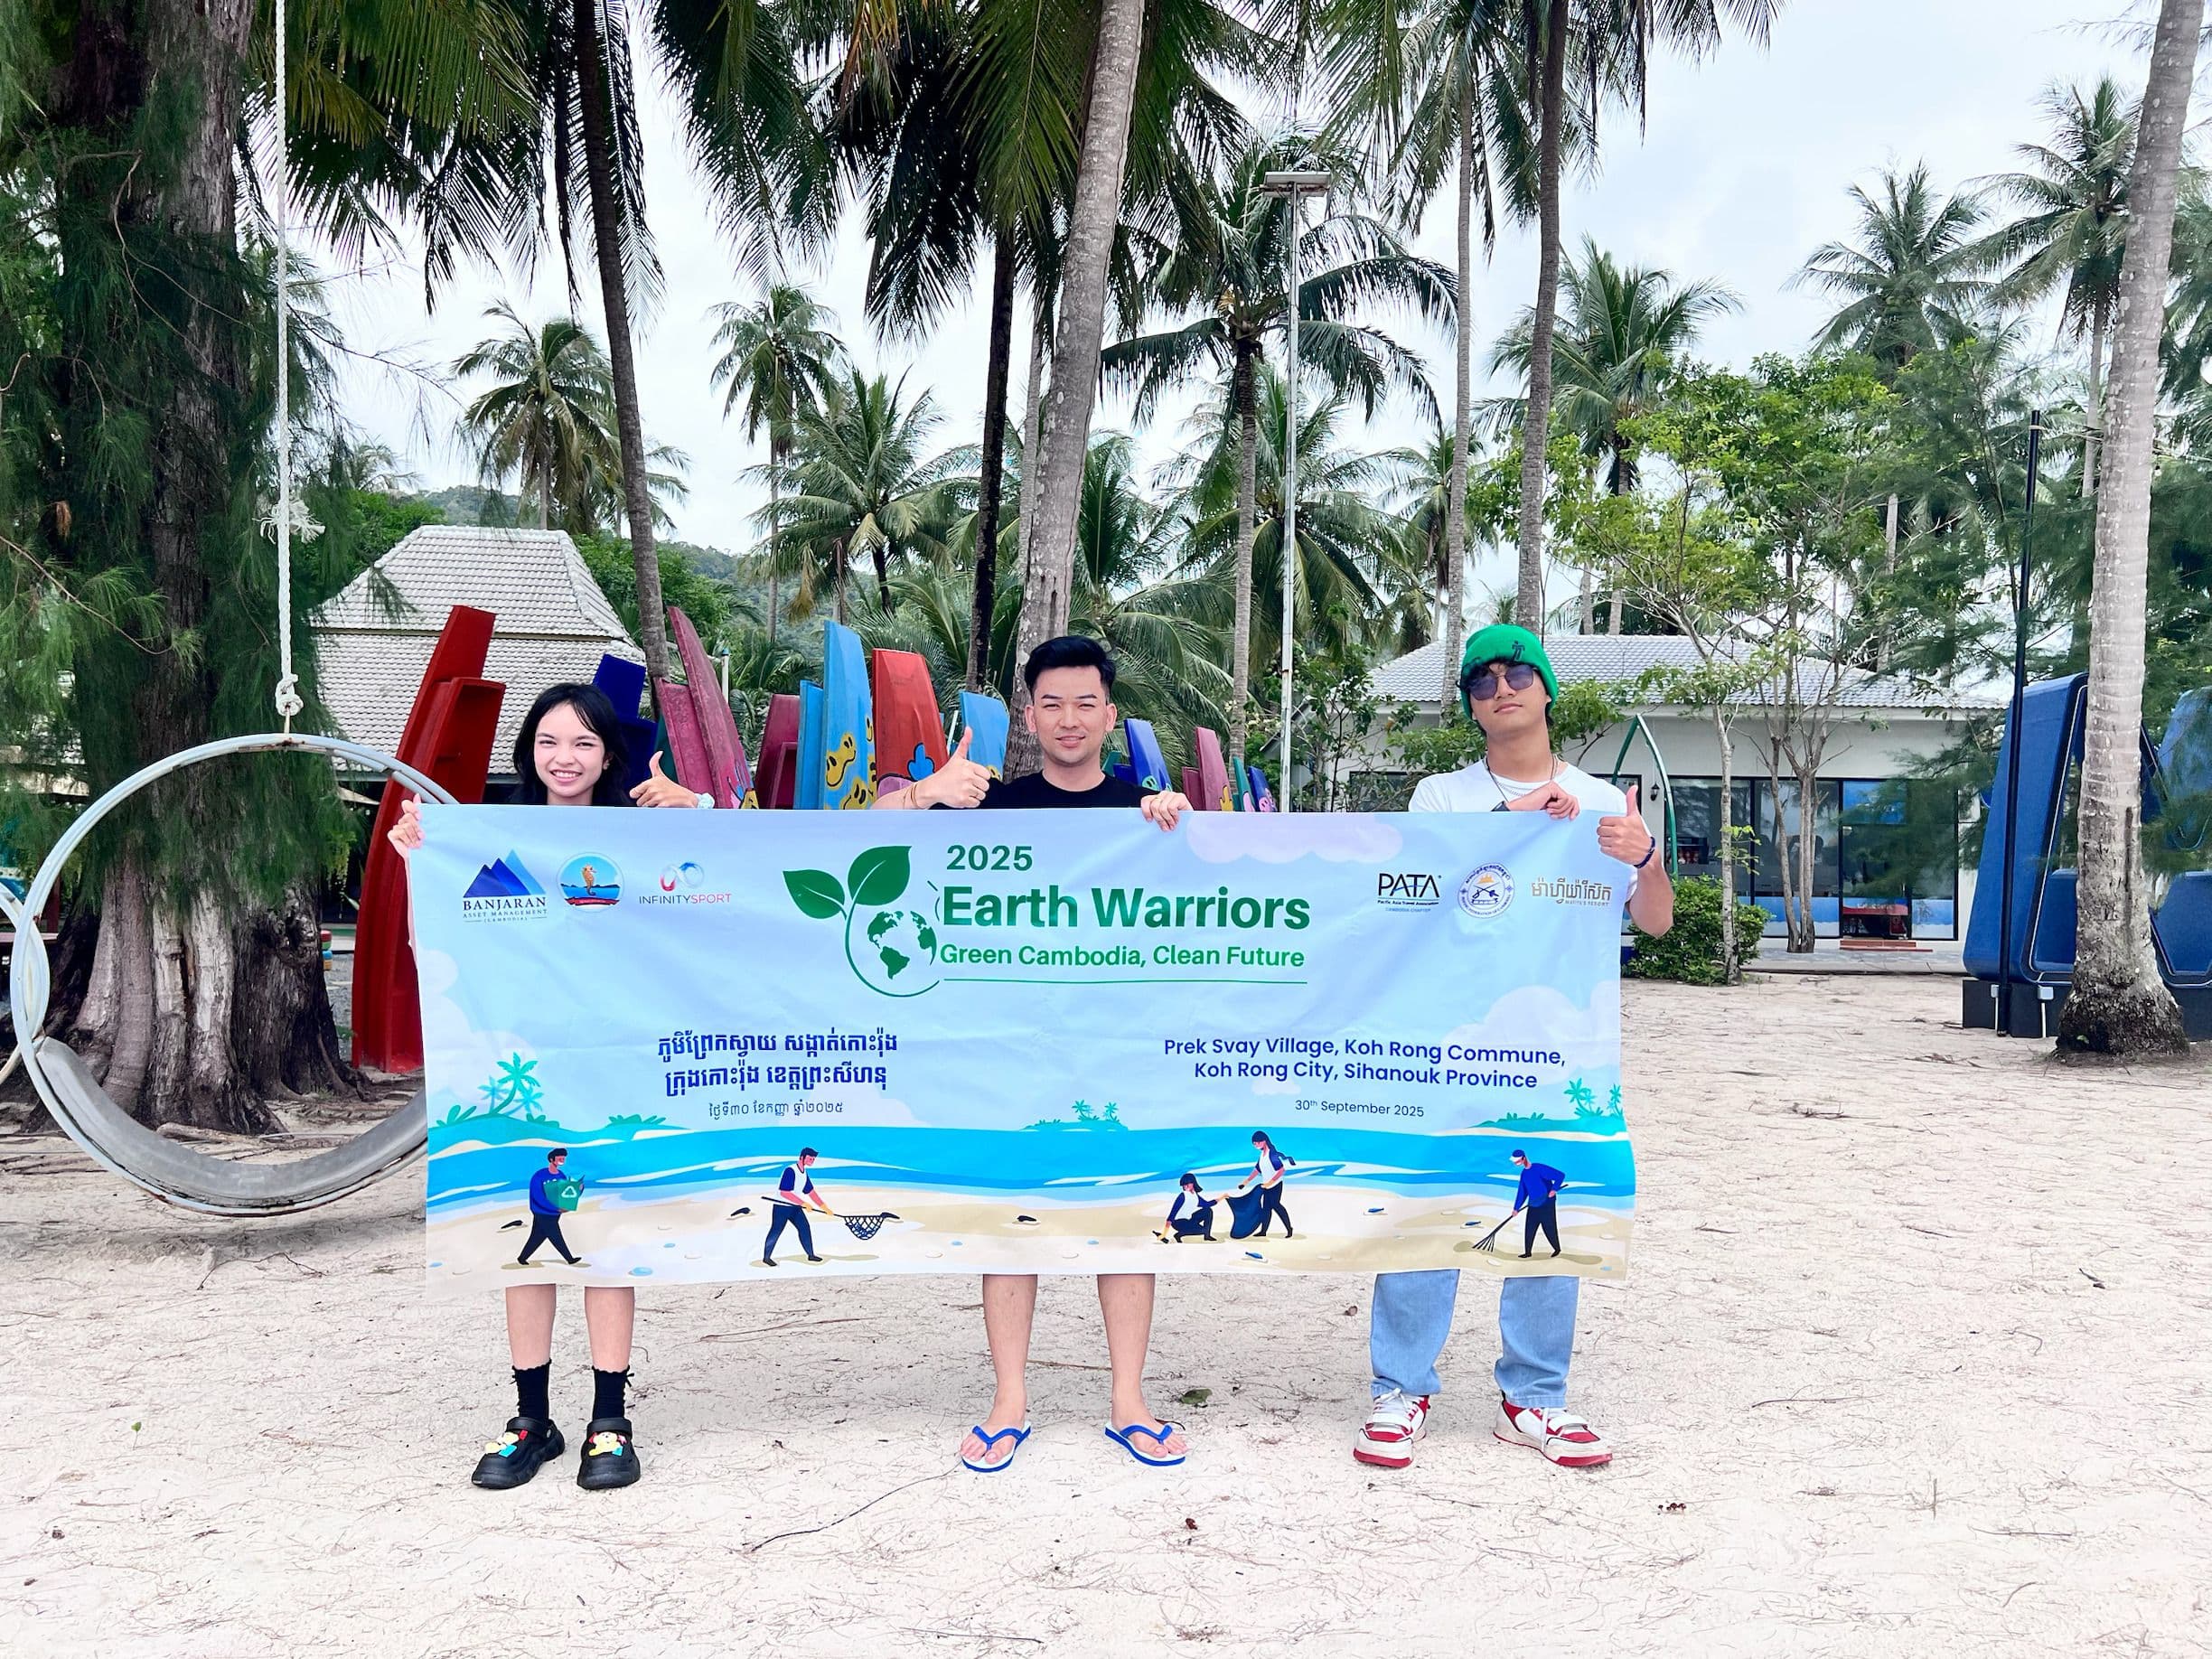
ទិវាអ្នកចម្បាំងផែនដី ឆ្នាំ២០២៥:កម្ពុជាស្អាត អនាគតស្អាត
នៅថ្ងៃអង្គារ ទី៣០ ខែកញ្ញា ឆ្នាំ២០២៥ ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក មានមោទនភាពជាថ្មីម្តងទៀតក្នុងការចូលរួមកម្មវិធី “ទិវាអ្នកចម្បាំងផែនដី ឆ្នាំ២០២៥” នៅក្រុងកោះរ៉ុង ខេត្តព្រះសីហនុ។ ក្នុងនាមជាអ្នកឧបត្ថម្ភដ៏មានន័យនេះ យើងខ្ញុំមានសេចក្តីសោមនស្សរីករាយក្នុងការប្តេជ្ញាចិត្តដើម្បីកម្ពុជាស្អាត អនាគតស្អាត និងដើម្បីធានាថាវាជាកំណប់ទ្រព្យសម្រាប់មនុស្សជំនាន់ក្រោយ។ រួមគ្នាជាមួយក្រុម Earth Warriors ក្រុមការងារយើងខ្ញុំបានជួយប្រមូលសំរាមសរុបចំនួន ២០០ គីឡូក្រាម ដែលជាការបង្កើតឥទ្ធិពលពិតប្រាកដក្នុងការអភិរក្សសោភ័ណភាពធម្មជាតិរបស់កោះនេះ។
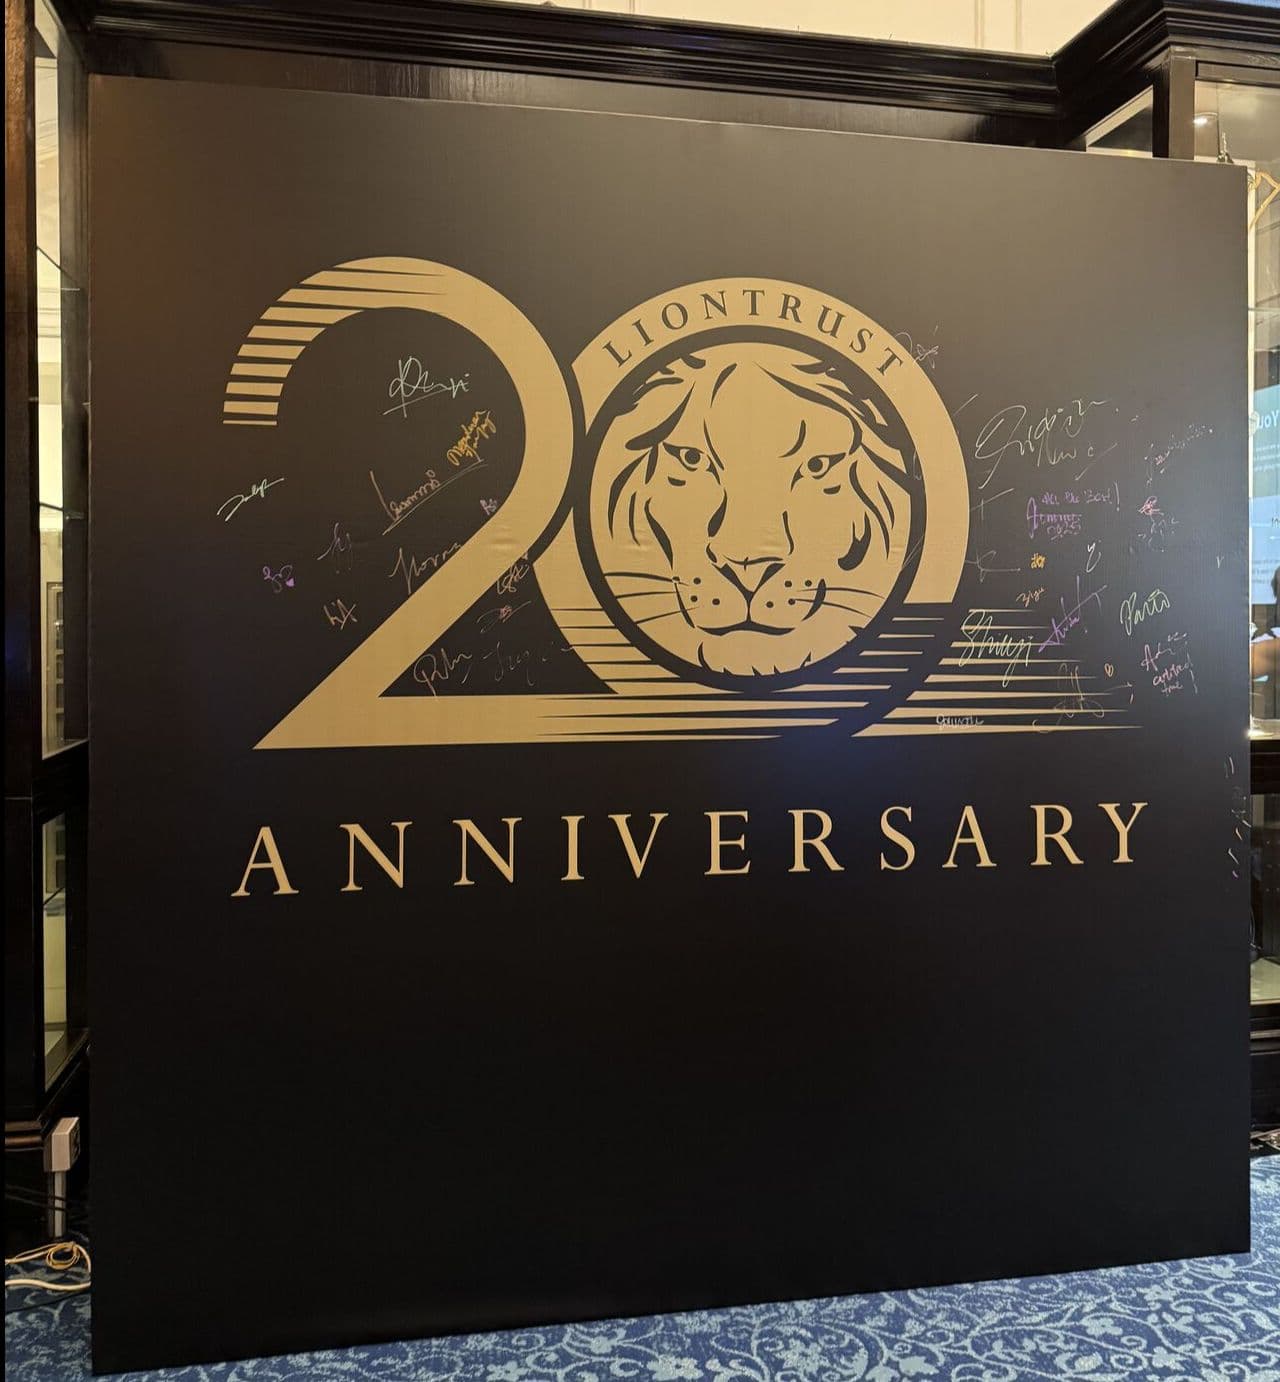
Banjaran AMC's CEO, Mr. Eric Loo, joins LionTrust’s 20th Anniversary Celebration
Singapore – September 5, 2025 Banjaran Asset Management (Cambodia) Plc. was invited to attend LionTrust Group's 20th-anniversary celebration in Singapore. It was an honor for our CEO and Executive Director, Mr. Eric , to join founders, partners, and industry peers in celebrating this remarkable milestone. LionTrust's two-decade journey is a powerful testament to the impact of trust, culture, and consistency. In an industry often focused on short-term gains, they have proven that genuine relationships and long-term stewardship are what build enduring success. This commitment deeply resonates with Banjaran Asset Management's mission in Cambodia. The principles LionTrust embodies are the very same we strive for: Trust as the cornerstone of every partnership. A collaborative culture that fosters shared purpose. Longevity built through alignment and sustainable growth. We extend our warmest congratulations to the entire LionTrust team. Their legacy of values and dedication is an inspiration, and we look forward to continued collaboration as we both work to shape a stable and prosperous financial future for our respective communities.
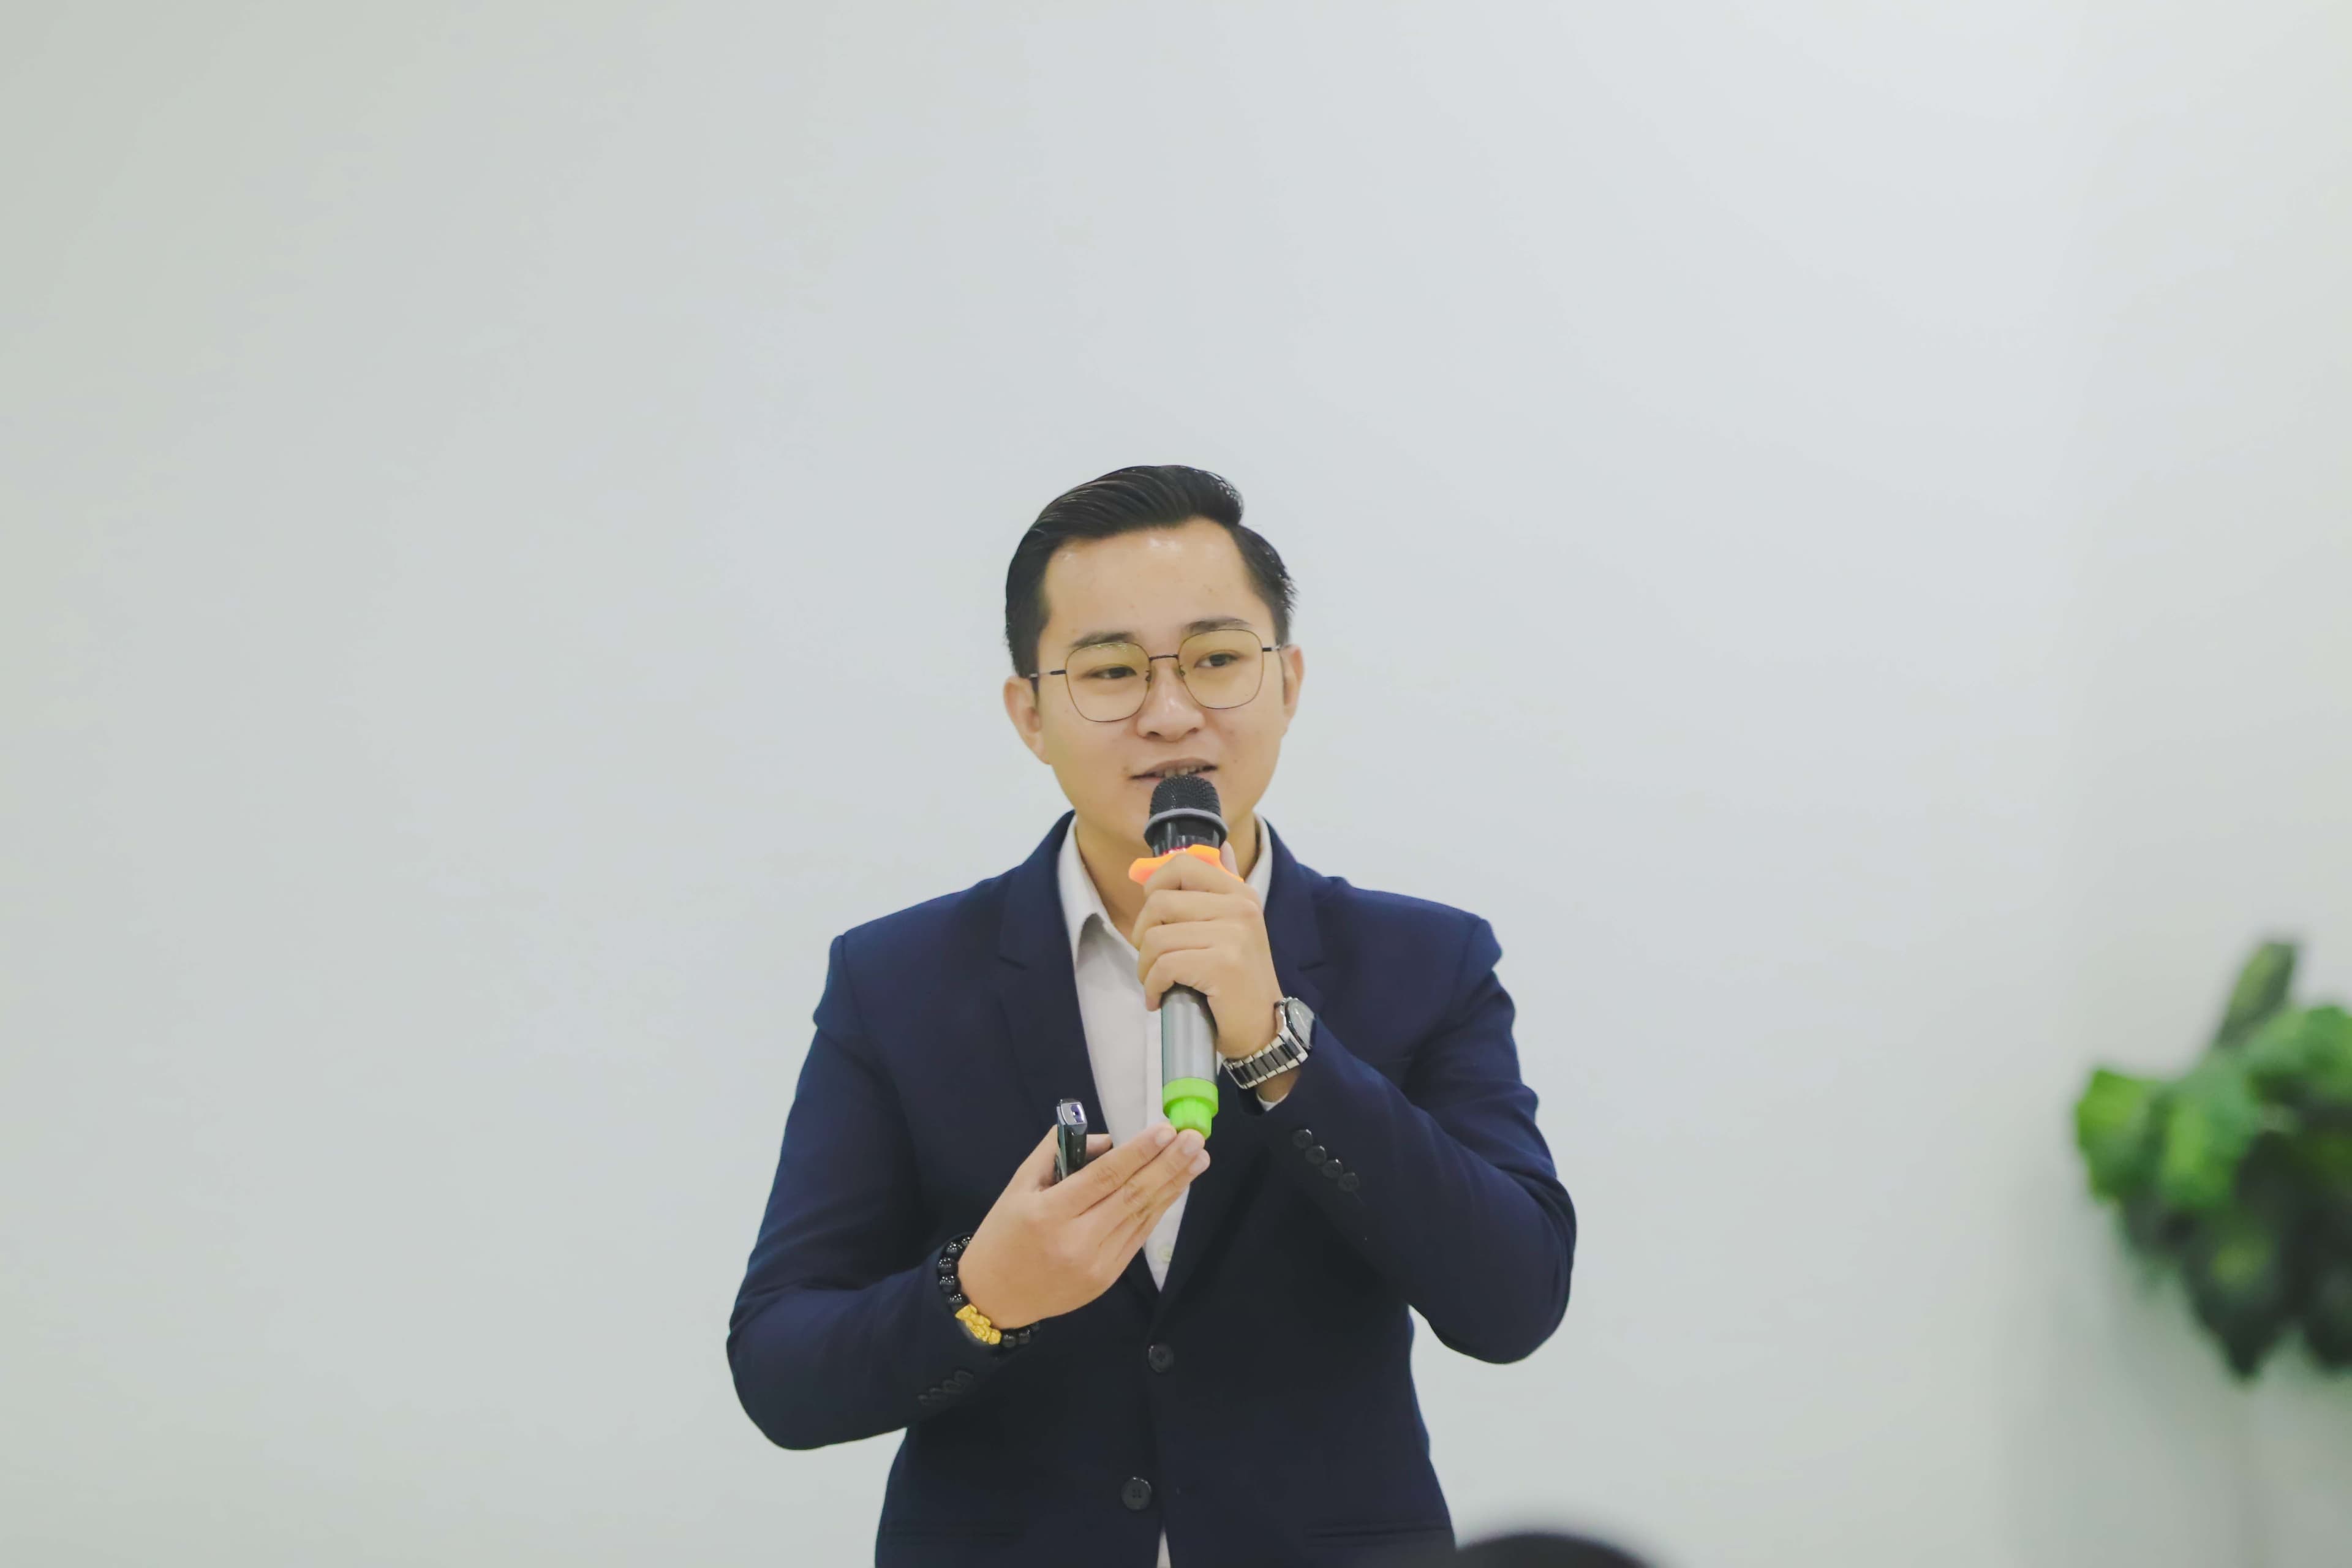
ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បាន ចែករំលែកចំណេះដឹងស្តីពី "គម្រោងវិនិយោគរួម" សម្រាប់និស្សិតសាកលវិទ្យាល័យ
នាព្រឹកថ្ងៃទី២៦ ខែសីហា ឆ្នាំ២០២៥ តំណាងក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានចូលរួមក្នុងវគ្គបណ្ដុះបណ្ដាលស្ដីពី "ការវិនិយោគឆ្លាតវៃ" រៀបចំឡើងដោយ ក្រុមហ៊ុនមូលបត្រ អេស៊ីលីដា ម.ក ដោយមានកិច្ចគាំទ្រពី និយ័តករមូលបត្រកម្ពុជា ផ្សារមូលបត្រកម្ពុជា និងសាកលវិទ្យាល័យអាស៊ី អឺរ៉ុប សម្រាប់និស្សិតនៃសាកលវិទ្យាល័យអាស៊ី អឺរ៉ុប។ នៅក្នុងវគ្គបណ្ដុះបណ្ដាលនេះ ដោយមានការអនុញ្ញាតពីថ្នាក់ដឹកនាំក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក លោក តាំង ហយ បុគ្គលិកផ្នែកច្បាប់និងអនុលោមភាព បានធ្វើបទបង្ហាញស្ដីពី "គម្រោងវិនិយោគរួម" ដែលចំណេះដឹងវិនិយោគថ្មីសម្រាប់វិស័យមូលបត្រនៅកម្ពុជា។ វគ្គបណ្ដុះបណ្ដាលនេះត្រូវបានរៀបចំឡើងក្នុងគោលបំណងលើកកម្ពស់ការយល់ដឹងផ្នែកហិរញ្ញវត្ថុ ការបង្កើតទម្លាប់សន្សំប្រកបដោយប្រសិទ្ធភាព និងលើកកម្ពស់ការវិនិយោគប្រកបដោយភាពឆ្លាតវៃ សម្រាប់និស្សិតនៃសាកលវិទ្យាល័យ។
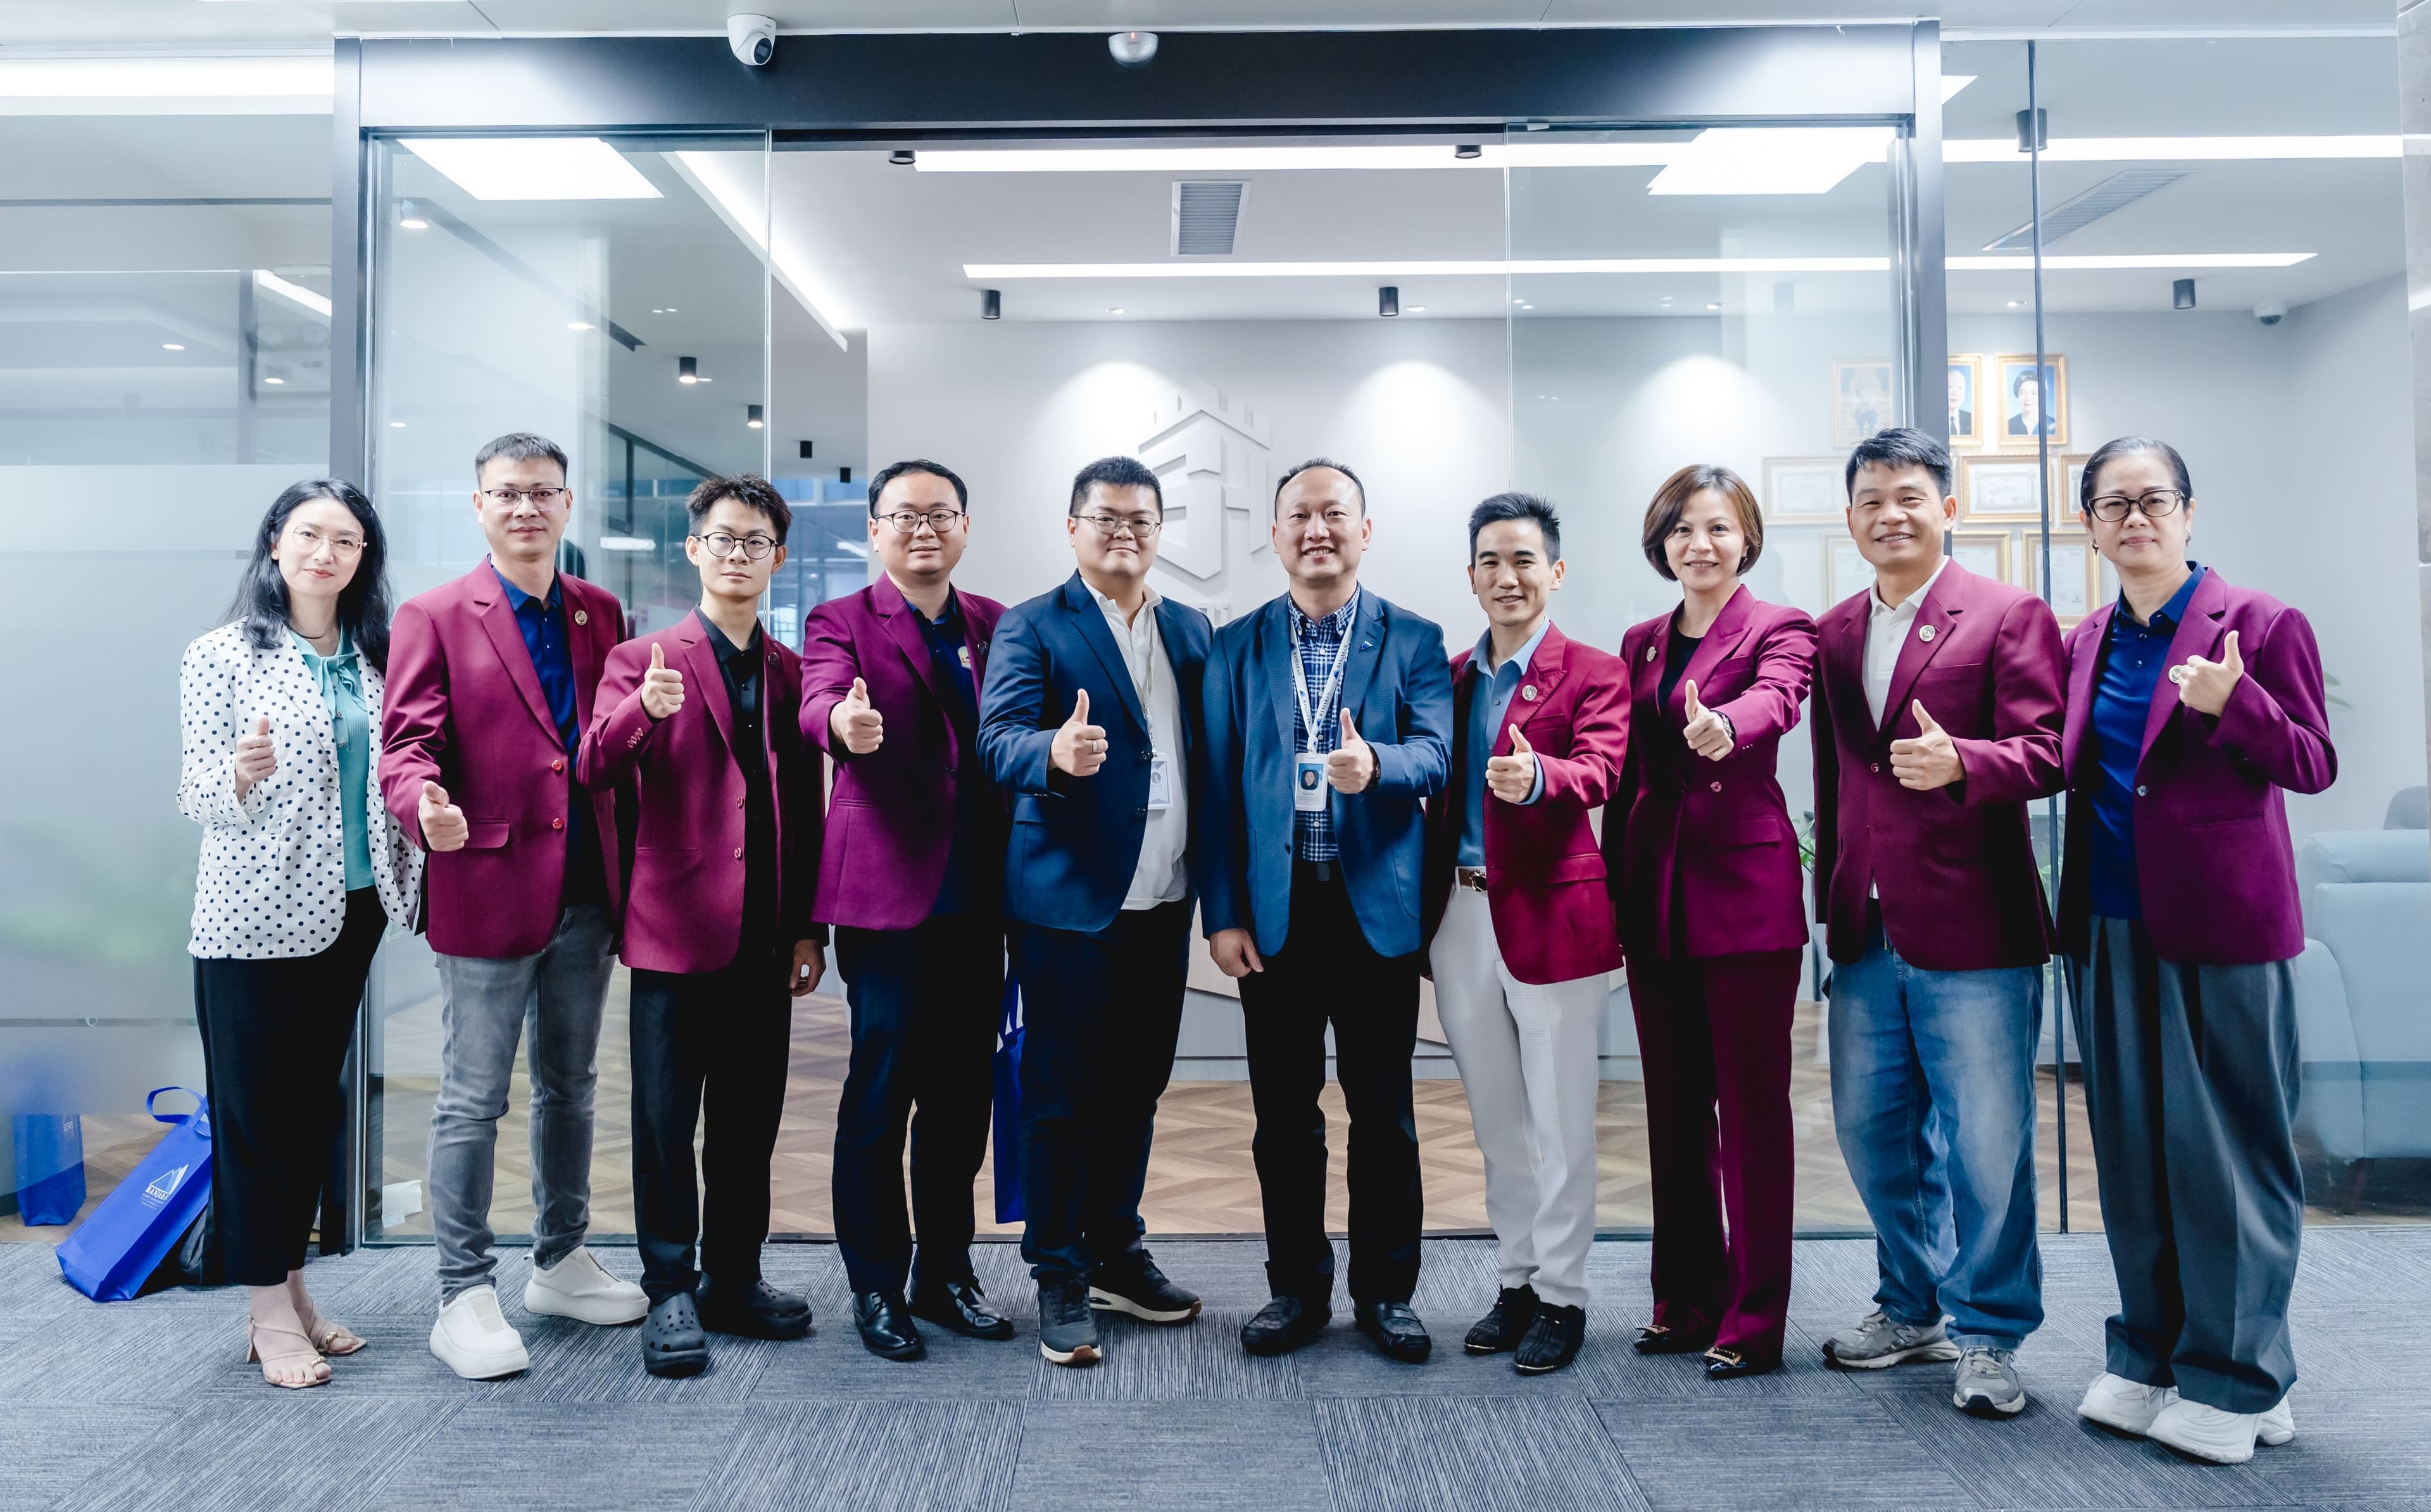
Shaping Cambodia’s Financial Future: Insights from Industry Leaders
The recent session on 22nd of August 2025, brought together industry leaders to share their expertise on pivotal topics shaping Cambodia’s financial sector. Mr. Eric Loo opened with an impactful presentation on “The Profound Significance of Successfully Launching Cambodia’s First Public Fund for the National Economy and Financial System”. He highlighted Banjaran AMC’s footprint as a pioneer in the Cambodian market, discussing the challenges faced in introducing the country’s first public fund and the company high standards in setting to the industry to ensure transparency, security, and investor confidence. He also emphasizes how this succession brings economic advantages, one such as attracting new investment opportunities and how the CIS can support projects & SMEs in driving growth. His insights underscored the importance of innovation and diligence in building a financial system that strengthens both the economy and the investment landscape. Following this, Mr. Hans Chen from StrongHold Trustee introduced his company and elaborated on the importance of trustee services, underscoring their role in ensuring security, transparency, and trust in the management of collective investment schemes. Finally, Mr. Zhang Dazhi shared his expertise on corporate compliance in Cambodia, discussing practical strategies for businesses to manage risks effectively. He covered key areas including proper tax planning, sustainable growth through EIAs, accurate reporting, and overall adherence to regulatory requirements, providing guidance on how companies can navigate the evolving compliance landscape safely. Together, these discussions highlighted the collective efforts of industry experts in shaping a stronger, more resilient, and forward-looking financial ecosystem for Cambodia.
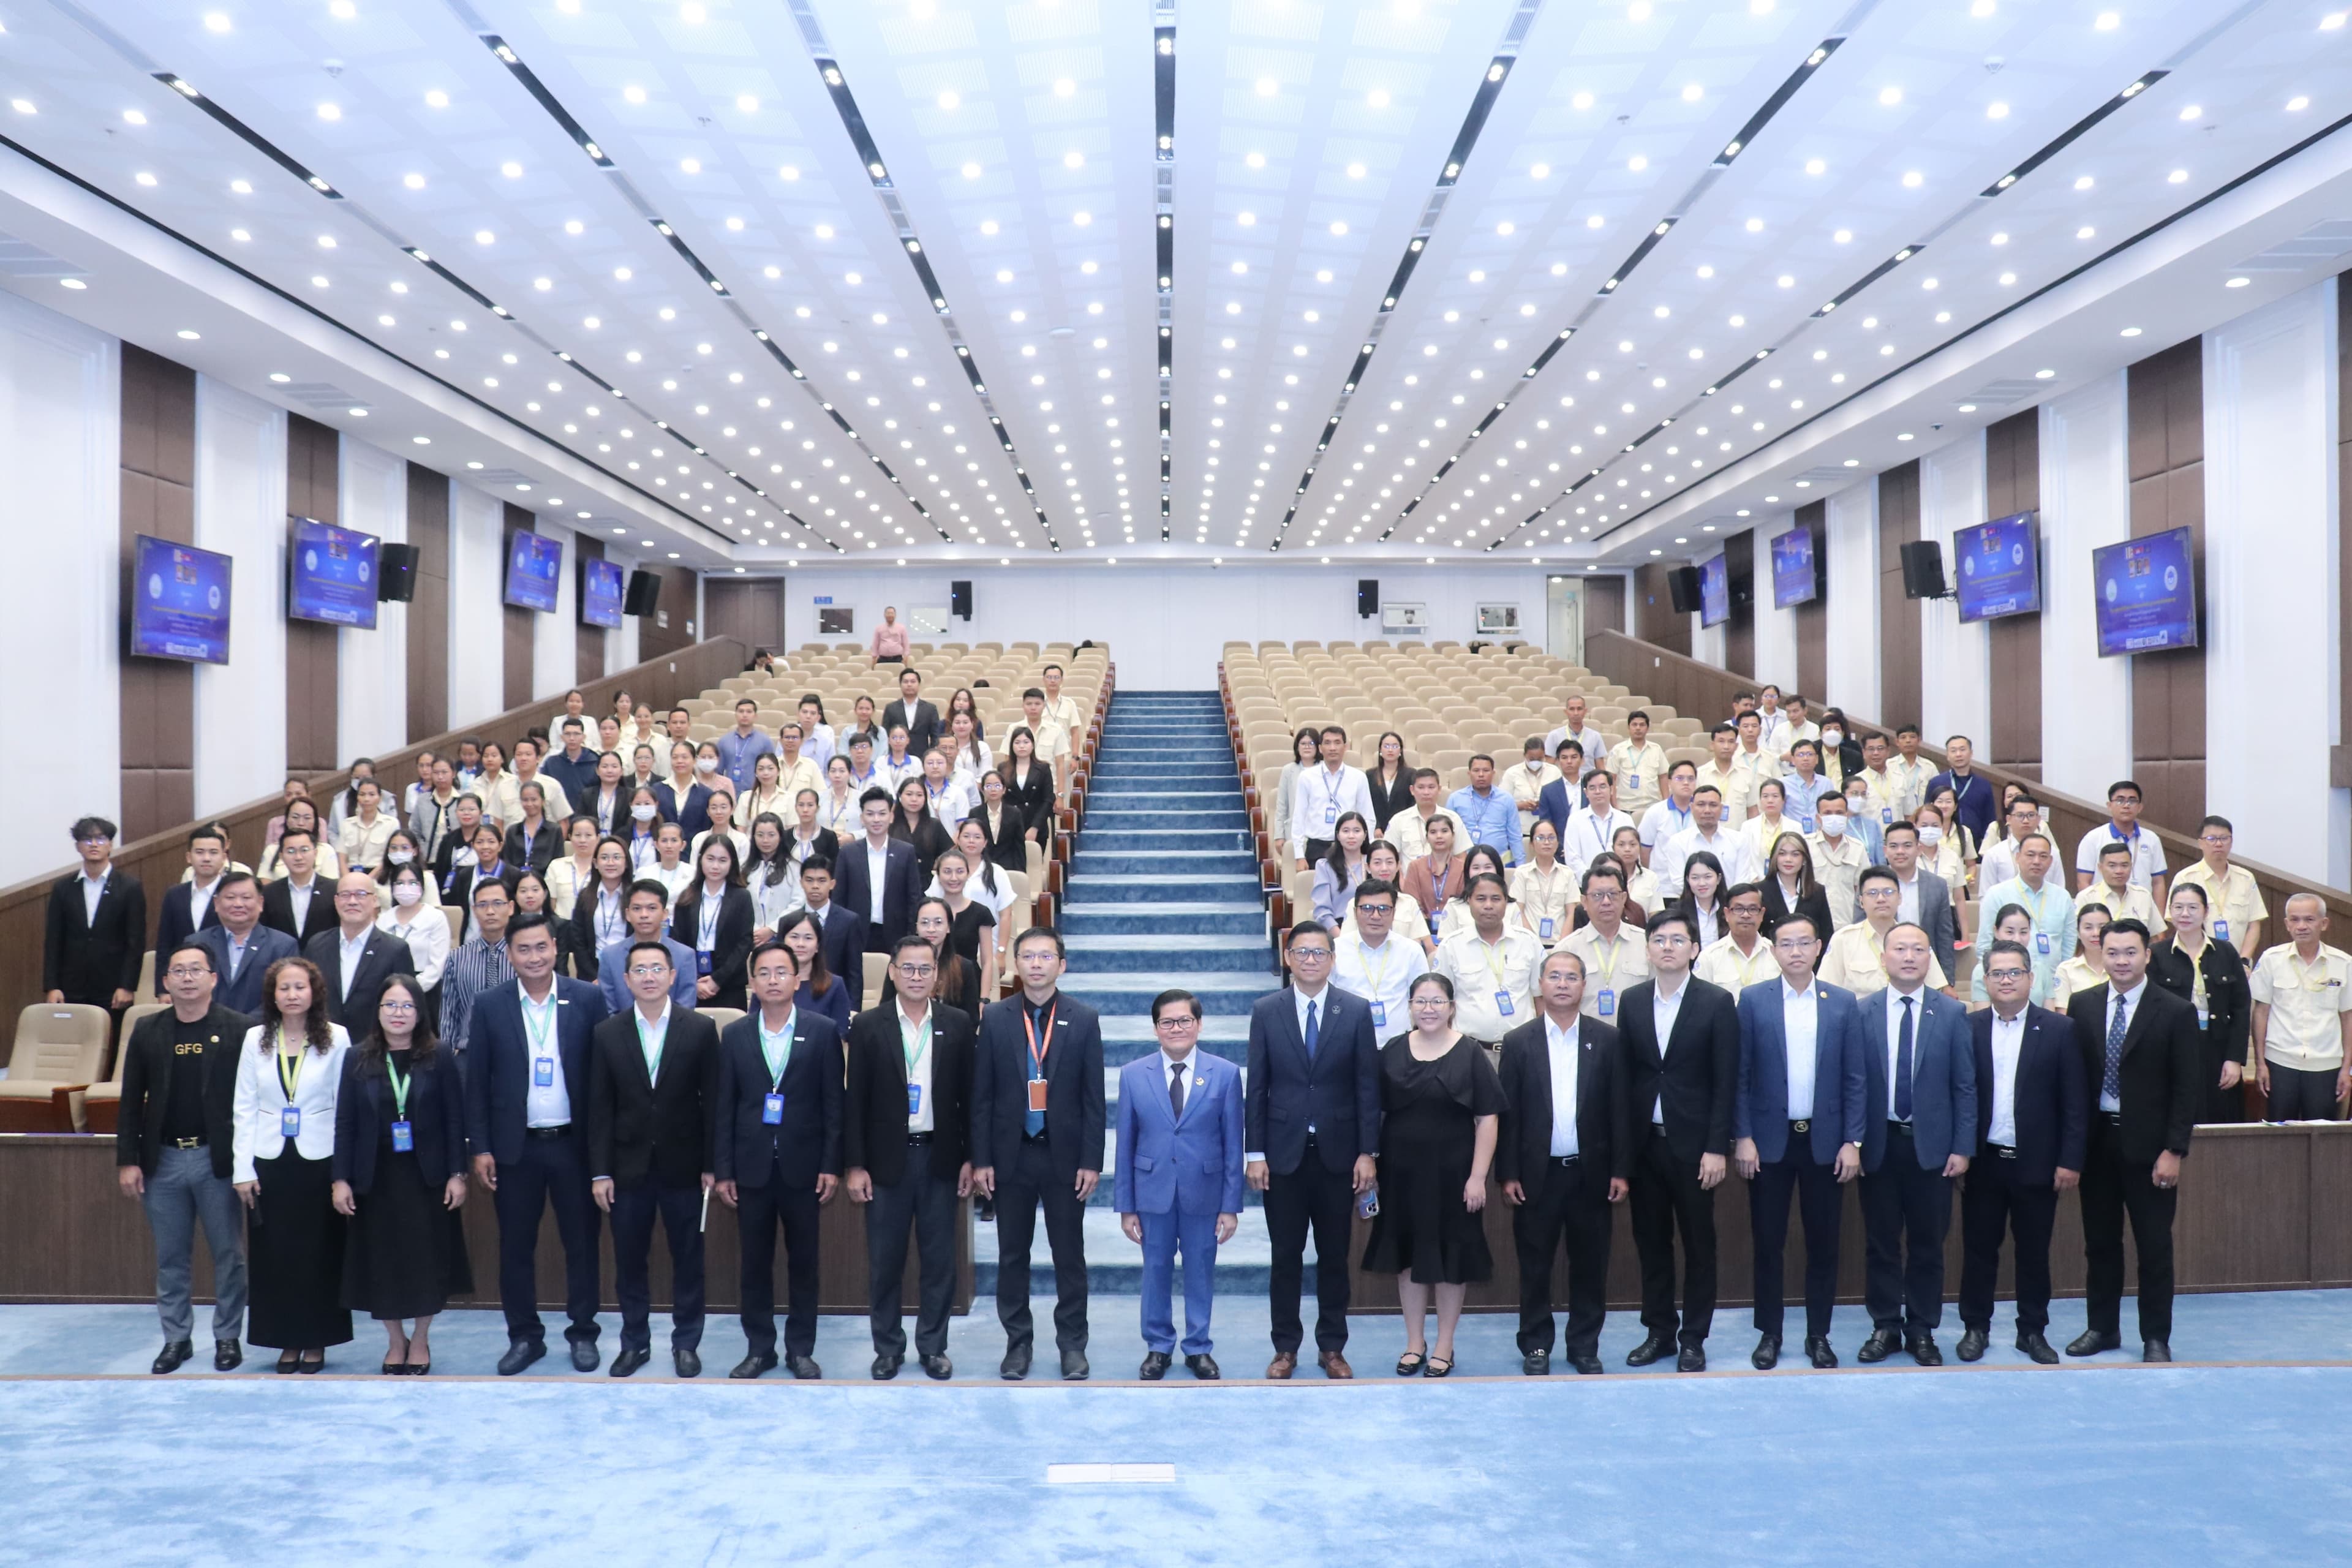
ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានដើរតួនាទីយ៉ាងសំខាន់នៅក្នុងសិក្ខាសាលាថ្នាក់ជាតិស្តីពីឧបករណ៍វិនិយោគ
នៅថ្ងៃទី១៤ ខែសីហា ឆ្នាំ២០២៥ ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានចូលរួមក្នុងសិក្ខាសាលាថ្នាក់ជាតិមួយ ដែលផ្តោតលើប្រធានបទ "ការឈ្វេងយល់អំពីឧបករណ៍វិនិយោគ និងហិរញ្ញប្បទានក្នុងវិស័យមូលបត្រ"។ ព្រឹត្តិការណ៍នេះ ត្រូវបានរៀបចំនៅស្នាក់ការកណ្តាល នៃបេឡាជាតិសន្តិសុខសង្គម (ប.ស.ស.) ដែលរៀបចំដោយ និយ័តករមូលបត្រកម្ពុជា (ន.ម.ក.) និងបេឡាជាតិសន្តិសុខសង្គម (ប.ស.ស.) និងមានការគាំទ្រពី ផ្សារមូលបត្រកម្ពុជា (ផមក) ក្រុមហ៊ុនមូលបត្រ អេស៊ីលីដា ម.ក ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក និងក្រុមហ៊ុន Gold Financial Global Investment Co., Ltd. (GFG)។ សិក្ខាសាលានេះមានសិក្ខាកាមចូលរួមប្រមាណជាង១៥០នាក់ ដែលរួមមានថ្នាក់ដឹកនាំ មន្រ្តីរាជការ និងអ្នកជំនាញវិជ្ជាជីវៈក្នុងវិស័យហិរញ្ញវត្ថុ។ ឯកឧត្តម គឹម កែវរស្មី អគ្គនាយករង នៃបេឡាជាតិសន្តិសុខសង្គម (ប.ស.ស.) បានថ្លែងកោតសរសើរចំពោះសារៈសំខាន់ជាវិជ្ជមានរបស់ប័ណ្ណសមាជិក ប.ស.ស. ក្នុងការជួយសម្រួលដល់ការចំណាយលើថ្លៃព្យាបាល និងថ្លៃពិនិត្យដល់ប្រជាពលរដ្ឋ។ ទន្ទឹមនឹងនេះ ឯកឧត្តមក៏បានលើកសរសើរពីការប្តេជ្ញាចិត្តរបស់ ប.ស.ស. ក្នុងការផ្តល់សេវាសន្តិសុខសង្គម និងសេវាហិរញ្ញវត្ថុសំខាន់ៗ ដើម្បីអត្ថប្រយោជន៍ដល់សមាជិកគ្រប់រូប។ ឯកឧត្តមក៏បានបញ្ជាក់អំពីសារៈសំខាន់នៃឱកាសវិនិយោគ ក្នុងការជួយបន្ថែមដល់ការការពារសង្គម និងធានានិរន្តរភាពរយៈពេលវែង។ សុន្ទរកថារបស់ឯកឧត្តម ឆ្លុះបញ្ចាំងពីការគាំទ្រនិងការទទួលស្គាល់ប្រកបដោយគុណតម្លៃពីថ្នាក់ដឹកនាំនៃរាជរដ្ឋាភិបាល ក៏ដូចជាការគូសបញ្ជាក់ពីសារៈសំខាន់ជាយុទ្ធសាស្ត្រនៃកិច្ចសហប្រតិបត្តិការរវាងក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក និងបេឡាជាតិសន្តិសុខសង្គម (ប.ស.ស.) ក្នុងការជំរុញសុខុមាលភាពជាតិ និងកំណើនសេដ្ឋកិច្ចរយៈពេលវែង។ វត្តមានរបស់ លោក Eric Loo នាយកប្រតិបត្តិនិងអភិបាលប្រតិបត្តិ នៃក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានគូសរំលេចពីតួនាទីរបស់ក្រុមហ៊ុនក្នុងនាមជាអ្នកនាំមុខគេក្នុងការបង្កើតឱ្យមានទីផ្សារគ្រប់គ្រងមូលនិធិ ដែលកំពុងរីកចម្រើននៅកម្ពុជា។ ចក្ខុវិស័យនិងភាពដឹកនាំរបស់លោក មានឥទ្ធិពលយ៉ាងសំខាន់ក្នុងការជំរុញបង្កើតមូលនិធិថ្មីៗបន្ថែមទៀត និងធ្វើឱ្យក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ក្លាយជាក្រុមហ៊ុននាំមុខដំបូងគេក្នុងទីផ្សារកម្ពុជា។ លោក Low Hon-Yu និង លោក Christopher Wong សមាជិកក្រុមប្រឹក្សាភិបាលដែលមានមូលដ្ឋាននៅប្រទេសសិង្ហបុរី ក៏បានចូលរួមដើម្បីបង្ហាញការគាំទ្រយ៉ាងពេញទំហឹងចំពោះសកម្មភាពថ្នាក់ជាតិដ៏សំខាន់នេះ។ ការរួមបញ្ចូលគ្នារវាងភាពដឹកនាំក្នុងស្រុកនិងភាពជំនាញអន្តរជាតិ គឺជាកត្តាសំខាន់មួយដែលធ្វើឱ្យក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក មានលក្ខណៈពិសេសផ្ទាល់ខ្លួន។ ការប្តេជ្ញាចិត្តរបស់ ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក ក្នុងការកសាងទីផ្សារដែលរឹងមាំ មិនត្រូវបានមើលរំលងឡើយ។ ឯកឧត្តម ស៊ូ សុជាតិ ប្រតិភូរាជរដ្ឋាភិបាលទទួលបន្ទុកជាអគ្គនាយកនៃនិយ័តករមូលបត្រកម្ពុជា (ន.ម.ក.) បានបង្ហាញការកោតសរសើរគួរឱ្យកត់សម្គាល់ ចំពោះភាពជាអ្នកគាំទ្រដែលរួមចំណែកសំខាន់ក្នុងភាពជោគជ័យនៃសិក្ខាសាលា និងការប្តេជ្ញារបស់ក្រុមហ៊ុនក្នុងការបណ្តុះបណ្តាលអ្នកវិនិយោគ និងអភិវឌ្ឍទីផ្សារ។ ការទទួលស្គាល់នៅកម្រិតខ្ពស់នេះ បញ្ជាក់យ៉ាងច្បាស់ពីតួនាទីដ៏សំខាន់របស់យើង ក្នុងការកសាងទំនុកចិត្ត និងការផ្សព្វផ្សាយចំណេះដឹង នៅក្នុងប្រព័ន្ធអេកូហិរញ្ញវត្ថុរបស់កម្ពុជា។ លោក ញ៉ែម សុប៉ុល ប្រធានផ្នែកគ្រប់គ្រងសាជីវកម្ម នៃក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានធ្វើបទបង្ហាញអំពី "គម្រោងវិនិយោគរួម (CIS)" ដោយបានសម្រាយប្រធានបទហិរញ្ញវត្ថុដ៏ស្មុគស្មាញនេះឱ្យងាយយល់សម្រាប់មន្រ្តីរាជការនៃ ប.ស.ស.។ លោកបានបង្ហាញពីរបៀបដែលមូលនិធិទាំងនេះអាចបង្កើតឱកាសវិនិយោគដោយមានវិន័យ និងមានភាពចម្រុះសម្រាប់ប្រជាជនកម្ពុជាទូទៅ ដែលឆ្លុះបញ្ចាំងពីការប្តេជ្ញារបស់ក្រុមហ៊ុនក្នុងការផ្តល់សិទ្ធិសម្រេចដល់វិនិយោគិន។ ការអនុវត្តការងារប្រកបដោយទស្សនវិស័យ និងការយកចិត្តទុកដាក់លើការអប់រំរបស់ក្រុមហ៊ុន បានបង្កើនការចាប់អារម្មណ៍យ៉ាងខ្លាំងនៅក្នុងសិក្ខាសាលា។ សិក្ខាសាលានេះបានបង្កើតឱ្យមានទំនាក់ទំនង ពិភាក្សា និងសន្ទនាដ៏មានអត្ថន័យជាមួយនាយកប្រតិបត្តិនិងថ្នាក់ដឹកនាំជាច្រើន ដែលបានបង្ហាញពីការចាប់អារម្មណ៍ចំពោះមូលនិធិរបស់ក្រុមហ៊ុន។ នេះបញ្ជាក់ថា ការខិតខំប្រឹងប្រែងរបស់យើងក្នុងការដឹកនាំទីផ្សារវិនិយោគនៅកម្ពុជា កំពុងទទួលបានជោគជ័យ និងកំពុងបង្កើនកិត្តិនាមរបស់យើង ជាអ្នកនាំមុខគេក្នុងទីផ្សារ ដែលគួរឱ្យទុកចិត្ត។ ដោយមានភាពដឹកនាំដ៏រឹងមាំនិងភាពជំនាញអន្តរជាតិ ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បានប្តេជ្ញាចិត្តចំពោះបេសកកម្មរបស់ខ្លួន គឺ៖ ធ្វើឱ្យការវិនិយោគអាចដំណើរការបានយ៉ាងទូលំទូលាយ បង្កើនការយល់ដឹងពាក់ព័ន្ធនឹងហិរញ្ញវត្ថុ និងមានតួនាទីប្រែក្លាយអនាគតនៃវិស័យហិរញ្ញវត្ថុរបស់កម្ពុជា។
Cambodia Capital Markets Assessment Report
On July 11, 2025, Banjaran Asset Management (Cambodia) Plc. had the privilege of participating in the IFC Capital Markets Assessment & Fundraising Event, held at the Hyatt Regency Phnom Penh. This high-level session, hosted by the International Finance Corporation (IFC), brought together key stakeholders across Cambodia’s financial sector—including fund managers, insurance providers, regulators, and banks—to explore strategies for strengthening the country’s capital markets. The discussions centered on unlocking new capital-raising opportunities, with particular emphasis on the development of Cambodia’s bond market as a vehicle for long-term investment and sustainable economic growth. Representing Banjaran AMC were Mr. Aaron Ng , CEO of Banjaran Asset Management Pte Ltd (Singapore), and Mr. Jevin Loo , Business Manager of Banjaran Asset Management (Cambodia) Plc.. During the event, our senior representatives had the opportunity to engage directly with IFC officials, introduce Banjaran AMC’s core mission, and present the impactful work being done through initiatives such as the K-Fund —a Collective Investment Scheme focused on agriculture and empowering local farmers that support the workshop's vision. IFC representatives expressed strong recognition and interest in Banjaran’s vision and ongoing efforts. These interactions helped lay the groundwork for potential future collaboration and opened new doors for strategic engagement in Cambodia’s fast-evolving investment environment. This event marked an important milestone in Banjaran AMC’s ongoing efforts to connect global capital with local opportunity, and to support the development of Cambodia’s financial ecosystem through innovation, transparency, and inclusion.
ទស្សនៈទីផ្សារ
2024 April, Market Outlook: Navigating Volatility Amidst Inflation, Interest Rates, and Geopolitical Risks
Recently, both the bond and stock markets have experienced heightened volatility, driven by inflation and retail sales in the US consistently exceeding expectations. In response, the Federal Reserve once again opted to hold off on lowering interest rates, waiting for more comprehensive data before making further policy decisions. This cautious approach led investors to adjust their interest rate forecasts aggressively, which directly impacted equity markets. We believe these concerns are justified, especially as commodity prices have surged, potentially contributing to higher inflation in the months ahead. At present, we assess that the recent equity price movements may be a short-term reaction to rising bond yields, and we will continue to monitor these trends closely. In China, the government's initiative to support "whitelist" property projects has made significant progress, with funds raised reaching RMB 469 billion by the end of March—more than double the RMB 200 billion previously reported. Given the size of China’s residential property sector, we anticipate further substantial disbursements. Additionally, there is an expectation that the People’s Bank of China will gradually increase government bond trading through its open market operations, signaling a form of monetary policy easing. These developments, along with China's Q1 GDP growth and improved PMI numbers, offer positive signals for the economy. However, we recognize initial signs of a slowdown in key economic indicators, such as retail sales and industrial production, reflecting lingering sluggishness in the domestic economy. We will continue to track these factors in the coming months. On the geopolitical front, tensions between Iran and Israel are escalating, with Israel considering its response to recent drone strikes by Iran. This situation could significantly impact crude oil prices, introducing further inflationary risks in the near term. Meanwhile, the ongoing US-China tensions remain a long-term issue. Recently, US lawmakers introduced a bill that would bar mutual funds from investing in indices that include Chinese stocks. This follows a broader trend of global portfolio allocations shifting away from China over the past year. As a result, we have observed a substantial valuation premium in the US market relative to China, far exceeding historical norms. We believe that once the Chinese economy stabilizes and returns to sustainable growth, this valuation gap may narrow. In the near term, inflationary risks in the US and uncertainty in China could present challenges for equity markets. However, our analysis of current data suggests that this may be a temporary correction, largely driven by high valuations in developed markets. We remain focused on identifying attractive opportunities as they emerge in the evolving market landscape.
2024 March, Market Outlook: Navigating Elevated Interest Rates, China’s Economic Measures, and Corporate Earnings
Throughout the month, the Federal Reserve reinforced its stance that there is no urgency to lower interest rates during the first half of 2024. Notably, the Fed addressed growing concerns within the commercial real estate sector, acknowledging that while the situation remains manageable for now, it may lead to further banking failures. This dovetails with our cautious outlook on the potential consequences of keeping interest rates elevated for too long, especially if policy missteps occur. High rates for an extended period could stress certain sectors, particularly real estate, heightening risks within financial markets. In China, the government has begun to take action to support previously announced “whitelist” property projects. Major commercial banks have approved over RMB 200 billion in loans to facilitate the completion of these projects. While this is a positive step, further financing will likely be necessary to ensure sufficient liquidity for the real estate sector's recovery. We will continue to monitor further policy announcements and their impact on property sales and prices in the coming months. The recently concluded "Two Sessions" meeting of the Chinese Communist Party revealed economic targets similar to those set last year. The 5.0% GDP growth target for 2024 appears ambitious, especially in light of the modest 3.0% deficit target and the conservative spending habits of Chinese consumers. However, we believe this growth target is achievable, given the gradual shift in consumer behavior towards increased spending. Furthermore, growth outside of the real estate sector remains robust, offering a positive outlook for broader economic recovery. In the corporate world, recent earnings reports from leading companies have generally shown strong growth for Q4 2023, with some projecting modest top-line expansion in 2024. However, US stocks that missed earnings expectations and guidance experienced sharp declines, a consequence of their elevated valuations. Given the uncertain economic outlook, we will closely monitor both economic and industry-specific data to inform our next portfolio decisions. Despite these short-term uncertainties, we remain positive about the long-term potential of our holdings. In conclusion, as central banks maintain a cautious stance on interest rates and China accelerates its economic support, global markets face a delicate balancing act in 2024. Careful navigation through these challenges will be key for investors seeking sustainable growth opportunities.
2024 February, Market Outlook: Navigating Central Bank Strategies and Growth Opportunities in Asia
As we step into 2024, initial hopes for early interest rate cuts by the US Federal Reserve (FED) and the European Central Bank (ECB) are fading. Both central banks have downplayed the likelihood of reducing rates anytime soon, largely due to strong economic data released in recent months. The US economy continues to display resilience, with sustained expansion indicating that the FED must tread carefully. Lowering interest rates too soon could risk reigniting inflation, which the central bank is keen to avoid. At the same time, there are pockets of weakening growth within the economy, signaling the potential for a broader slowdown. This delicate balancing act places the FED in a challenging position, where policy mistakes could have significant consequences for both the US economy and global financial markets. In line with our earlier expectations, the Eurozone also faces similar inflationary pressures, with energy prices remaining persistently high. As a result, inflation remains sticky, preventing the ECB from easing rates. We foresee that both central banks will need to remain vigilant in navigating the complex dynamics of their respective economies, weighing inflation risks against the threat of economic slowdowns. Meanwhile, China's approach to monetary policy has taken a markedly different turn. The Chinese government recently lowered the 5-year loan prime rate by 25 basis points to 3.95%, signaling its determination to stimulate the economy and support the real estate sector. Under the “whitelist” initiative, commercial banks are encouraged to provide lending to property projects approved by local governments. These rapid, proactive measures underscore the government's commitment to front-loading stimulus to prevent weak sentiment in the housing market from deepening. We believe these policies will continue to evolve progressively, ensuring that the real estate sector stabilizes and recovers on a sustainable path. Signs of improvement are already emerging in China’s economy. Recent data on monetary aggregates indicate positive movement, and domestic travel and spending during the Lunar New Year suggest a rebound in consumer activity. On the global stage, China’s exports have grown for the second consecutive month in December 2023, further reinforcing the positive outlook for 2024. These rapid policy moves come as the State Council calls for "forceful measures" to restore confidence in both the economy and financial markets. Japan is also showing signs of strength, with the economy benefiting from long-anticipated corporate reforms. After decades of deflation, Japan appears to be breaking free from this prolonged economic phase. Reforms aimed at improving corporate profit margins and shareholder returns are finally coming to fruition, marking the end of the country's 30-year deflationary struggle. We believe these developments will unlock significant value for shareholders, creating opportunities for growth in the Japanese market. In summary, we remain optimistic about the prospects for the Asian markets, particularly as China and Japan implement aggressive economic measures. Conversely, we approach the US markets with caution, given the headwinds presented by inflationary pressures and an overconcentration in the technology sector. As we move forward, the balancing act between growth, inflation, and central bank policy will continue to shape the global market landscape, with Asia emerging as a bright spot for investors in 2024.
2024 January, Market Outlook - Navigating 2024 Amid Geopolitical Tensions and Economic Shifts
As we enter 2024, the global financial landscape is expected to shift focus from rising bond yields to interest rate stabilization and potential easing, particularly by the US Federal Reserve. After three years of tightening policies, we anticipate that both the US and Europe will experience sharply slower economic activity and increased unemployment. Europe, in particular, faces heightened risks of a prolonged recession. While interest rates in the US may hold steady for now, primarily due to persistent inflation pressures in areas like housing, rising geopolitical risks, such as recent airstrikes by the US and UK in response to Houthi rebel attacks, could lead to disruptions in global trade and shipping costs. Geopolitical Tensions: The US-China Factor Geopolitical developments, especially the enduring US-China tension, will be a critical driver in assessing global economic and financial market performances. The ongoing decoupling between the two economic giants, particularly in the semiconductor industry, presents both challenges and investment opportunities. We foresee increased innovation stemming from this geopolitical divide, providing promising prospects in certain sectors. The AI Revolution: A Long-Term Investment Opportunity The advent of generative artificial intelligence (AI), epitomized by innovations like ChatGPT, has sparked widespread interest in AI-driven technologies across industries. While the global addressable market for AI is still being estimated, we remain optimistic about its long-term growth potential. AI companies in our portfolio have already shown promise, and we continue to explore new investment opportunities in this space as AI applications expand. China's Economic Recovery: Stabilization Efforts China's economic recovery is gaining momentum, though the real estate sector remains a drag. However, recent fiscal and monetary policies have helped stabilize the situation. The Central Economic Work Conference's call for proactive fiscal expansion and real estate policy adjustments are positive signs for the market. China's central bank has also introduced liquidity-boosting measures, such as a 50 basis point reduction in the reserve requirement ratio and lower rates for loans to small firms. We believe these are incremental steps toward further stabilization, and we are optimistic about China's economic and market outlook in 2024. US Presidential Election: Market Implications This year’s US Presidential Election will undoubtedly shape economic policies and market directions, though we refrain from speculating on political outcomes. Instead, our focus remains on the data-driven economic and market trends, with a view that the US economy will increasingly look inward as the election approaches. Overall, we believe Asia, particularly China, remains a bright spot in the global economy, while the US and Europe may face slower growth and recessionary pressures. We remain vigilant in assessing geopolitical risks and continue to focus on sectors like AI and innovation, which offer long-term growth opportunities.
2023 December, Market Outlook: Asia Emerges as a Bright Spot Amid Global Economic Shifts
As 2023 draws to a close, the equity market has remained largely stable, with investors maintaining a preference for developed markets. While Asia Pacific markets have also posted positive returns, their performance still trails behind other regions despite notable improvements in economic data. This disparity is likely due to end-of-year dynamics such as tax-loss harvesting and institutional portfolio adjustments, or "window dressing," a common phenomenon seen during this period. Historically, such short-term volatility tends to carry over into January as fund managers rebalance their portfolios for year-end reporting. In developed markets, equity markets have experienced significant optimism since the Federal Reserve opted to hold interest rates steady for two consecutive meetings. This move has signaled to investors that the Fed's interest rate hike cycle may have peaked, fueling market euphoria. Additionally, concerns about a looming US recession have eased, with many economists now revising their forecasts toward a "soft landing" scenario, where economic activity slows but avoids a severe downturn. However, inflation in the US remains persistently above the Fed's 2% target, indicating that interest rates may stay elevated for an extended period. The future economic outlook remains uncertain, especially as housing inflation cools, but we believe that while the risk of a recession is still moderately high, it is unlikely to escalate into a systemic crisis. On the geopolitical front, China’s recent diplomatic overtures toward the US have been a positive development. Following Chinese President Xi Jinping's visit to the US last month, both nations have expressed a renewed commitment to peaceful cooperation. The resumption of military dialogue, after months of silence, signals China's intention to restore political ties with the US. Additionally, President Xi’s meeting with top US business leaders highlighted strong corporate support for continued engagement with China, despite ongoing geopolitical tensions. For instance, Mastercard's new joint venture with China's national transaction processor, NetsUnion Clearing, demonstrates the long-term business potential between the two countries, allowing Mastercard cardholders to enjoy seamless payments in China. Nevertheless, while these diplomatic efforts are encouraging, further reciprocal actions from the US government will be crucial to reducing geopolitical risks in the long term. With the US presidential elections on the horizon in late 2024, we expect China to remain a central theme in American political discourse, with both parties likely positioning the country as a major national security threat to garner electoral support. This political climate may perpetuate tensions, and as a result, we anticipate that geopolitical risks will remain elevated through 2024. Looking beyond the US, other significant elections, such as Taiwan's, will also play a key role in shaping geopolitical dynamics. As global security concerns intensify, we foresee a gradual restructuring of global supply chains, with capital and business operations increasingly shifting to countries deemed safer or more politically stable. This trend toward economic fragmentation will favor companies capable of maintaining market share and operational efficiency amid the reshoring of industries. In China, the recent Central Economic Work Conference concluded with the government setting a clear pro-growth agenda for 2024. Chinese policymakers are focusing on reviving confidence and stimulating economic growth through a series of supportive measures, including monetary, fiscal, and administrative interventions. These initiatives have been ramping up in intensity, and we anticipate additional measures in the coming months, particularly aimed at addressing risks in the real estate sector. Given these developments, we continue to see Asia, particularly China, as a bright spot for economic growth in the global economy. A lower interest rate environment, coupled with increased liquidity, should help alleviate financial pressures and reduce the debt burdens of companies and individuals. As the world economy navigates through geopolitical tensions and inflationary pressures, Asia remains well-positioned to drive global growth in the near term, making it a focal point for investors looking to capitalize on emerging market opportunities. In summary, while global economic conditions remain uncertain, Asia’s resilience, supported by pro-growth policies and improving economic indicators, offers a compelling investment case, even as geopolitical risks loom on the horizon.
2023 November, Market Outlook: Resilience, Stimulus, and Global Shifts
As we look ahead, the global market outlook remains shaped by several key developments. Despite geopolitical tensions and ongoing conflicts, such as the humanitarian crisis between Israel and Hamas, we expect limited broader economic impact due to stabilizing military presence and containment measures. The risk of a wider regional conflict appears low, preserving global market stability for the time being. US Economic Resilience and Slowdown Expectations In the US, resilience continues to be a dominant theme. While the Federal Reserve’s tightening measures have been in place since 2022, the financial system remains robust, supported by the aftereffects of COVID-19 stimulus and substantial fiscal spending by the US government. This liquidity, however, is expected to taper, with a corresponding economic slowdown projected over the medium term. Current forecasts suggest GDP growth of 0.7% in Q4 2023 and 0.3% in Q1 2024, indicating a likely deceleration in the coming quarters. China’s Recovery Gains Momentum China’s economy has begun to gain notable momentum, driven by improving retail sales, imports, and industrial output. The government has recently announced a significant RMB 1 trillion stimulus package to further bolster the recovery. However, investor sentiment remains cautious, keeping valuations suppressed relative to the US. We believe that this discrepancy is unsustainable and anticipate that over the medium term, valuations in China will close the gap, driven by stronger economic fundamentals. Japan’s Stimulus and Growth Prospects Japan is emerging as an intriguing opportunity as it moves away from years of deflation, with inflation now supported by demand. In response to weakening economic data, the Japanese government has introduced a US$ 110 billion stimulus package aimed at boosting private consumption. This should translate into economic growth in the near-to-medium term, further enhancing Japan’s market potential. Focus on Asia Amid Geopolitical Stability Asia remains our primary focus, especially in light of recent positive developments in China’s economic data and a decrease in US-China geopolitical tensions following the Biden-Xi meeting in San Francisco. Agreements between both countries signal a more stable relationship, reducing trade war fears and enhancing the region’s investment appeal. Overall, we maintain a cautiously optimistic view, focusing on opportunities in Asia while monitoring the evolving macroeconomic landscape.