Insights
Market Outlook1 September 20261 min read

2026 August Market Outlook: Navigating Volatility

2026 August Market Outlook: Navigating Volatility

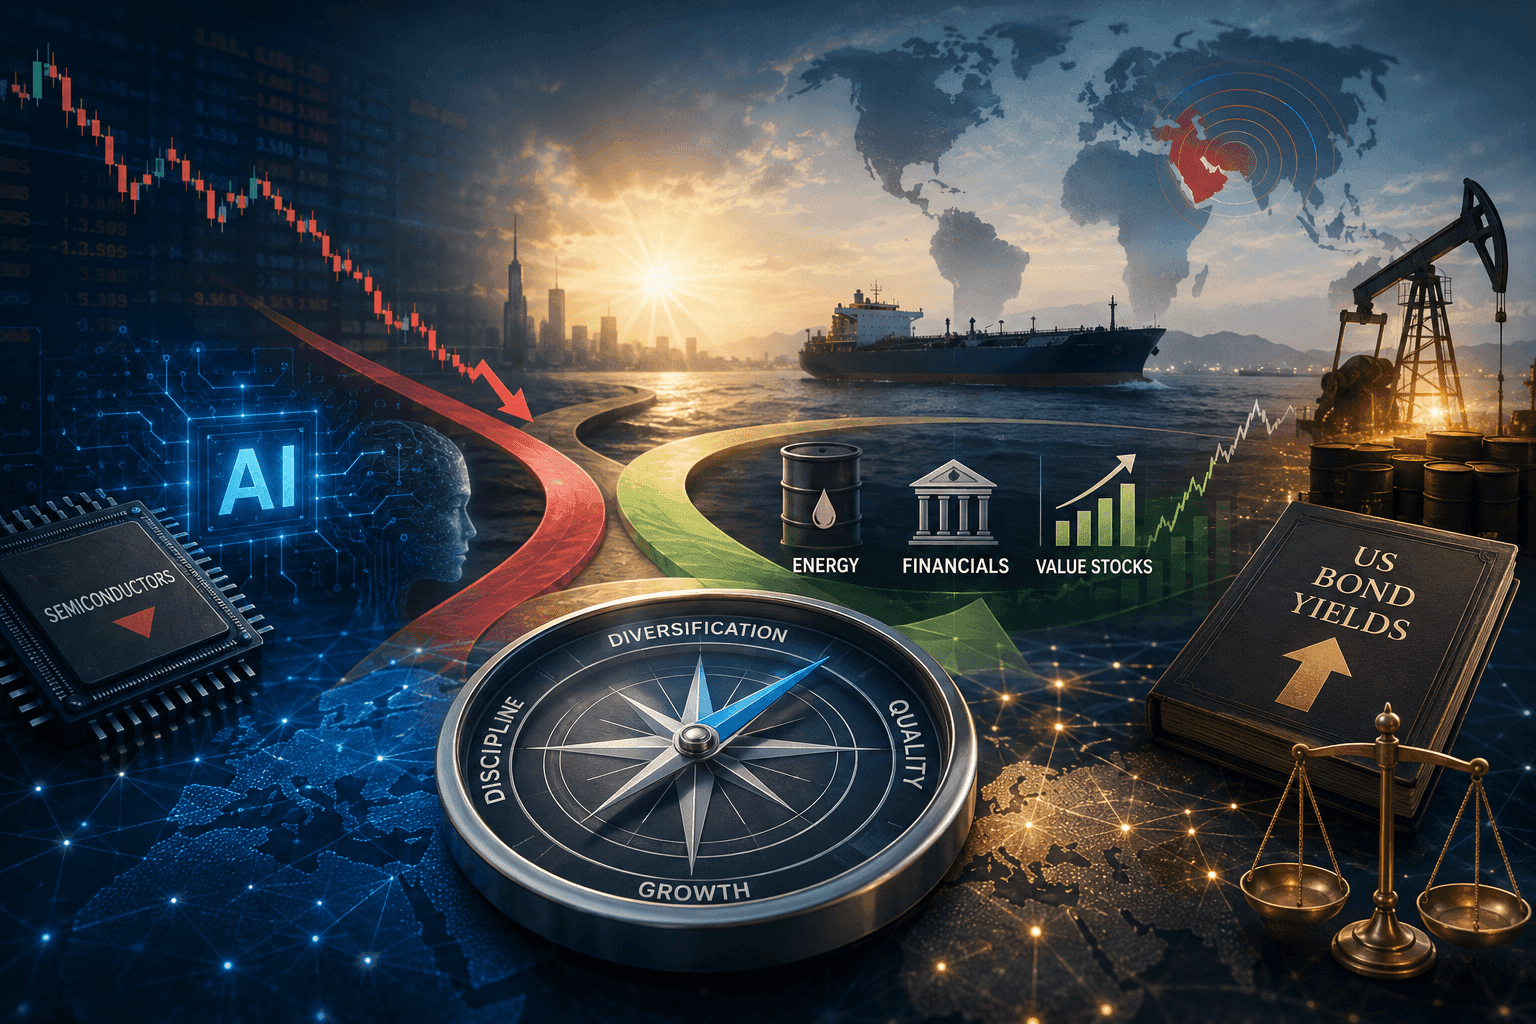
Concerns around the durability of AI-related capital expenditure and intensifying competition triggered a sharp sector sell-off after a mid-July peak. Investor sentiment turned more discerning on the back of earnings season, and questions arose regarding how sustainable the AI investment pace is without eating into cash generation. Capital rotated out of semiconductors and into energy, financials and value stocks, shifting to markets and names seen as less exposed to a single-theme correction.  

Layered on top was renewed Middle East escalation and its effect on rates expectations. Brent crude spiked back above $100/barrel intermittently after the US reinstated a naval blockade on Iran and announced plans to impose a levy on cargo transiting Hormuz, although the levy was never implemented. This revived inflation concerns and caused markets to price a reduced likelihood of further Fed easing. Elevated US bond yields further weighed on stocks.  

Looking ahead, renewed conflict or another AI-related pullback could swiftly unwind recent sentiment gains and force a repricing of both rates and earnings expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.

  • BAMC
Share

More insights

BAMC Asia Equity Fund (BAEF) Performance as of 16 October 2026
Announcement23 October 2026

BAMC Asia Equity Fund (BAEF) Performance as of 16 October 2026

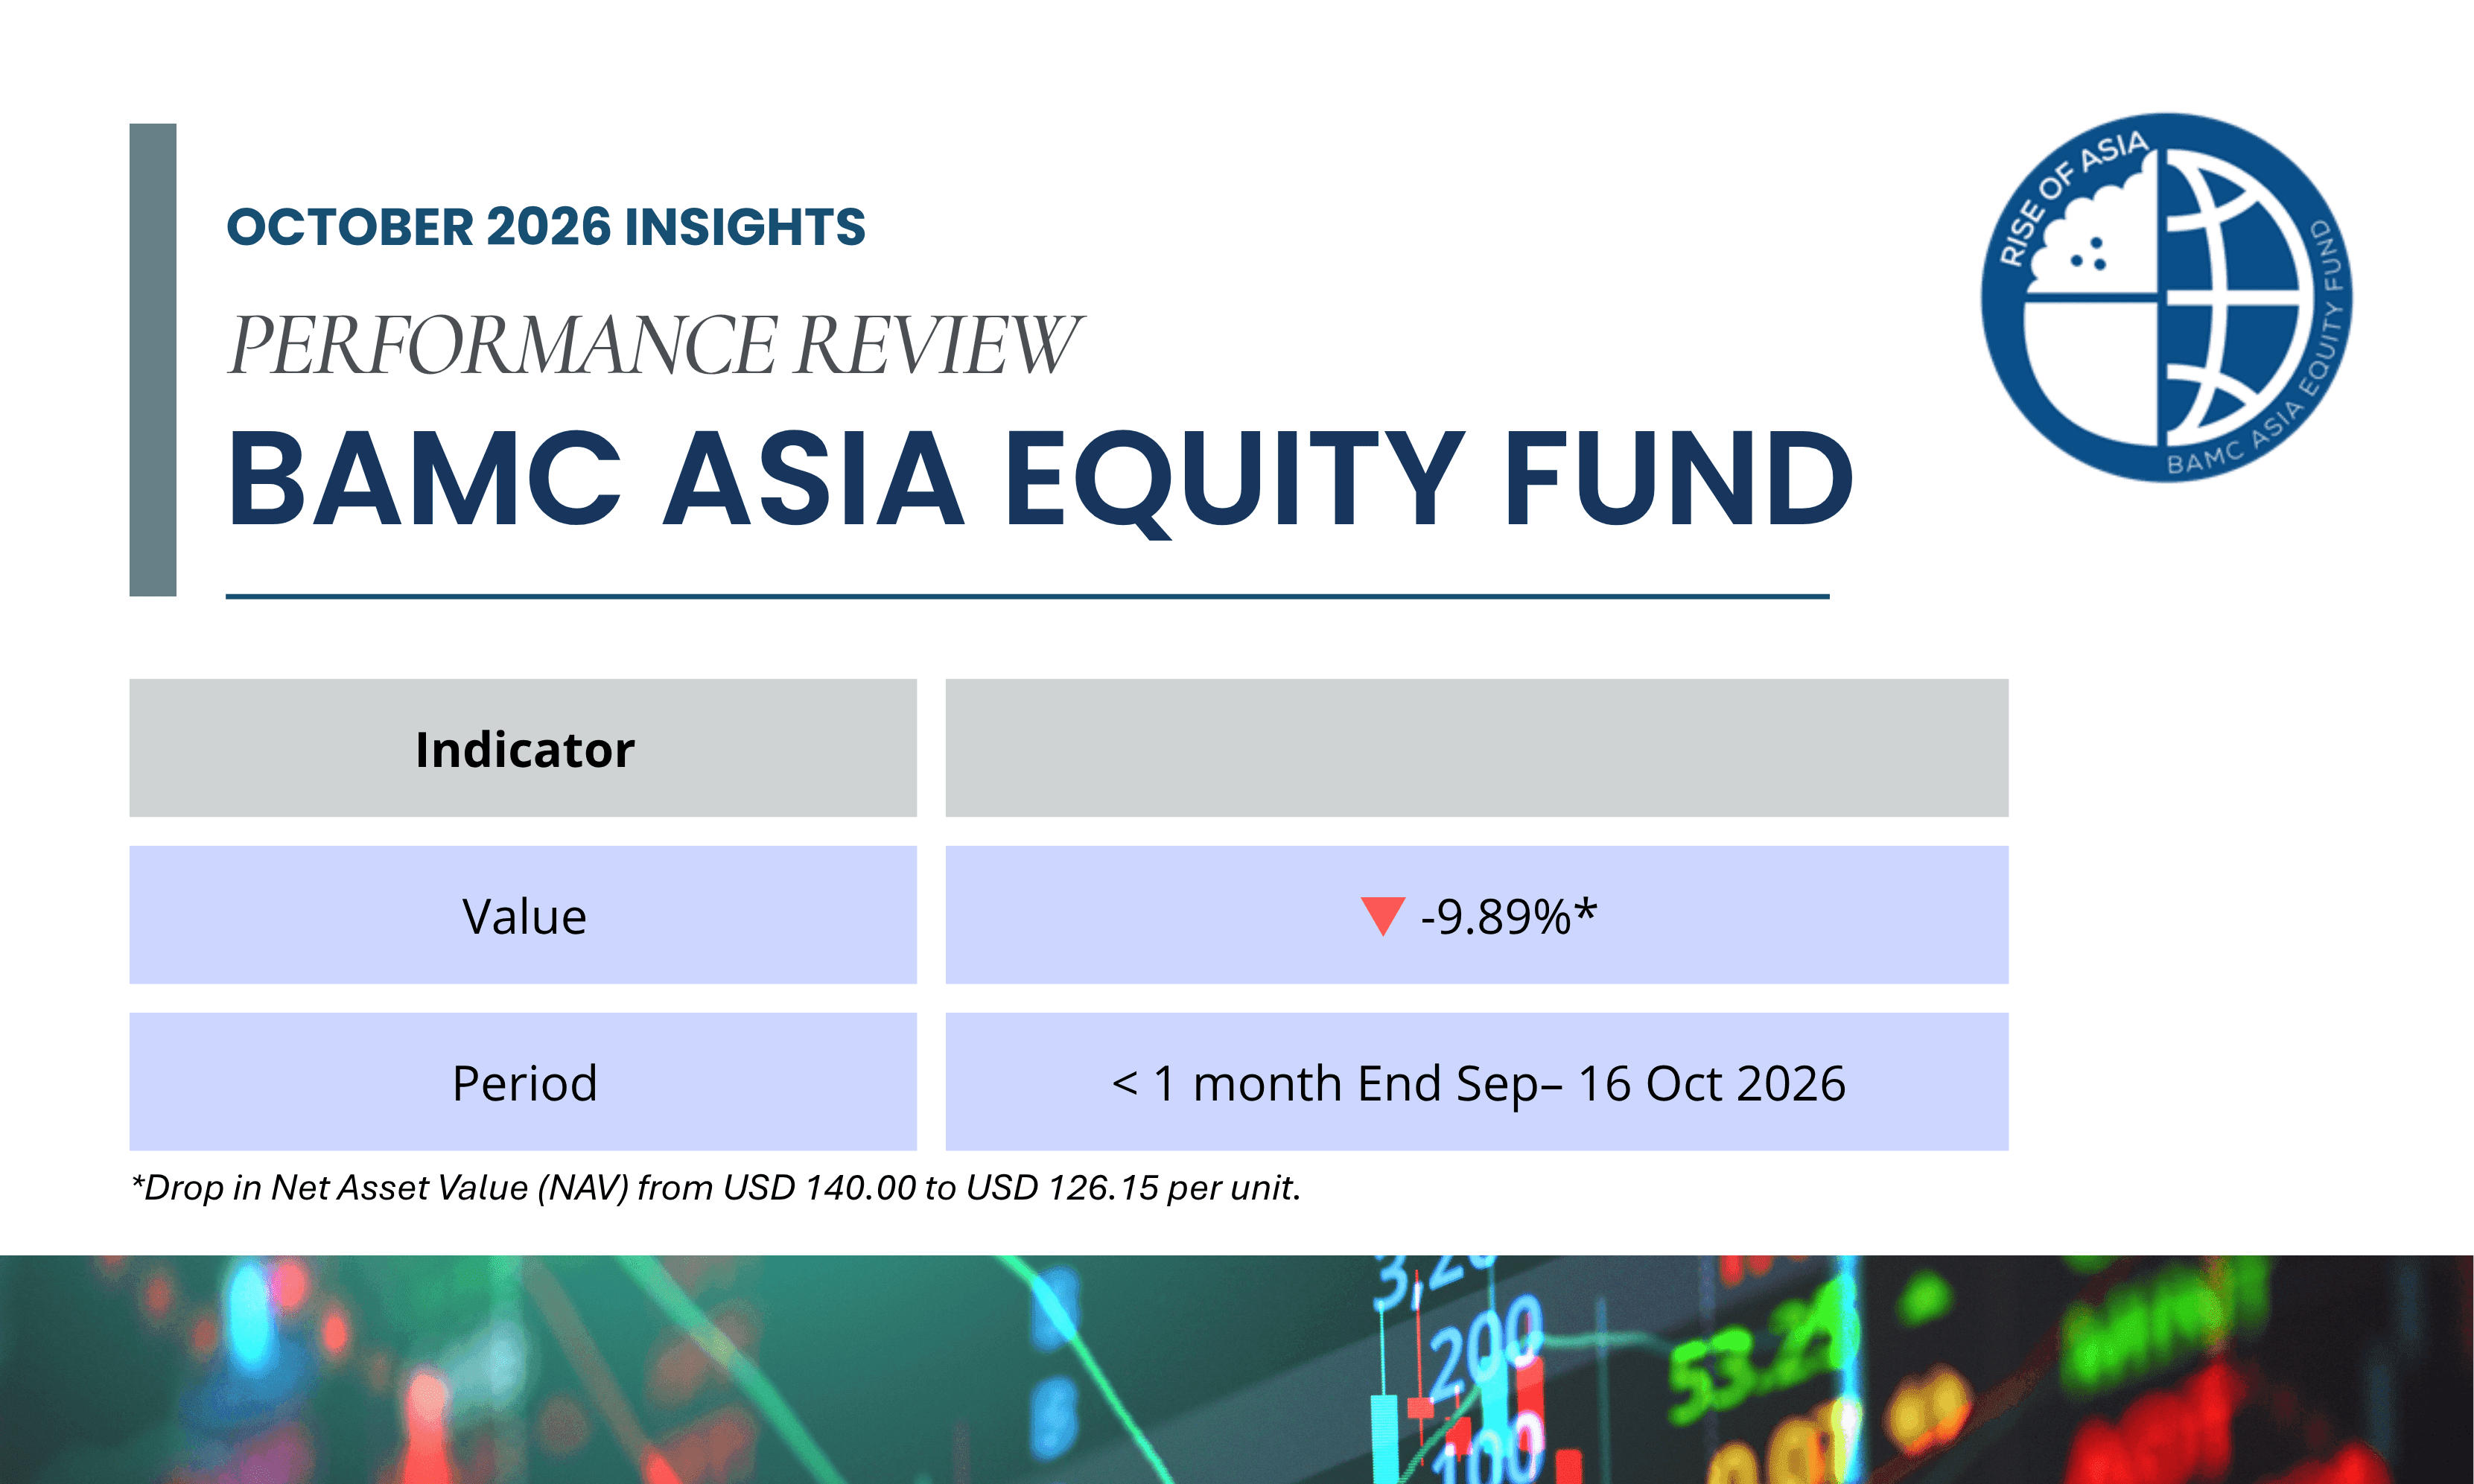
Markets in October Since end September, global equities have faced pressure from higher borrowing costs and growing scrutiny of the returns from AI related spending. Stronger than expected US inflation reinforced expectations of further Federal Reserve tightening, weighing particularly on technology and semiconductor valuations. Elevated oil prices added further pressure on inflation concerns. Overall, technology-heavy Asian markets bore a greater share of the selling in October’s global tech weakness. Our exposure to Asian equities reflects our focus on the region’s long-term growth opportunities. Short-term volatility is an inherent risk of this approach, but our investment decisions remain anchored in companies’ fundamentals and their potential to generate sustainable returns over time. Portfolio underperformance Against this backdrop, BAEF’s main drag was its concentration in Korean and Taiwanese equities and semiconductor related holdings, which together accounted for 32.3% of the portfolio and approximately 4% of the calculated drag. The Korea ETF and Samsung alone contributed roughly 2%. Korea was particularly affected by the unwinding of AI-related positions. On 15 October, its benchmark equity index fell approximately 8%. Samsung’s weakness came despite guidance for a substantial increase in third-quarter operating profit, suggesting that concerns over valuations, financing conditions and competition outweighed the near-term earnings improvement. The drop was compounded by sharp falls in several Singapore small caps and financials. Addvalue fell 22.9%, UOB Kay-Hian 25.2%, OCBC 10.3%. OCBC faced a specific catalyst when Citi downgraded the stock from “neutral” to “sell”, citing risks to third-quarter earnings, pressure on net interest margins from higher deposit costs, and the potential normalisation of exceptionally strong first-half wealth-related income. Addvalue’s share price weakness is due to profit-taking after a strong run. Singapore’s semiconductor-related suppliers to chipmakers fell harder than the larger chipmakers; Frencken fell 14.9%, UMS 14.8% and AEM 9.9%. Together, these holdings constituted approximately 14% of the portfolio and implied another 2.3% of drag. Like the global technology sell-off, broader concerns over the AI investment cycle were weighing on sentiment beyond individual companies’ reported performance. There were few meaningful offsets in the portfolio as gains elsewhere were insufficient to counter the losses. Why we still hold these stocks Despite the recent weakness, we retain these holdings because the underlying earnings drivers remain relevant to our investment horizon. The sell-off has weakened share prices more than the underlying medium- to long-term investment case. In semiconductors, the correction has coincided with continued growth in demand for AI compute. TSMC’s latest results and guidance pointed to sustained demand for advanced chips, while Samsung’s earnings guidance reflected stronger memory sales and pricing. These developments support maintaining exposure to the sector, although we recognise that strong operating performance does not eliminate valuation risk or the possibility of further share price volatility. Our Singapore semiconductor holdings provide exposure to different parts of this investment cycle. UMS benefits from equipment demand and increasing exposure to advanced packaging, AEM offers participation in increasingly complex semiconductor testing, and Frencken provides a more diversified manufacturing exposure. The rationale for retaining these positions rests on their prospective earnings as customers invest in additional capacity and advanced chip architectures, rather than an expectation that all semiconductor-related stocks will recover together. For the financial holdings, recent operating results provide a basis for distinguishing share price weakness from deterioration in the businesses. OCBC’s wealth-management and other non-interest income have helped offset pressure on lending margins, while its capital position continues to support business growth and distributions. UOB Kay Hian reported substantially higher first-half earnings, supported by stronger trading activity, commission income and interest income. We retain exposure to these earnings streams, while recognising that wealth related revenue and brokerage activity are market sensitive and that recent growth rates may not persist. We retain exposure to Addvalue to the long-term growth in satellite connectivity and space infrastructure. Recent share-price weakness appears to reflect, in part, profit-taking following a strong rally, while continued orders support the underlying growth outlook. In september, Addvalue announced US$15 million of new orders across its space connectivity and advanced digital radio business, bringing its order book to US$20.2 million. Converting these orders into earnings and cash flow remains central to our investment case. Overall, we remain selective and view the decline as a potential opportunity to top up positions rather as a reason to hold every position unchanged. Continued ownership must be supported by company fundamentals, an acceptable valuation, and grounded in earnings growth. Moving forward Looking ahead, we intend to increase exposure to quality large-cap and blue-chip companies to strengthen portfolio resilience amid continued volatility. We will prioritise businesses with sound balance sheets, sustainable earnings and cash flows, and durable competitive advantages. Further market weakness could provide opportunities to build positions at more attractive entry prices, while maintaining a disciplined approach to valuation. Disclaimer : This Document is issued for information and investor awareness purposes only to explain the factors contributing to the changes in BAEF’s NAV. It does not constitute investment advice, an investment recommendation, an offer, or a solicitation to buy, sell, or hold units of BAEF. The information provided herein should not be relied upon as the sole basis for any investment decision and does not guarantee future performance. Investors should refer to the Fund’s official offering documents and disclosures and carefully assess their own investment objectives and risk tolerance before making any investment decision.

4 min readRead more
2026 September Market Outlook: Navigating Market Divergence
Market Outlook1 October 2026

2026 September Market Outlook: Navigating Market Divergence

The Fed maintained a restrictive, data-dependent stance through August and subsequently raised the federal funds target range by 25 basis points to 3.75-4.00% citing persistent inflationary pressures. Updated projections point to the possibility of one further increase in 2026. Elevated long-dated US Treasury yields continue to present a valuation risk particularly for growth, technology and AI-related companies, whose expected cash flows lie further in the future. At the same time, continued corporate earnings delivery and investments in strategic technologies along the tech supply chain have so far helped the global economy absorb tighter financial conditions. Strong earnings guidance from major global technology companies supports the view that investment in data centres, advanced chips and supporting infrastructure remains resilient. Within Asia, performance has diverged meaningfully across countries. Singapore remains the region’s defensible market, with strong banking profitability and wealth management inflows attracting investor interest amid global uncertainty. Taiwan and South Korea’s technology sector continues to be major beneficiaries of surging AI-related demand. On the other hand, confidence towards China’s and Indonesia’s growth outlook remains fragile. China’s slow economic momentum is a result of a weak property market and slow domestic consumption, while Indonesia’s commodity price normalisation and concerns over capital outflows weigh on sentiment. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macroeconomic uncertainty.

1 min readRead more
Banjaran AMC and ACLEDA Securities Host Investment Workshop for Forte
Roadshow6 August 2026

Banjaran AMC and ACLEDA Securities Host Investment Workshop for Forte

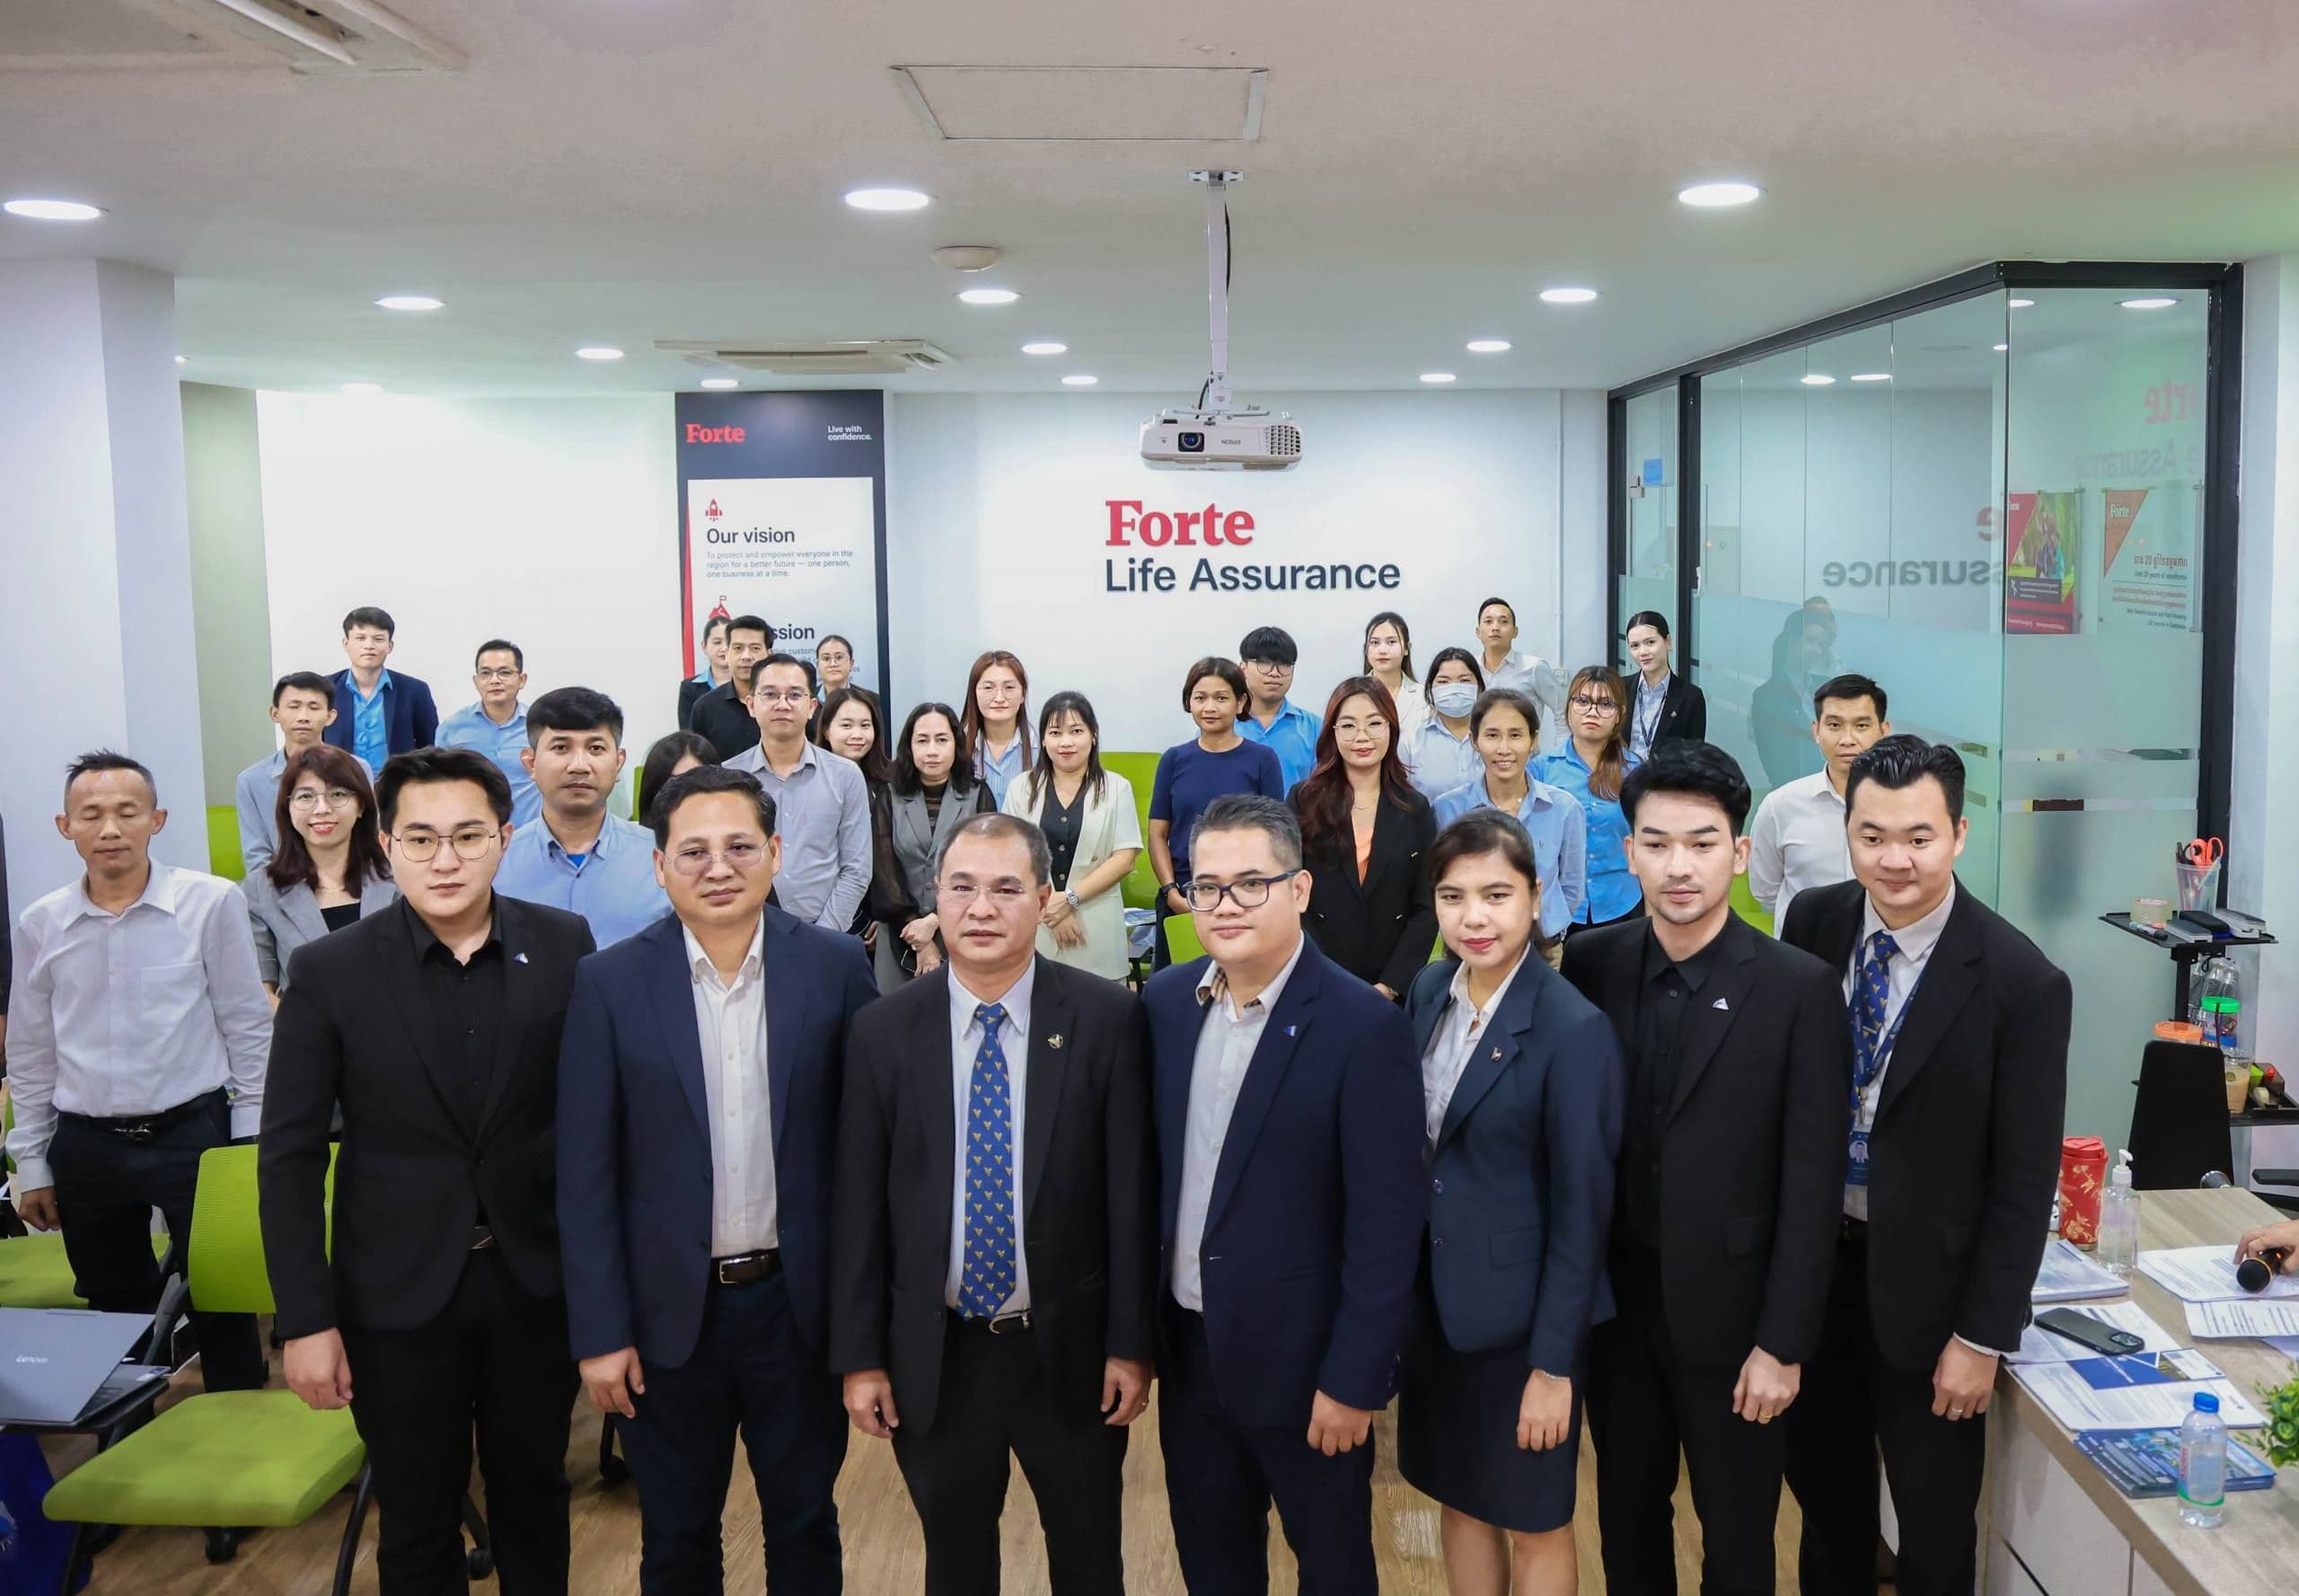
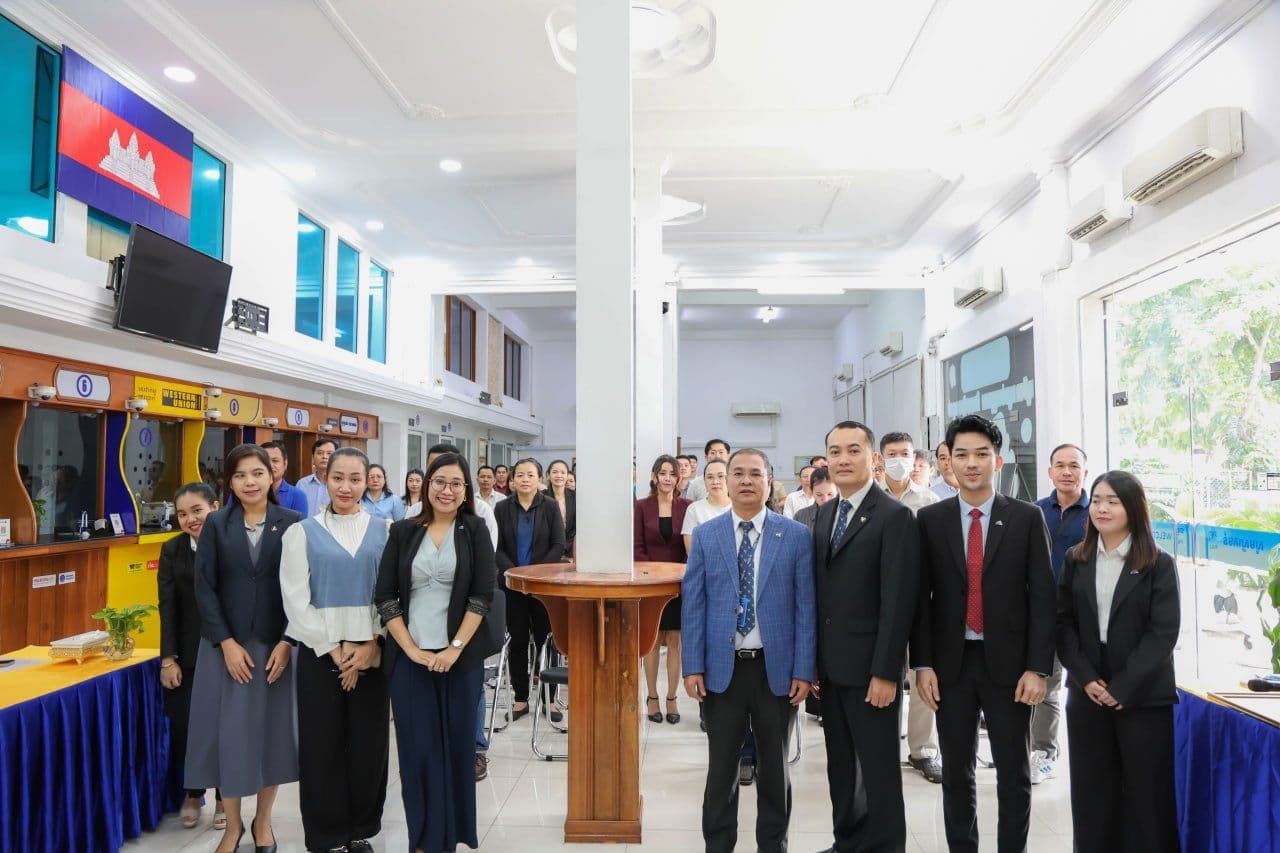
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., successfully organized a workshop on “Golden Investment Opportunities in Securities Sector” for the Management team and staff of Forte General Insurance Plc., and Forte Life Assurance Plc., on 06 August 2026 at Forte Office, One Park Tower. The workshop provided participants with valuable insights into the BAMC Asia Equity Fund (BAEF), including its key features, investment strategy, and the opportunities available through investing in a professionally managed fund licensed by the Securities and Exchange Regulator of Cambodia (SERC). During the session, Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., delivered a presentation on “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”, sharing knowledge on investment opportunities and the benefits of BAEF as part of Cambodia’s growing securities sector. This workshop marks another important milestone under the Strategic Partnership between Banjaran Asset Management (Cambodia) Plc., ACLEDA Securities Plc., Forte General Insurance Plc., and Forte Life Assurance Plc., with the aim of enhancing investment awareness, strengthening collaboration, and creating opportunities for future business growth. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial

1 min readRead more
Banjaran AMC Participates in Trust Forum 2026
News4 August 2026

Banjaran AMC Participates in Trust Forum 2026

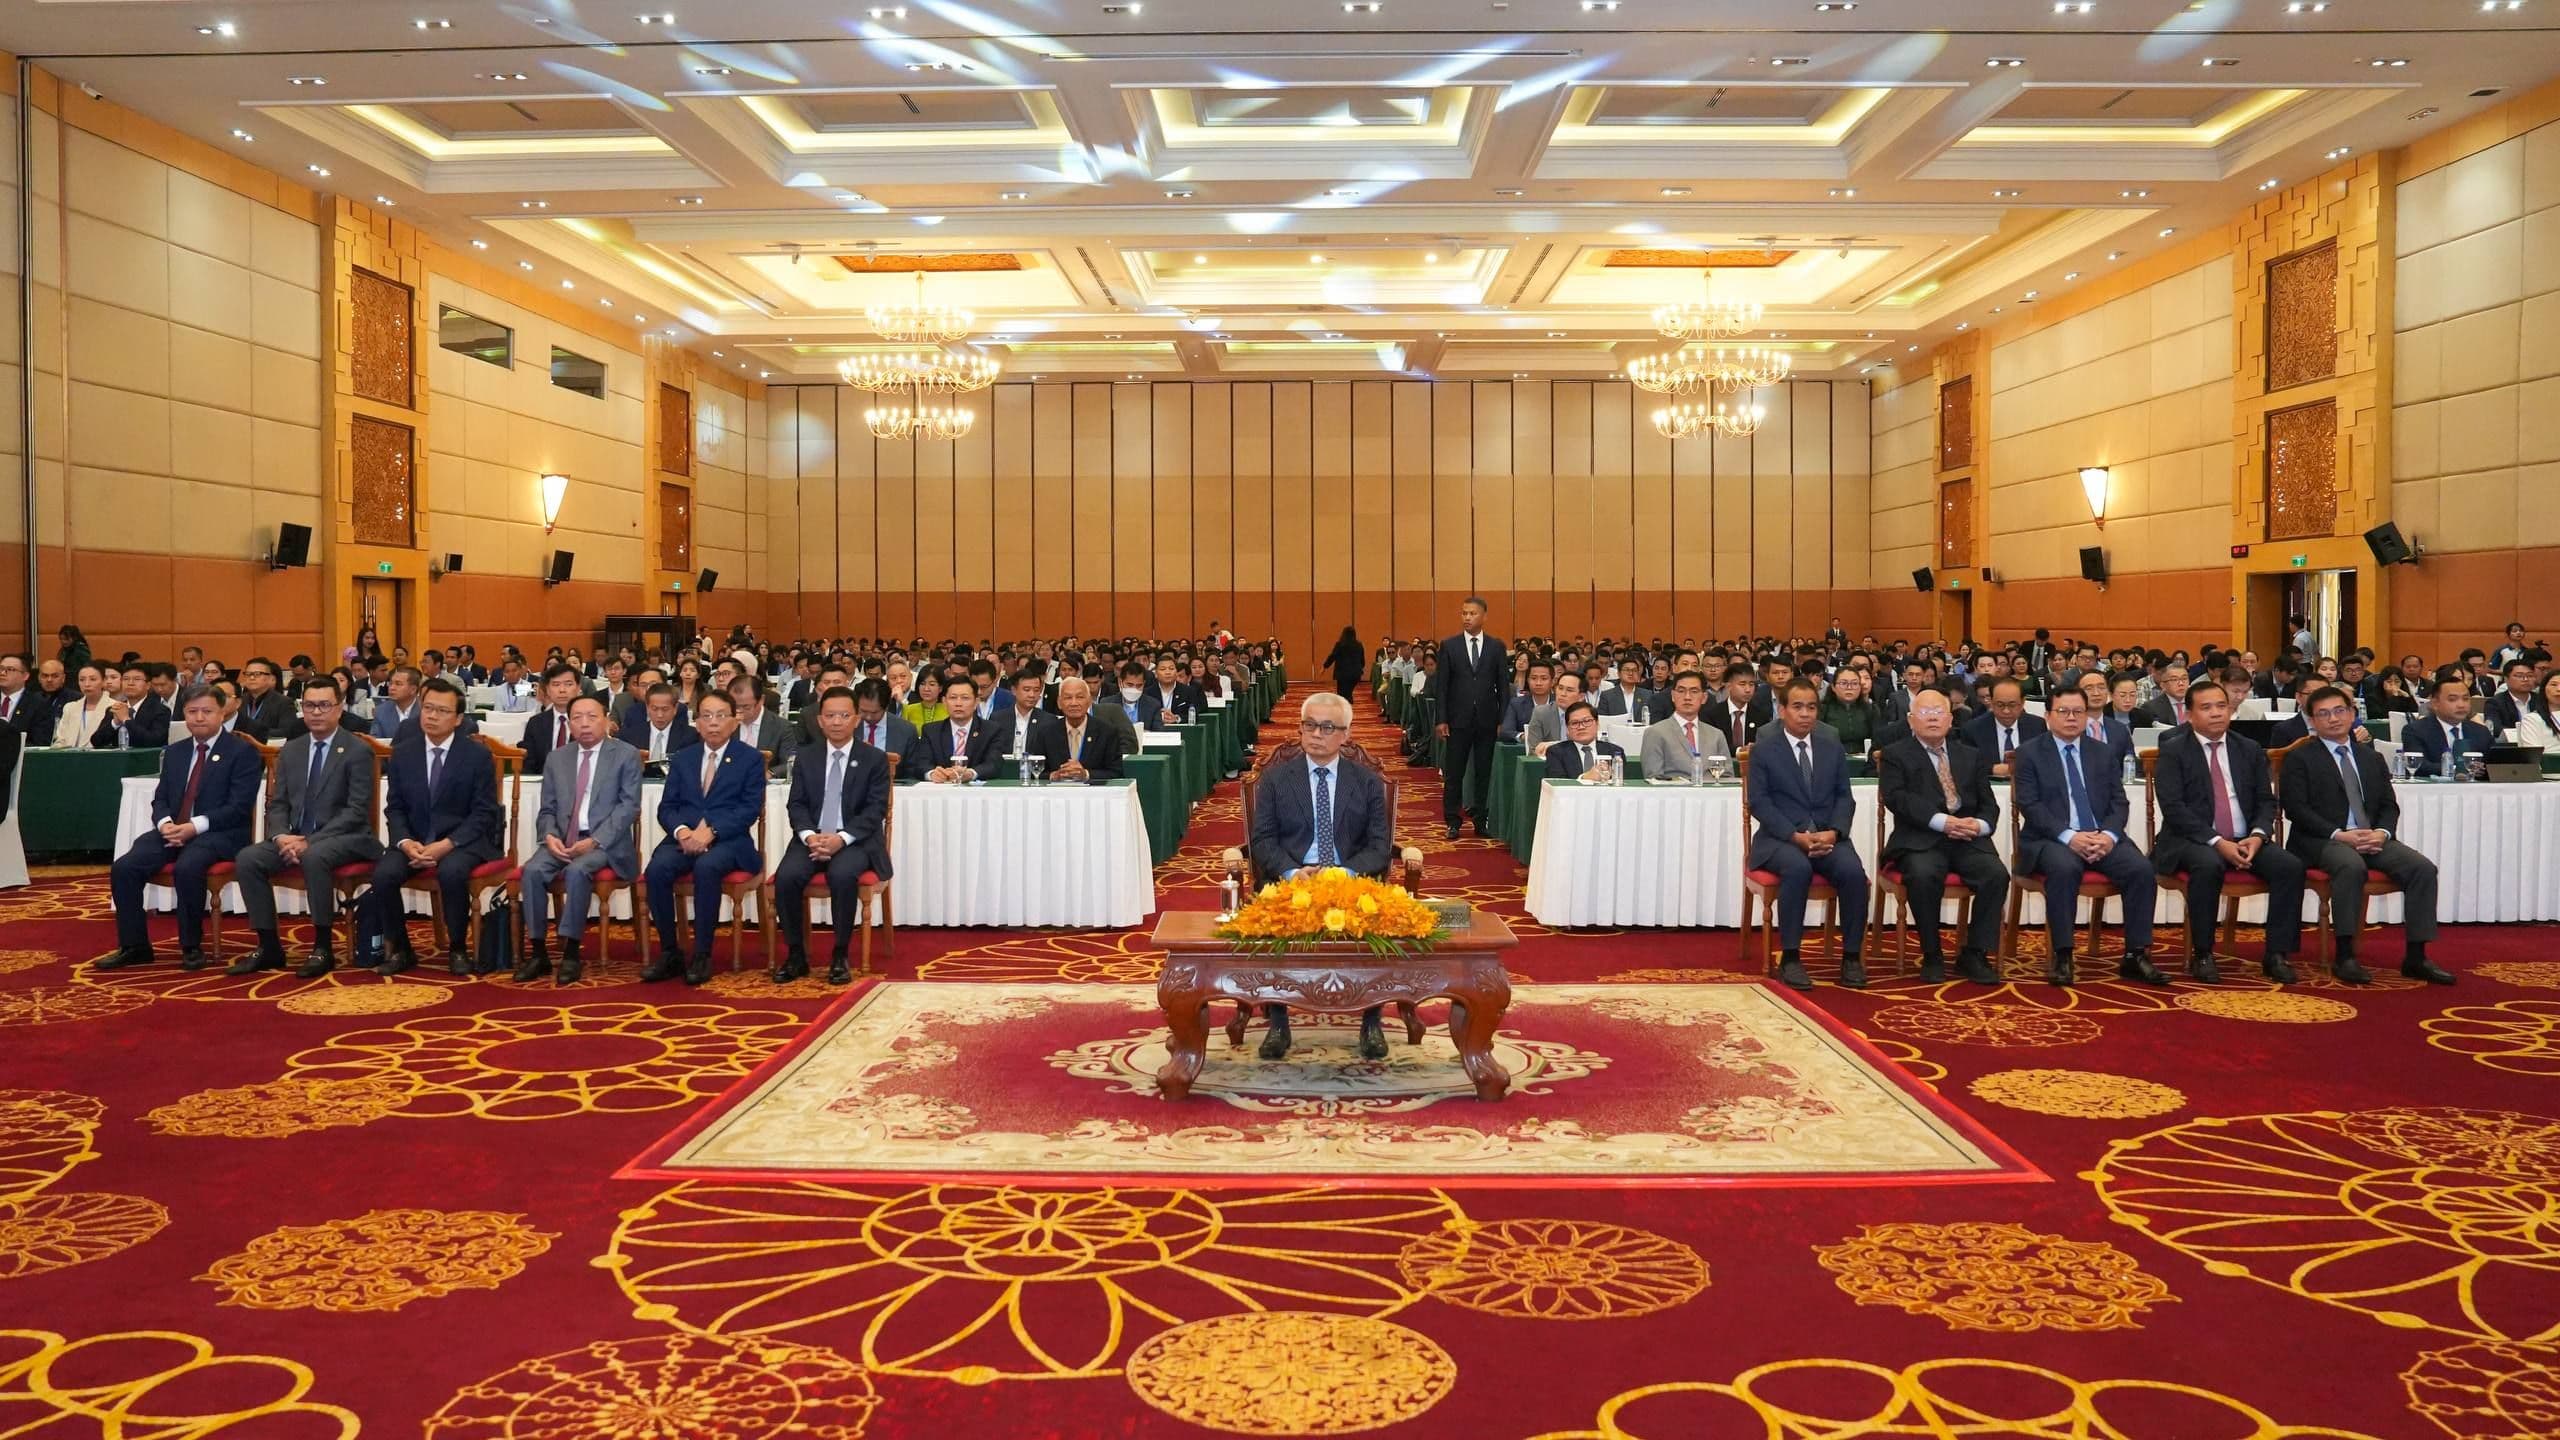
Banjaran Asset Management (Cambodia) Plc. was honored to participate in the “Trust Forum 2026” under the theme “Trust in the Dynamics of Stakeholder System and Achievements over the Past Five Years,” organized by the Trust Regulator (TR) and presided over by H.E. Akka Pundit Sapheacha AUN Pornmoniroth, Deputy Prime Minister, Minister of Economy and Finance, and Chairman of the Non-Bank Financial Services Authority Council, on 4 August 2026 at Sokha Phnom Penh Hotel. The Forum brought together senior government officials, regulators, trust-sector operators, financial institutions, and industry experts to strengthen networks, exchange insights, and shape the future of Cambodia's trust sector. Delivering the welcome address, H.E. SOK Dara, Director General of the Trust Regulator, highlighted five years of remarkable growth in Cambodia's trust sector while reaffirming ongoing efforts to foster a transparent, resilient, and sustainable ecosystem. Representing Banjaran Asset Management (Cambodia) Plc., Mr. Eric Loo, CEO & Executive Director of Banjaran Asset Management (Cambodia) Plc., attended the landmark event. As a licensed fund management company in Cambodia, Banjaran AMC remains committed to working alongside and supporting our Trustee partners, driving collaboration, strengthening market confidence, and supporting the long-term growth of the financial and investment landscape.

1 min readRead more
2026 July Market Outlook: Navigating Crosscurrents
Market Outlook3 August 2026

2026 July Market Outlook: Navigating Crosscurrents

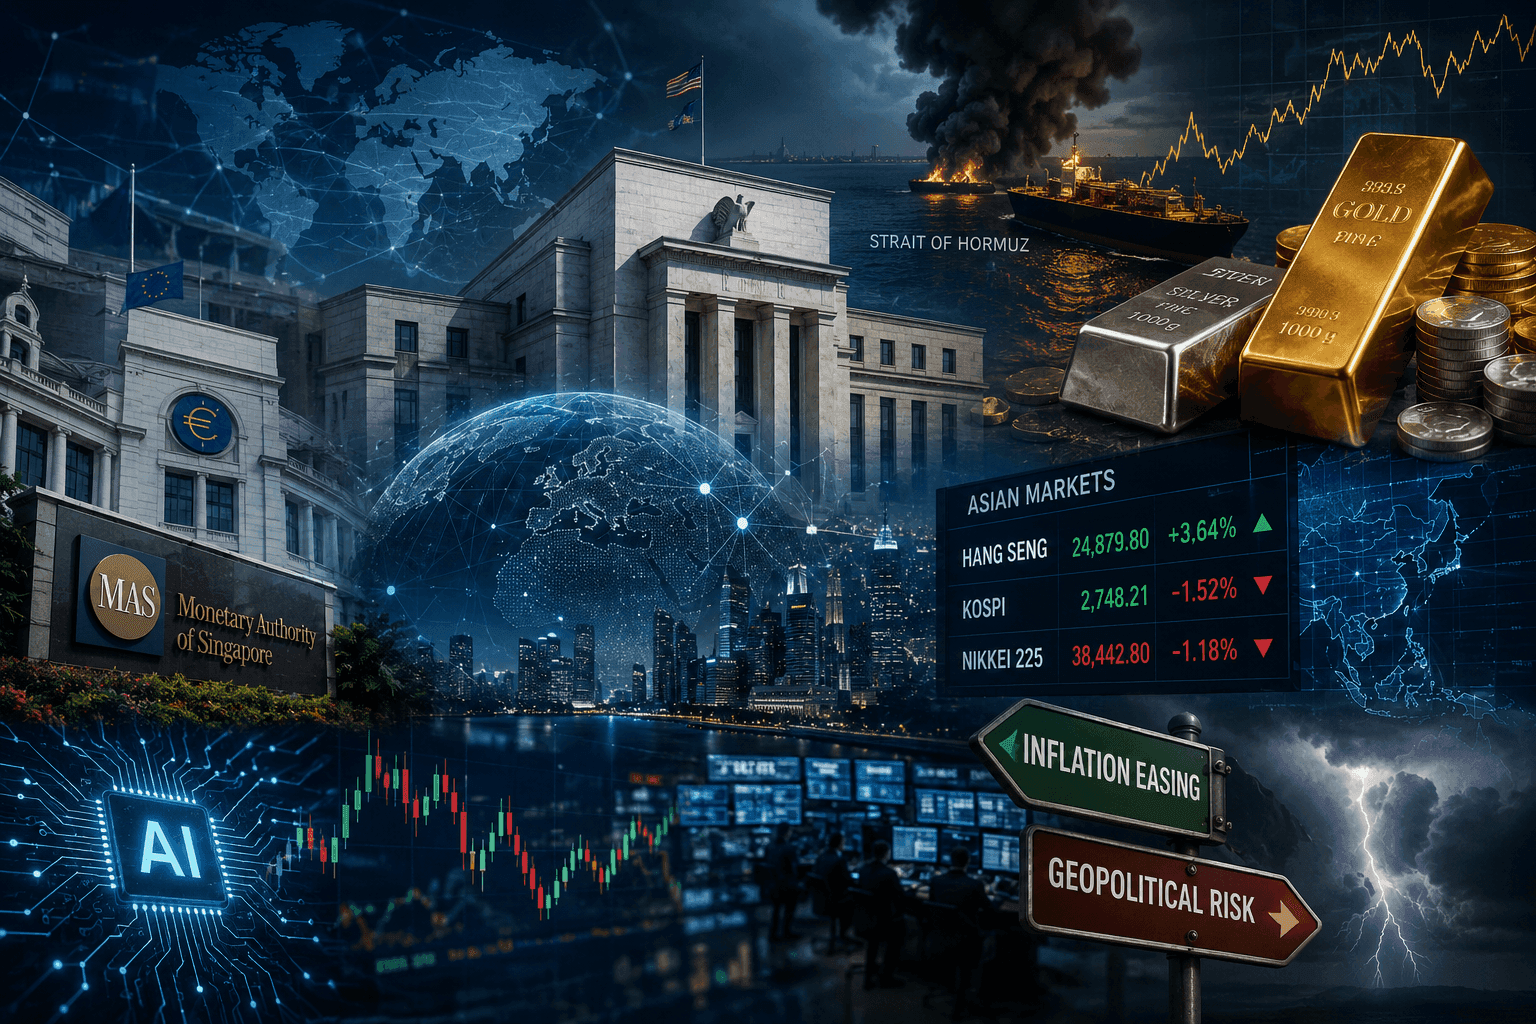
Central banks broadly maintained a data-dependent stance through the period and remained watchful even as global energy-driven inflation eased. The Federal Reserve reaffirmed its commitment to price stability even as growth prospects softened, while the European Central Bank similarly balanced improving headline inflation against still-elevated services prices. Closer to home, the Monetary Authority of Singapore raised its 2026 core inflation forecast on concerns that persistent price pressures could dampen household spending. The Hormuz disruption has driven inflation fears that outweigh traditional safe-haven demand. Gold and silver have moved in an unusual, counterintuitive pattern, falling rather than rallying as fighting escalated. In equities, investor sentiment shifted markedly as the AI-led rally that dominated the first half of the year gave way to a bout of volatility, prompting some rotation into value and cyclicals. Asian equities showed sharp dispersion rather than uniform resilience. In July 2026, Hong Kong’s Hang Seng emerged as the standout performer on continued strength in Chinese technology and AI names, while South Korea’s Kospi and Japan’s Nikkei slipped from June’s rebound as the memory-chip optimism and AI trade cooled. Looking ahead, markets remain caught between two competing narratives, a genuine easing of geopolitical and energy-driven inflation pressure, against the risk of renewed hostilities or a resurgence in AI-related volatility, which could quickly reverse recent gains in sentiment and reprice rate expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.

2 min readRead more
Golden Investment Workshop – ACLEDA Bank Tuol Kouk Branch
Roadshow1 August 2026

Golden Investment Workshop – ACLEDA Bank Tuol Kouk Branch

Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., successfully organized the Workshop on "Golden Investment Opportunities in Securities" as part of the 3rd Round Roadshow at ACLEDA Bank Plc., Local Branch (Khan Tuol Kouk, Sangkat Boeng Kak Ti Muoy), on the morning of 01 August 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., on the topic “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events.

1 min readRead more