

洞察力
获取最新资讯、专家分析及市场展望,抢先洞察行业动态。
新闻中心
集体投资计划投资教育系列(第一篇)
投资于合法合规的投资产品 根据世界银行公布的数据,柬埔寨人均国内生产总值 (GDP) 已从 2010 年的 783 美元增长至 2021 年的 1,625 美元。 Statista.com 进一步预测,柬埔寨人均国内生产总值将持续上升,预计于 2028 年达到约 2,656 美元。随着中等收入群体的不断扩大以及居民整体财富水平的提升,社会对理性投资与财富管理的需求亦随之显著增长。 然而,近年市场上亦出现了大量涉及欺诈、失败甚至明显诈骗性质的投资项目。这凸显了投资者在追求财富增值的同时,更应提高风险意识,谨慎甄别投资产品的合法性与合规性。 在实际投资过程中,投资者往往容易被高回报承诺或熟悉感所吸引,却忽略了投资中最为关键的因素之一 —— 风险。 投资风险的主要类型包括但不限于: 交易对手风险 市场风险 汇率风险 流动性风险 监管风险 特定风险 环境风险 破产风险 运营风险 风险与回报的关系 基于历史数据可以清楚地看到,投资风险与投资回报之间存在直接关系。一般而言,潜在回报越高,所承担的风险也越大。这一关系通常可通过风险 — 回报曲线进行直观展示。 在实际投资中,为了有效控制和缓释风险,投资应尽量选择位于或高于风险 — 回报合理区间的投资机会。更为重要的是,投资者应优先选择合法、受监管的投资产品,以保障自身权益并降低遭受欺诈的可能性。 ❖ 合法合规的投资产品 ( 受监管 ) 在进行投资决策时,投资者应首先判断相关投资计划是否属于受监管投资产品、未受监管投资产品,或存在欺诈风险的非法项目。通常而言,受监管的投资产品须接受国家金融监管机构的严格监管与持续监督,相较其他投资形式,其安全性与透明度更高。 一般情况下,受监管的投资产品通常具备以下特征: 获得监管机构的正式批准或核准 由持牌基金管理人或持牌资产管理机构负责管理 具备完善的法律文件及信息披露机制,并通常由经监管机构认可的审计机构进行审计 基于上述监管框架,受监管投资计划涉及欺诈的风险极低,有助于有效保障投资者权益。 ❖ 柬埔寨集体投资计划市场的最新发展 鉴于集体投资计划市场对经济增长的重要潜力, —— 柬埔寨证券交易监管机构,作为负责监管、监督及推动柬埔寨证券市场发展的唯一监管机构,已通过颁布相关法规,逐步建立并完善该市场的制度基础与基础设施。 为推动集体投资计划市场的发展,柬埔寨证券交易监管机构于 2018 年 5 月 29 日正式颁布《集体投资计划业务许可与监管条例》,允许符合条件的机构向柬埔寨证券交易监管机构申请许可或批准,从事集体投资计划相关业务。 截至 2023 年第三季度( Q3 2023 ),柬埔寨证券交易监管机构已向以下机构颁发相关牌照或批准: 16 家基金管理公司 8 家受托机构 5 家基金分销机构 3 家基金行政管理机构 此外,柬埔寨证券交易监管机构于 2023 年 7 月 20 日进一步颁布《集合投资计划基金单位发行条例》。该法规明确了基金单位发行的条件与要求,以及发行后的持续运营与监管安排,以确保市场运作的有序性、问责性与透明度,并最重要地,全面保护包括投资者在内的所有市场参与者的合法权益。 ❖ 未受监管的投资产品 未受监管的投资计划通常由一般经营性公司运作,往往以高回报承诺吸引投资者,其监管仅限于基本的公司法层面,不受金融监管机构的实质性监督。在实践中,未受监管投资计划与投资诈骗项目往往难以清晰区分。 此类投资计划通常具有以下特征: 承诺异常高的投资回报 (往往“好得令人难以置信”,实际隐含极高风险) 文件与信息披露不足 (未充分披露潜在风险及隐性费用) 由规模极小的团队管理 (管理层背景往往被夸大或缺乏可核实性) 缺乏独立第三方验证机制 (未经过审计,所有关键流程由单一公司自行完成) 最重要的是,缺乏监管机构的合法性监督,投资计划的合规性无法得到保障 ❖ 投资诈骗或欺诈性投资计划 以下为近年来在柬埔寨发生的部分未受监管投资计划失败或涉嫌欺诈的案例: 2019 年国际外汇交易(International Forex Trading) 案件 该计划由少数个人运作,并向投资者承诺极高回报。项目缺乏必要的制衡机制,相关公司既负责资金投资决策,又负责向投资者发放支票。在缺乏独立第三方监督的情况下,此类未受监管机构容易作出虚假或夸大的投资承诺。 2017 年 Empire Big Capital Limited 与 Investment Consultant Association 案件 该投资计划同样由小型团队运作,并承诺每月高达 10% 的回报率。与上述案例类似,该项目缺乏基本的内控与监督机制,所有投资及资金运作均在公司内部完成,透明度极低。 涉嫌欺诈的土地投资计划案例 市场上亦曾出现多起土地投资项目失败并被指控涉嫌欺诈的情况。部分相关经营者已被逮捕、起诉,甚至判刑。此类土地投资项目普遍承诺高回报,但在资金使用方式、项目进展及现金流状况方面严重缺乏透明度。 ❖ 投资失败与投资诈骗的区别 需要特别强调的是,投资项目表现不佳与投资诈骗之间存在本质区别。 所有投资活动均伴随一定风险,市场环境变化、经济周期波动等因素,均可能导致合法投资项目出现亏损。 投资诈骗则发生在经营者根本无意将募集资金投入所宣称的投资项目之情况下,而是通过利用新投资者的资金向早期投资者支付所谓 “ 收益 ” 来制造盈利假象,此类行为被称为 “ 庞氏骗局 (Ponzi Scheme)” 。 所有诈骗项目均未经监管机构批准,不具备合法性。 ❖ 结论 在选择合法合规的投资产品时,投资者应重点考虑以下因素: 该公司是否受相关监管机构监管? 该投资产品是否获得相关监管机构的批准? 所承诺的回报率是否与其风险水平相匹配,是否具备合理性? 集合投资计划是否具备基本的制衡机制,例如独立的法律顾问、审计机构及其他专业服务机构? 最后,相信您的理性判断。 如果某项投资听起来“好得不真实”,投资者应保持谨慎,进行更深入的调查,并提出更多关键问题。在选择符合自身风险承受能力的合法投资时,合理的投资应有助于分散风险,并在长期内实现稳健的财富增长。 本文内容摘编自 柬埔寨证券交易监管机构 (SERC) 相关文章。
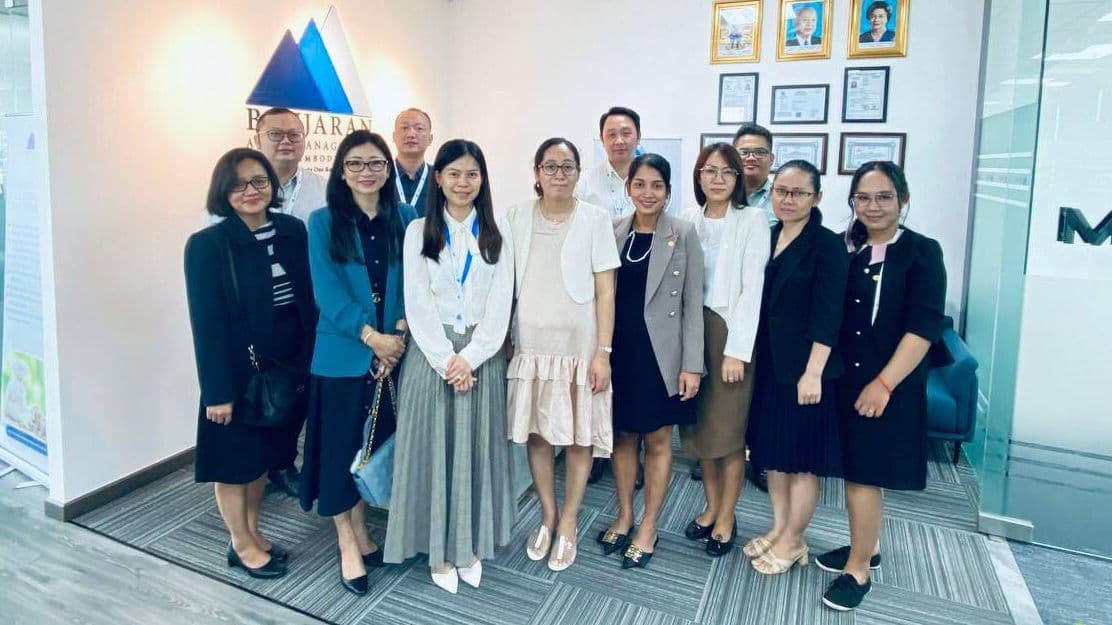
富亚资产管理向柬埔寨证券交易监管机构提交富亚亚洲股票基金申请集体投资计划基金单位发行批准
柬埔寨 · 金边 —— 富亚资产管理 ( 柬埔寨 ) 有限公司近日正式向柬埔寨证券交易监管机构提交富亚亚洲股票基金的基金单位公开发行审批申请。该申请依据柬埔寨 ** 集体投资计划 ** 监管框架提交,充分体现公司致力于为区域市场提供稳健、合规投资产品的承诺。 本次申请材料由柬埔寨证券交易监管机构——证券发行司司长 Thay Sokphalline 女士阁下 率领相关官员团队进行审查与检视。此次全面而严谨的监管审阅,标志着 富亚亚洲股票基金 在审批进程中迈出关键一步。该基金旨在拓宽投资者参与多元化股票投资组合的渠道,以满足亚洲股票投资解决方案日益增长的市场需求。 富亚亚洲股票基金 代表着柬埔寨资本市场发展的开创性尝试。富亚资产管理 ( 柬埔寨 ) 有限公司对该基金的市场前景充满信心,认为该产品有望吸引本地及国际投资者参与,为国家经济增长注入新动能。基金将重点布局亚洲地区具高增长潜力的行业与企业,力求在审慎风险管理的前提下,为投资者创造中长期稳健回报,并进一步提升柬埔寨在全球金融市场中的地位。 富亚资产管理 ( 柬埔寨 ) 有限公司将持续与监管机构保持紧密合作,确保全面遵循所有法律及金融监管要求。在获得最终批准后,富亚亚洲股票基金有望成为柬埔寨市场首批此类产品之一,为国家金融体系发展树立重要里程碑。 有关该基金的进一步进展及官方信息,敬请关注富亚资产管理 ( 柬埔寨 ) 有限公司及柬埔寨证券交易监管机构后续发布的正式公告
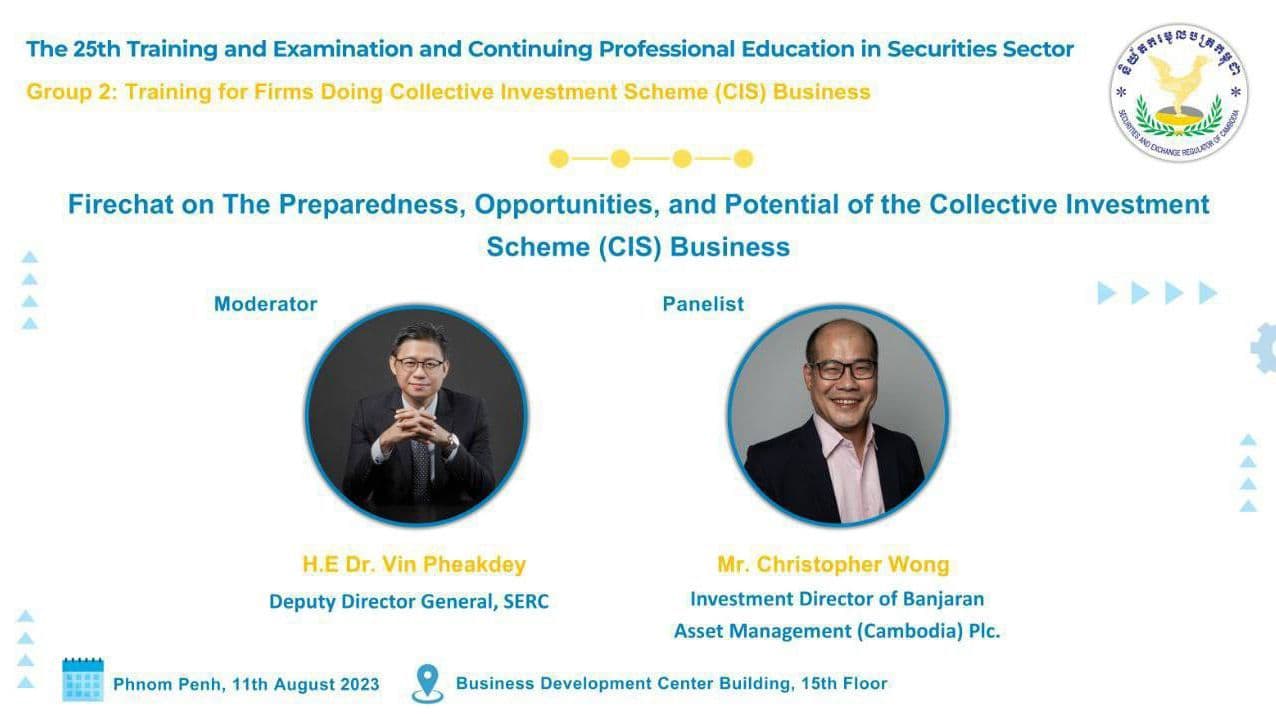
“集体投资计划 (CIS) 业务的准备度、机遇与发展潜力”专题炉边对话
柬埔寨 · 金边 —— 富亚资产管理 ( 柬埔寨 ) 有限公司 投资总监 Christopher Wong 先生 受邀参与题为 “ 集体投资计划业务的准备度、机遇与发展潜力 ” 的专题炉边对话 (Fireside Chat) 。本次活动由柬埔寨证券交易监管机构副总干事 Vin Pheakdey 博士阁下担任主持。 讨论围绕柬埔寨集体投资计划市场的最新发展态势展开,重点探讨了监管体系的完善程度、市场准备情况,以及通过集合投资工具推动经济增长的潜力。 Wong 先生结合其专业经验,深入分享了集体投资计划为本地及国际投资者所带来的机遇,并强调其在提升资本市场可及性、促进金融包容性方面所发挥的重要作用。 本次对话亦为行业参与者提供了一个高层次的交流平台,就投资领域所面临的挑战与机遇展开深入探讨。 Wong 先生的专业见解,有助于加深业界对如何有效运用集合投资计划以强化柬埔寨金融市场体系的理解。 随着柬埔寨资本市场的持续发展,此类高层次对话对于促进监管机构、投资者及行业领导者之间的协作至关重要。富亚资产管理 ( 柬埔寨 ) 有限公司将持续积极参与相关行业倡议,致力于推动健康稳健的投资环境建设,并助力国家金融服务业的长期发展。
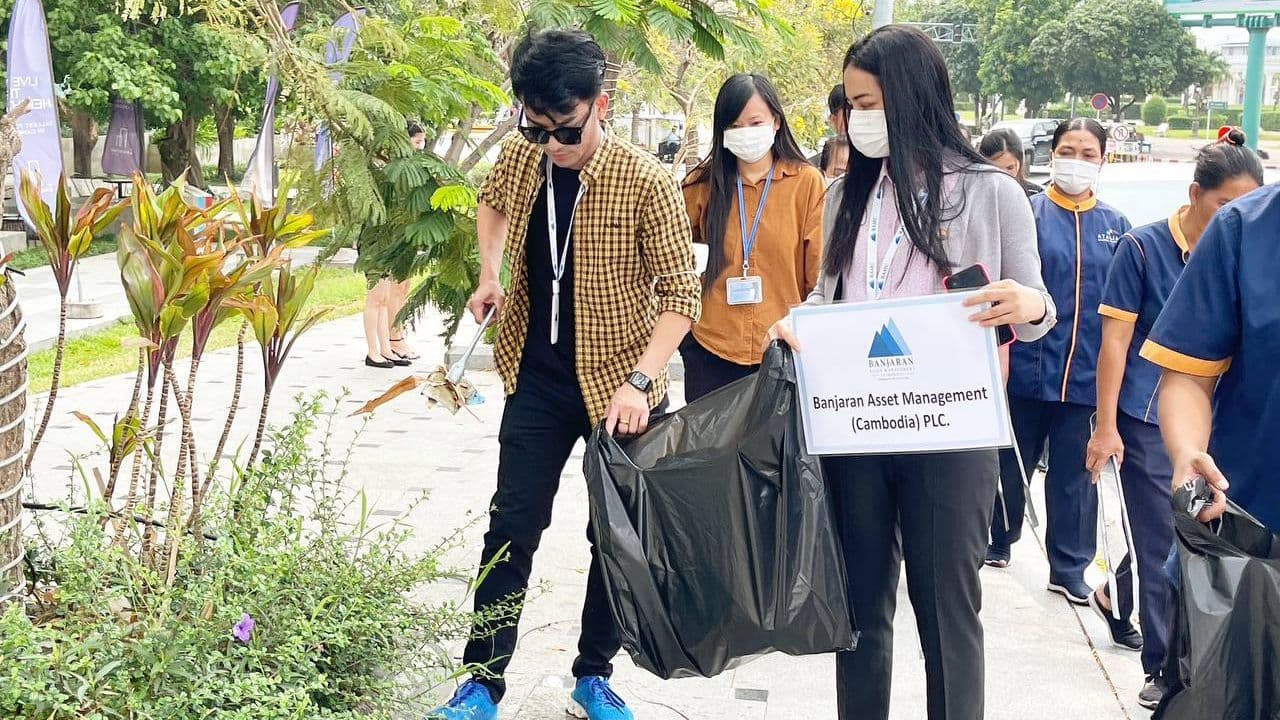
富亚资产管理 (柬埔寨) 参与绿色清洁行动
柬埔寨 · 金边 · 钻石岛 —— 富亚资产管理 ( 柬埔寨 ) 有限公司近日自豪地参与了在钻石岛举行的绿色清洁行动,进一步彰显公司对环境保护与可持续发展的坚定承诺。 本次活动旨在提升公众对维护清洁、绿色公共空间重要性的认知,并鼓励社区积极参与各类环保行动。活动期间,富亚资产管理 ( 柬埔寨 ) 的员工与当地志愿者及社区居民携手合作,开展了包括垃圾清理及环保意识宣导在内的多项实践活动。 此次亲身参与不仅为钻石岛的环境美化作出了积极贡献,也有效向参与者传达了环境保护责任意识,强调了为子孙后代保护自然资源的重要性。 富亚资产管理 ( 柬埔寨 ) 有限公司董事总经理 Ben Lee 先生表示: “ 我们认为,企业责任不仅体现在财务表现上,更体现在对环境的积极守护。通过参与此类活动,我们希望能够激励更多企业共同为建设一个更加清洁、绿色的柬埔寨贡献力量。 ” 本次绿色清洁行动汇聚了多家机构及地方政府代表,充分展现了集体行动在推动可持续发展方面的重要性。富亚资产管理 ( 柬埔寨 ) 的参与,不仅体现了其在金融服务领域的专业追求,也反映了公司在推动环保意识与社会责任方面的长期承诺。 作为企业社会责任战略的重要组成部分,富亚资产管理 ( 柬埔寨 ) 未来将持续参与有利于社区发展与环境保护的相关活动,进一步巩固其作为柬埔寨金融行业负责任企业典范的形象。
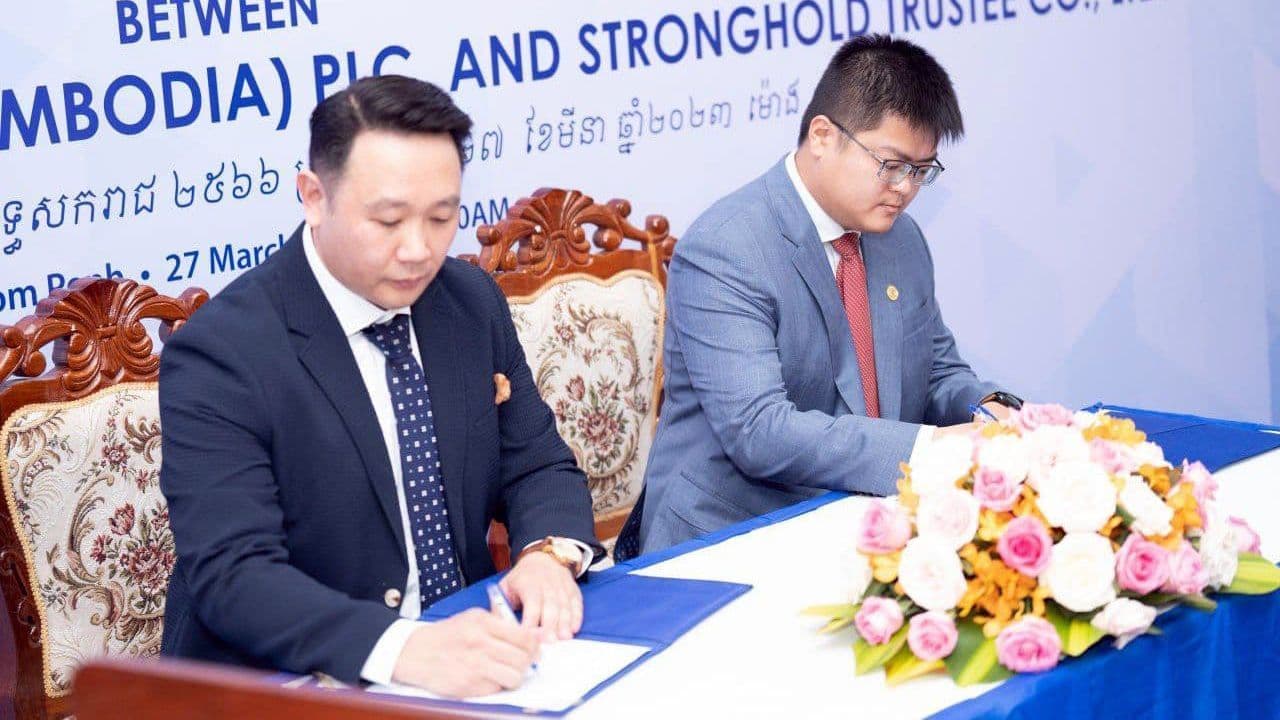
富亚资产管理 (柬埔寨) 有限公司与 碉堡信托有限公司携手合作共同推出市场领先的公募投资基金
金边,柬埔寨 —— 富亚资产管理 ( 柬埔寨 ) 有限公司与 碉堡信托有限公司近日举行了隆重的签约仪式,正式确立双方在推出柬埔寨首只公募基金及集体投资计划方面的合作关系。该仪式由柬埔寨证券交易监管机构 (SERC) 总干事 Sou Socheat 阁下亲自主持,并有多位监管机构官员出席见证。 在获得柬埔寨证券交易监管机构最终批准后,此项合作将成为柬埔寨金融服务行业的重要里程碑,为零售投资者提供除传统银行存款之外的全新投资选择。该基金将由富亚资产管理 ( 柬埔寨 ) 有限公司担任基金管理人,碉堡信托有限公司 出任受托人,而新加坡富亚资产管理私人有限公司则担任投资顾问。 此次合作将使柬埔寨投资者无需前往香港或新加坡等国际金融中心,即可参与全球资本市场投资。碉堡首席执行官 Hans Chen 先生表示,对基金的推出充满信心,并强调 碉堡将以高度的专业性与丰富的受托管理经验支持该项目。富亚资产管理 ( 柬埔寨 ) 董事总经理 Ben Lee 先生则指出,本基金引入了国际标准的基金管理制度,并为本地基金管理生态系统中的专业人才提供系统化培训。 富亚资产管理 ( 柬埔寨 ) 成立于 2022 年,持有由柬埔寨证券交易监管机构颁发的基金管理牌照,由 Banjaran Holdings Pte Ltd (新加坡)、 Best Magnet Capital Co., Ltd 及 Primo Plus Co., Ltd 共同合资设立。 碉堡信托有限公司是依据《柬埔寨信托法》设立并获全面牌照的首家受托机构,专注于为客户提供量身定制的信托服务解决方案。 此外,新加坡富亚资产管理私人有限公司 (BAMPL) 目前管理资产规模约 50 亿美元,在多元资产类别的投资管理领域拥有深厚经验,进一步巩固了本次基金项目的专业基础。 该公募投资基金的推出,标志着柬埔寨资本市场发展的关键一步,不仅为本地投资者提供了新的财富增长渠道,也为未来金融行业的持续创新与深化奠定了坚实基础。 More News Cambodia Investment Review Securities and Exchange Regulator of Cambodia Trust Regulator
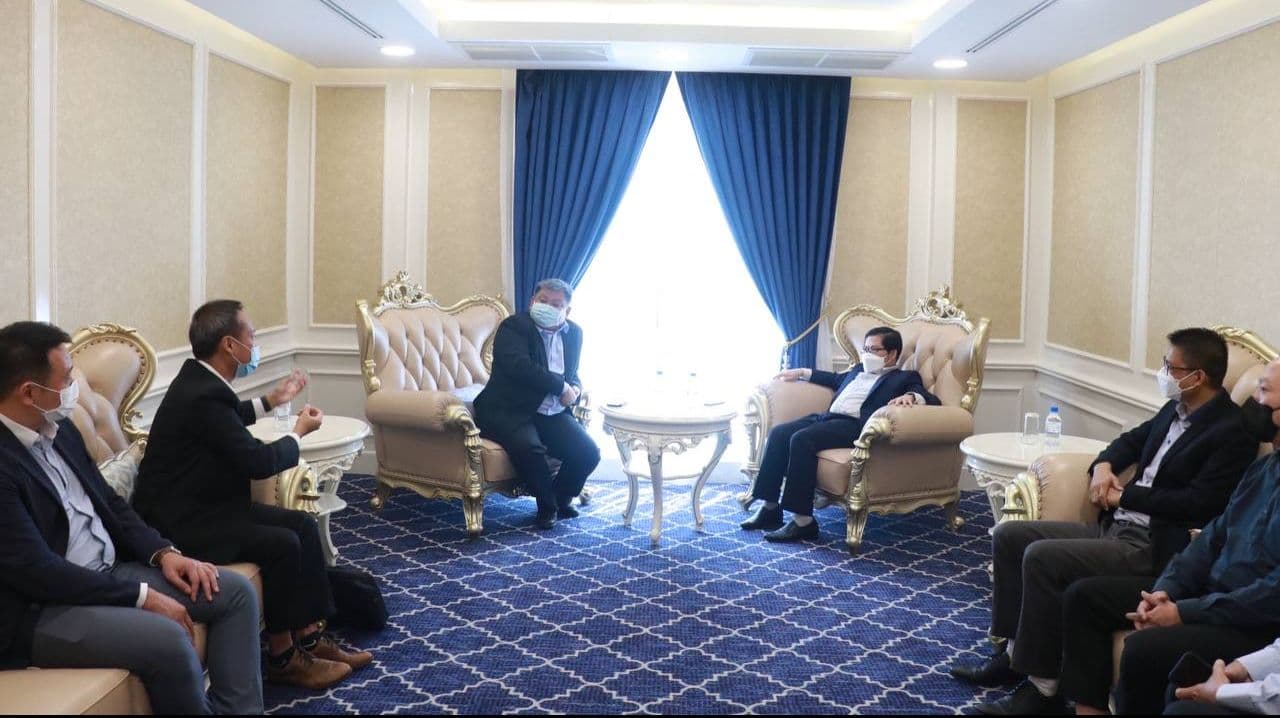
柬埔寨证券交易监管机构 欢迎新加坡富亚资产管理私人有限公司就柬埔寨证券市场进行战略会谈
2022 年 5 月 4 日,金边 为进一步推动柬埔寨资本市场的成长与现代化,柬埔寨证券交易监管机构 (SERC) 总干事、皇家政府代表 Sou Socheat 阁下 ,携同柬埔寨证券交易监管机构 副总干事 Vin Pheakdey 博士阁下 ,于 2022 年 5 月 4 日正式会见了来自新加坡的资产管理公司 富亚资产管理私人有限公司 (BAMPL) 高管团队。访问代表团由富亚资产管理私人有限公司首席执行官 Aaron Ng 先生 与 执行董事 Low Hon-Yu Low 先生 率领。 此次会晤为双方就柬埔寨证券市场的战略合作及潜在商业机会提供了重要平台。 Sou Socheat 阁下 详细介绍了柬埔寨资本市场的监管框架、投资环境及机构基础设施,并强调政府正在进行的改革举措旨在提升市场透明度、保护投资者权益,并确保国际合规,从而使柬埔寨成为具有吸引力的新兴市场。 会谈重点还涵盖了柬埔寨通过丰富金融工具、吸引国内外投资者参与以深化市场发展的举措。富亚资产管理私人有限公司 (BAMPL) 表示出对在柬埔寨开展投资及运营的浓厚兴趣,此举与其亚太区整体战略高度契合,有助于为投资者提供更多元化的市场机会。 Vin Pheakdey 博士阁下 进一步强调了监管合规、稳健风险管理标准及持续投资者教育的重要性,并向富亚资产管理私人有限公司保证,柬埔寨证券交易监管机构将支持有信誉的外资机构在柬埔寨市场负责任地开展业务。 富亚资产管理私人有限公司团队 分享了其业务模式、区域经验及在柬埔寨资本市场的战略愿景,其提出的业务计划,包括基金管理与分销服务,也进行了详细审议。 Sou Socheat 阁下 在会议总结中提供了建设性反馈,概述了获得牌照及运营批准的关键监管要求,并就如何在柬埔寨证券市场建立业务实体提供了实际指导,同时重申柬埔寨证券交易监管机构对认真投资者及合作伙伴的开放态度,鼓励其与柬埔寨的金融发展目标保持一致。 此次会晤体现了柬埔寨推动资本市场发展、增强国际连接的积极姿态,为吸引外资、推动金融产品创新及加速经济长期增长奠定了基础,对本地及国际投资者均具有重要意义。
市场展望
2026 March Market Outlook: Markets Under Pressure as Geopolitical Tensions Rise
The US-Israel war with Iran has created a delicate balancing act between investing for resilient growth and managing geopolitical volatility. While a "soft landing" remains the baseline for many advanced economies, the landscape has grown more complex following the late-February shocks. On interest rate watch, the US Fed is expected to maintain a "higher-for-longer" stance to counter inflationary pressures from rising energy cost, and to a lesser extent the new 15% global tariffs. Markets are pricing in a sustained "war premium" in energy. With Brent crude hovering near $100, any further escalation in the Middle East could reignite global supply-side inflation, which may lead to extended high-interest-rate environment and hence leading to a sharp global economic slowdown. In China, it has largely stayed away from the Middle East war though it has urged US and Israel to de-escalate and stop its aggression against its ally, Iran. China is amongst the most affected countries by the closure of the Strait of Hormuz, though Iran has allowed some Chinese-flagged oil tankers to transit through. Meanwhile, all eyes are on the implementation of the 15th Five-Year Plan. Success hinges on whether Beijing’s "New Quality Productive Forces" can offset the structural drag of its property sector. After the February technology sector correction and in this current environment of heightened volatility, we remain highly selective in the technology sector while diversifying across markets, maintaining our disciplined, bottom-up approach to portfolio construction.
2026 February Market Outlook: From U.S. Policy Turmoil to Mixed Signals Across Asia
The geopolitical scene in the US has been uncertain and volatile. The January jobs report exceeded expectations, though employment gains were largely concentrated in the healthcare sector. Kevin Warsh, known for his hawkish stance, has been nominated as the next Federal Reserve Chair, though this remains to be confirmed by the Senate. In the past week, the Supreme Court has ruled against President Trump’s International Emergency Economic Powers Act (“IEEPA”) tariffs. In return, the Trump administration acted quickly to impose 10% global tariffs, and immediately raised to 15% that will remain effective for 150 days under a separate trade law. These developments have contributed to a weakening US dollar, which is further exacerbated by rising US-Iran military tensions. Gold extended its rally and reached new highs, while silver surrendered most of its gains. Investors remain cautious amid sharp swings in these traditional safe haven assets. In Asia, market performance has been mixed. Indonesia experienced its largest stock crash since 1998, whereas South Korea and Taiwan delivered strong returns. Markets have shown heightened sensitivity to the external macro environment, resulting in intermittent pullbacks. Most recently, Chinese stocks rose as IEEPA tariffs were removed as China is set to face lower duties on shipments to the US. The Shanghai Composite and Hang Seng indexes also experienced recent declines, as is expected due to thin trading volumes during the Lunar New Year holiday season. Overall sentiment towards Asian equity markets amid the uncertain global political climate remains positive. Against this backdrop, we continue to diversify across different markets and sectors while remaining selective to stock selection, particularly within the technology sector. We continue to maintain a disciplined, bottom-up approach in portfolio construction.
2026 January Market Outlook: A Month That Redirected Market Attention
The New Year began with subdued volatility, but the calm was subsequently shattered by geopolitical events, notably US’s desire to take over Greenland for its strategic Arctic Circle argument. Demand for gold and silver skyrocketed with prices hitting new fresh highs. However, these high precious metal prices can create a range of challenges for precious metal-dependent industries like solar panel makers and EV producers which use silver as part of their components in their production. This may further impact the profitability of the solar panel makers which are already facing an oversupply situation. Asian markets started the year mixed but with some positive moves. Several key themes are driving the markets, central amongst them is a strong Asian IPO pipeline especially in Hong Kong and India. Other country-specific themes that are driving the markets include the deployment of funds from the Equity Market Development Programme in Singapore. The Korean Kospi has exceeded their President’s target, with technology companies fueling the rally on accelerated semiconductor demand. China surprised with an export outperformance with a record 2025 trade surplus, plus resurgent interests in AI-related tech names. While in Japan, performance is mixed where there are concerns with the volatility and soaring yields in the Japanese Government Bonds market. In 2025, US technology stocks dominated investor attention for much of the year, later turning to precious metals commodities. This period also underscored the importance of diversification and currency exposure beyond the US. With growth now amplifying across global markets, moderate softening of the US dollar may act as a drag on returns from US assets. Against this backdrop, we retain our emphasis on broadening exposure to other markets and sectors while being mindful of our stock selection, particularly in the technology sector. We continue to maintain a disciplined, bottom-up fundamental approach in portfolio construction.
2025 December Market Outlook: Protecting Value as Risks Reprice.
The hawkish rate cut signaled the Fed’s caution, even as tariff-related inflation pressures appeared to be fading. November’s jobs report suggested a subdued consumer environment. Unemployment had risen to its highest level since 2021, and retail sales remained unchanged despite Black Friday sales. Though the Trump administration has softened its language on China, recent developments highlight the delicate truce in their trade war. The U.S. has restricted China’s access to technology, such as permitting limited Nvidia chip exports, and formed an international partnership to counter China’s rare earth dominance. Across Asia, the picture remains mixed. The weaker U.S. dollar alleviates pressure on currency weakness in countries like Indonesia, South Korea, India, and the Philippines. The Bank of Japan have responded to the Fed’s rate cut by raising interest rates by a quarter point in a widely expected decision. In China, the economy continues to be supported by sustained capital inflows and the boom in exports while pivoting away from dependence on U.S. consumers. This was in spite of the property sector slump, missed industrial production expectations, weak retail sales, and unchanging unemployment rates. Measures to drive consumption appear ineffective, and rising trade frictions with countries beyond the U.S are weighing on sentiment. Investors are increasingly watchful for signs of an AI-driven bubble, including circular financing risks inflating valuations, where such dynamics could unwind abruptly. Against this backdrop, investors face a strategic dilemma - rein in AI exposure ahead of a potential bubble popping, or double down to capitalize on game-changing technology breakthroughs. In response, we are positioning portfolios defensively and broadening exposure to other sectors. This includes increasing allocations to commodities such as silver and gold, which can serve as stores of value, and consumer staples, that tends to offer more resilient demand. We continue to maintain a disciplined, bottom-up fundamental approach in portfolio construction.
2025 November Market Outlook: AI Bubble Alert
Mega-cap chip making company Nvidia Corp (“Nvidia”) became the first company to hit $5 trillion market capitalisation, likely due to U.S. President Trump’s comments ahead of the trade talk with Chinese President Xi Jinping at the end of October. The talk resulted in a consensus on cooperation in expanding agricultural trade and pausing the rare-earths licensing regime for a year. Mid-November saw the conclusion of the record U.S. government shutdown, which lasted 43 days, and put an end to unpaid furlough and other government operations. Consequently, the October jobs report was cancelled due to insufficient data. The ambiguity around unemployment rates raised uncertainty about the state of the U.S. economy. Compounding concerns were exacerbated by growing anxieties about stretched valuations of an “AI bubble”, which led to a selloff towards the end of November. Similarly, the Asian equity market, primarily due to technology companies in the AI landscape, slumped after an initial rally in the previous month’s end. In the semiconductor space, South Korean company Samsung Electronics Co., Ltd. reported an 80% surge in profit and SK Hynix Inc. continued to lead in chip memory. In China, different industries continue to diverge as technology companies grow while consumption and property remain a drag. In response, China’s policymakers are evaluating various measures to support the housing market. The MSCI Emerging Markets Index fell sharply, and losses were led by the tech heavy Korean Kospi index where the aforementioned Korean companies posted steep declines. Looking ahead, we remain cautious of the volatility in the markets. Due to concerns about inflated valuations for technology companies, the pullback observed in late November may have been a profit taking move or a price correction. Investors remain watchful for indicators of the widely discussed AI bubble, and signals for a potential burst. Against this landscape, we maintain a disciplined and balanced approach, grounded in bottom-up fundamental analysis in our portfolio construction.
2025 October Market Outlook: Between Tariffs and Growth — Searching for Stability
Towards the end of September, in an effort to protect American jobs, the Trump administration made surprised changes to immigration visa laws that target foreign talent, particularly those working in the U.S. technology sector. Amongst the heaviest users of this targeted immigration visa scheme include Amazon.com Services LLC, Meta Platforms Inc, Apple Inc and Google LLC. Later that month, the U.S. Immigration Service issued guidance that included exceptions, thus stabilising concerns. However, the labour market outlook remains uncertain with the shutdown of the U.S. government, which began on October 1st. Consequently, data reports such as the official U.S. monthly jobs report and the labour-intensive Consumer Price Index report would likely be delayed amidst the impending mass firing and unpaid furlough of certain segments of federal workers. In China, September data showed low domestic demand, a continued property downturn and the weakest economic growth in a year. With the ongoing US-China trade war, Chinese regulators have urged against the use of Nvidia chips completely, stating that domestic chips are adequate in delivering comparable computing power. As such, Chinese domestic chipmakers have benefitted from efforts to become self-sufficient, and this move should serve as a catalyst to grow the technology sector. China tightened exports of rare earth where products that contain certain rare earths or traces of it sourced from China will now require an export license. With a 70% share of global supply, the supply crunch would be felt by the U.S. and Europe. In response, the U.S. imposed a 100% import surtax on Chinese goods effective November 1st, ahead of the 90-day tariff truce that was set to end on November 9th. Despite the trade war uncertainty, Chinese exports rebounded in September from a slump in August, beating estimates and increasing 8.3% year over year while imports grew 7.4%. The sweep of high tariffs from the U.S. have led China to seek imports from other avenues, such as Brazil and Argentina for soybean, which has caused farmers in the U.S. to scramble for buyers. On the other hand, aggressive price competition among manufacturers in China have led to what has been termed ‘Chinese dumping’, where low prices due to Chinese imports are alarming domestic producers in India, Africa and South-east Asia. Looking ahead, we remain cautiously optimistic of the global markets. In the U.S., businesses and households are concerned over trade tariffs, changes to immigration laws and the shutdown of the U.S. government. The structural imbalance in China represented by slow domestic growth and heavy reliance on export further weighs on global financial markets and investor confidence. Despite the uncertainty, there were reports of pockets of positive news. Alternative data in the U.S. such as restaurant bookings and theatre box office receipts reflects resilient consumer activity. The number of seated diners was up 9% from last year and domestic box office grossed 13% more than the previous month.