

洞察力
获取最新资讯、专家分析及市场展望,抢先洞察行业动态。
新闻中心
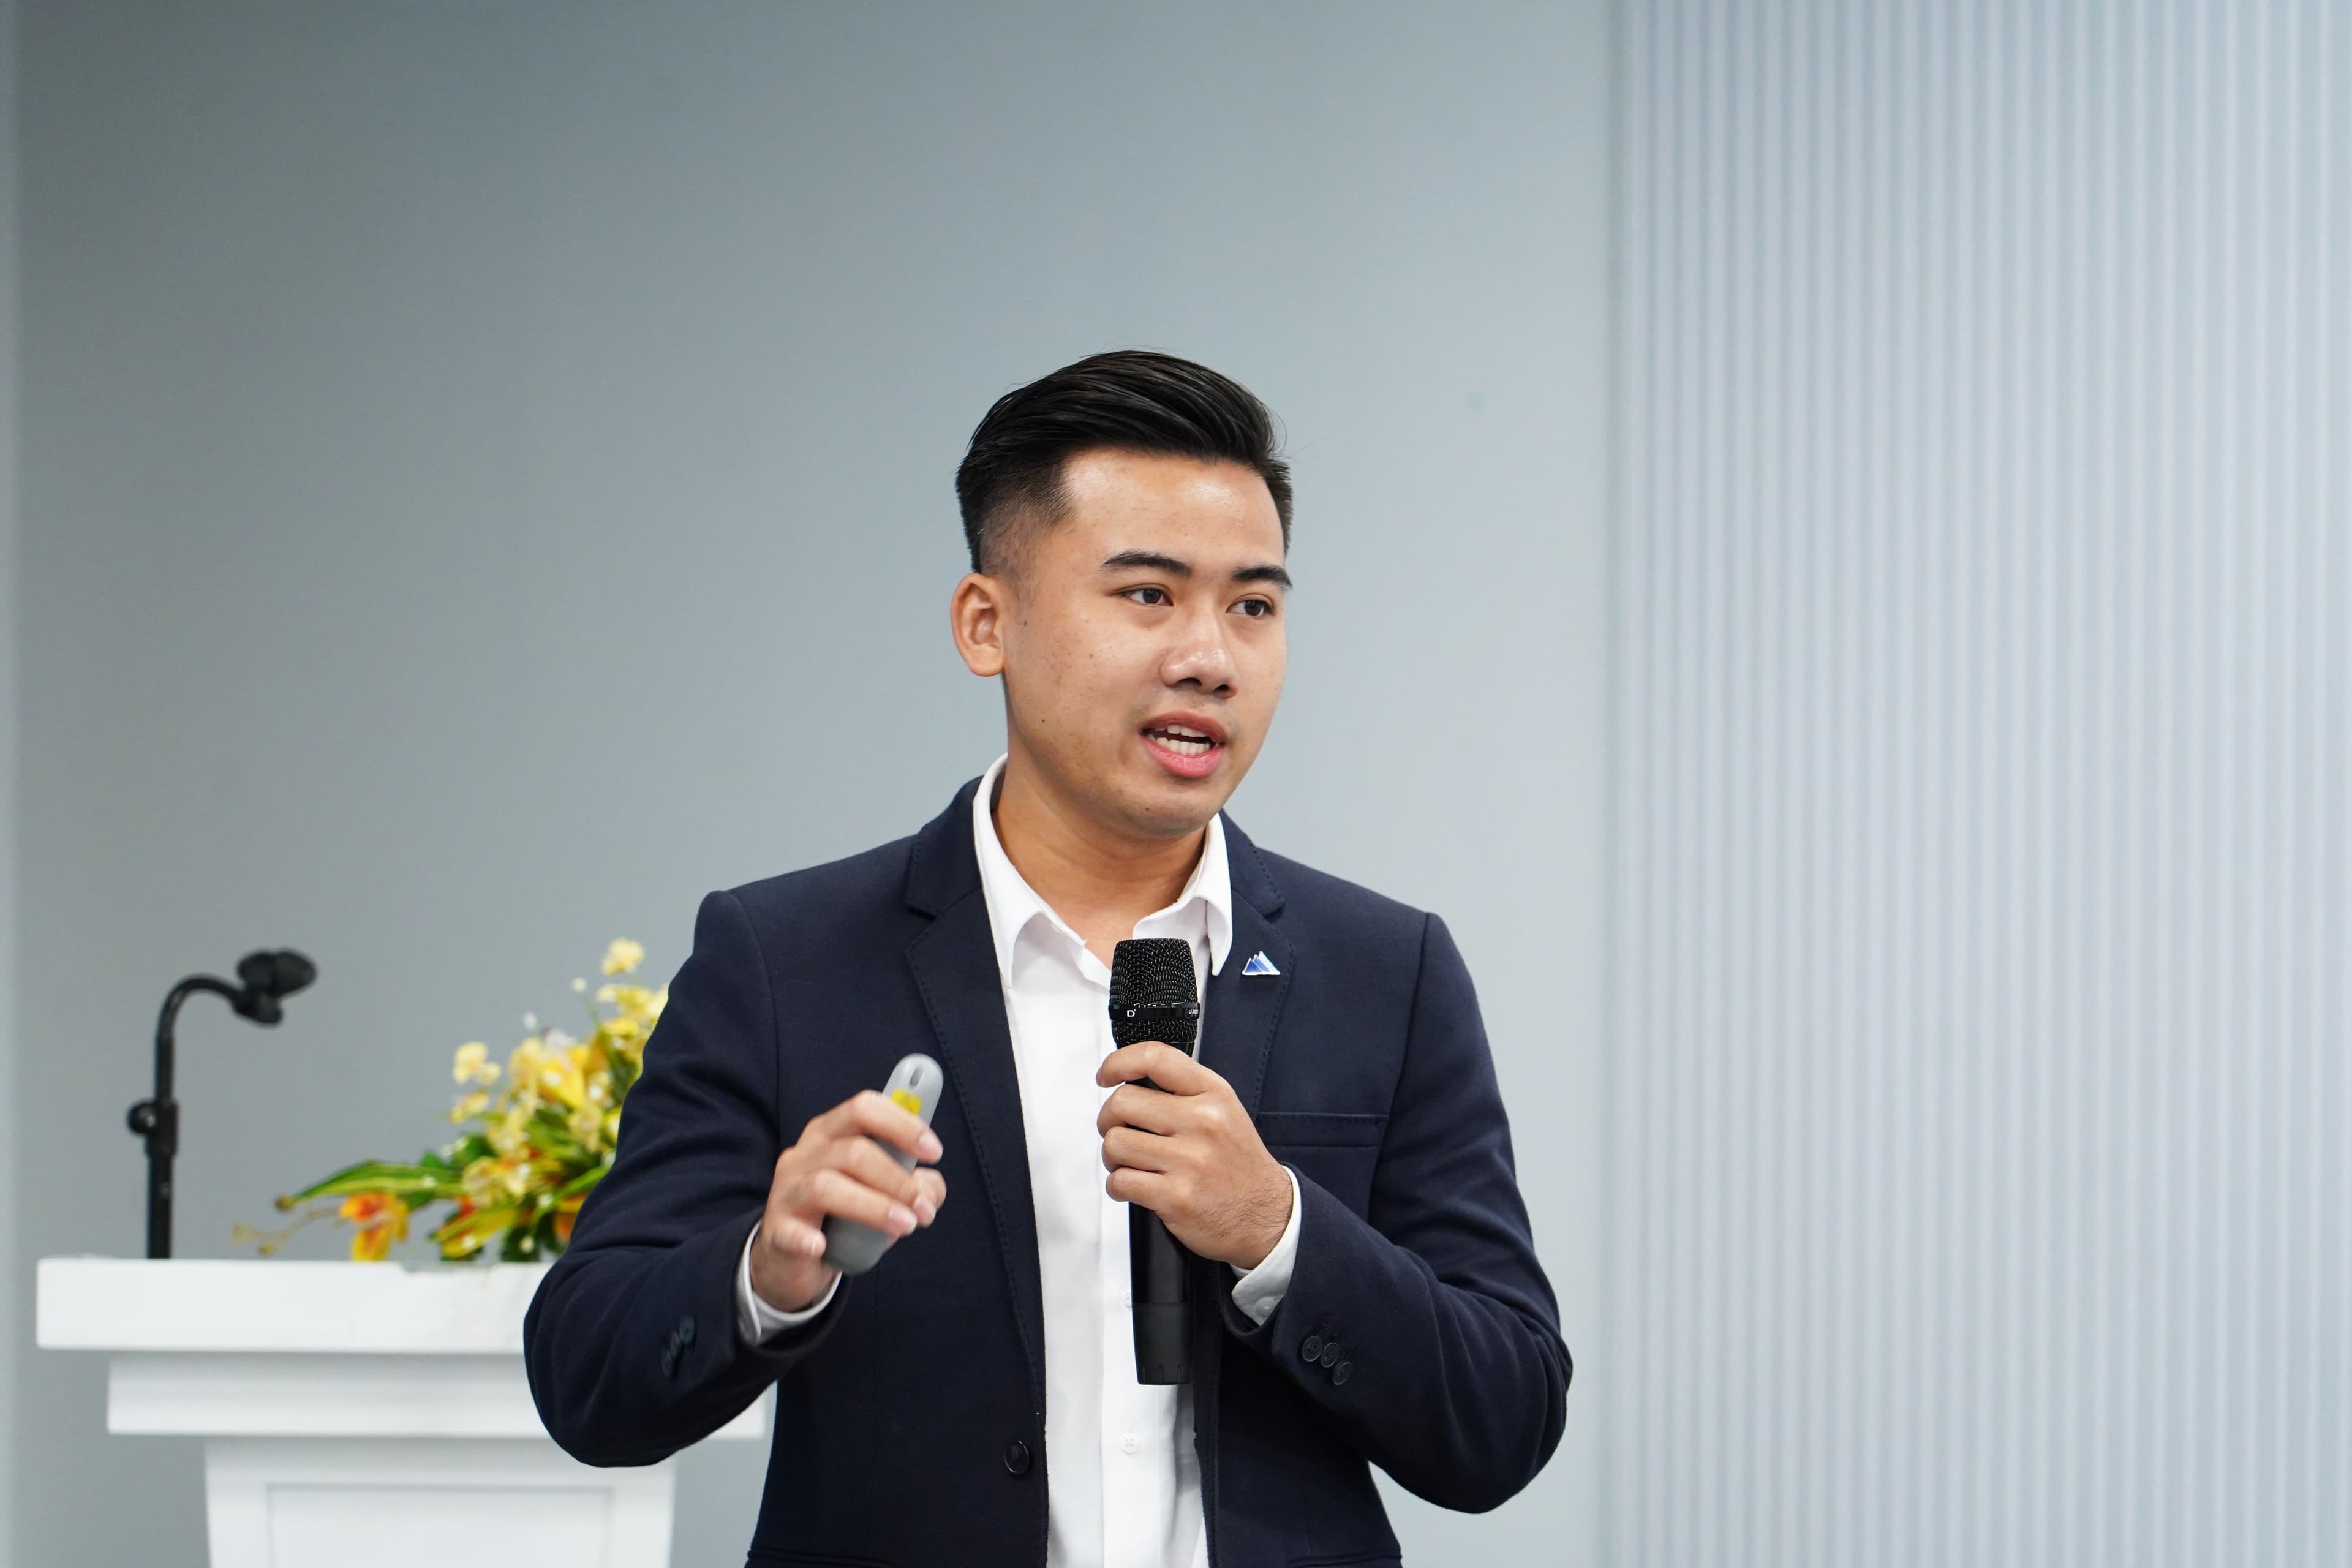
富亚资产管理 (柬埔寨) 有限公司在柬埔寨证券交易监管机构第29期培训中分享集体投资计划风险管理洞察
在柬埔寨证券交易监管机构举办的第 29 期证券行业培训中,富亚资产管理 ( 柬埔寨 ) 有限公司重点分享了集体投资计划的风险管理经验与实践策略。 2025 年 4 月 28 日上午,富亚资产管理 ( 柬埔寨 ) 有限公司运营部代表 Veasna Monireach 先生在柬埔寨证券交易监管机构主办的第 29 期培训、考核及继续专业教育活动中发表了题为《集体投资计划风险管理》的专业演讲。活动在业务发展中心举行。 Monireach 先生在演讲中强调了在集体投资计划运营中实施健全风险管理的重要性,以确保投资者保护、遵守监管要求及基金的可持续表现。他通过真实案例和最佳实践,展示了富亚在强化柬埔寨投资基金行业及提升证券行业专业水平方面的承诺。 此次分享进一步体现了富亚在推动柬埔寨金融市场发展、教育及创新方面的持续贡献。
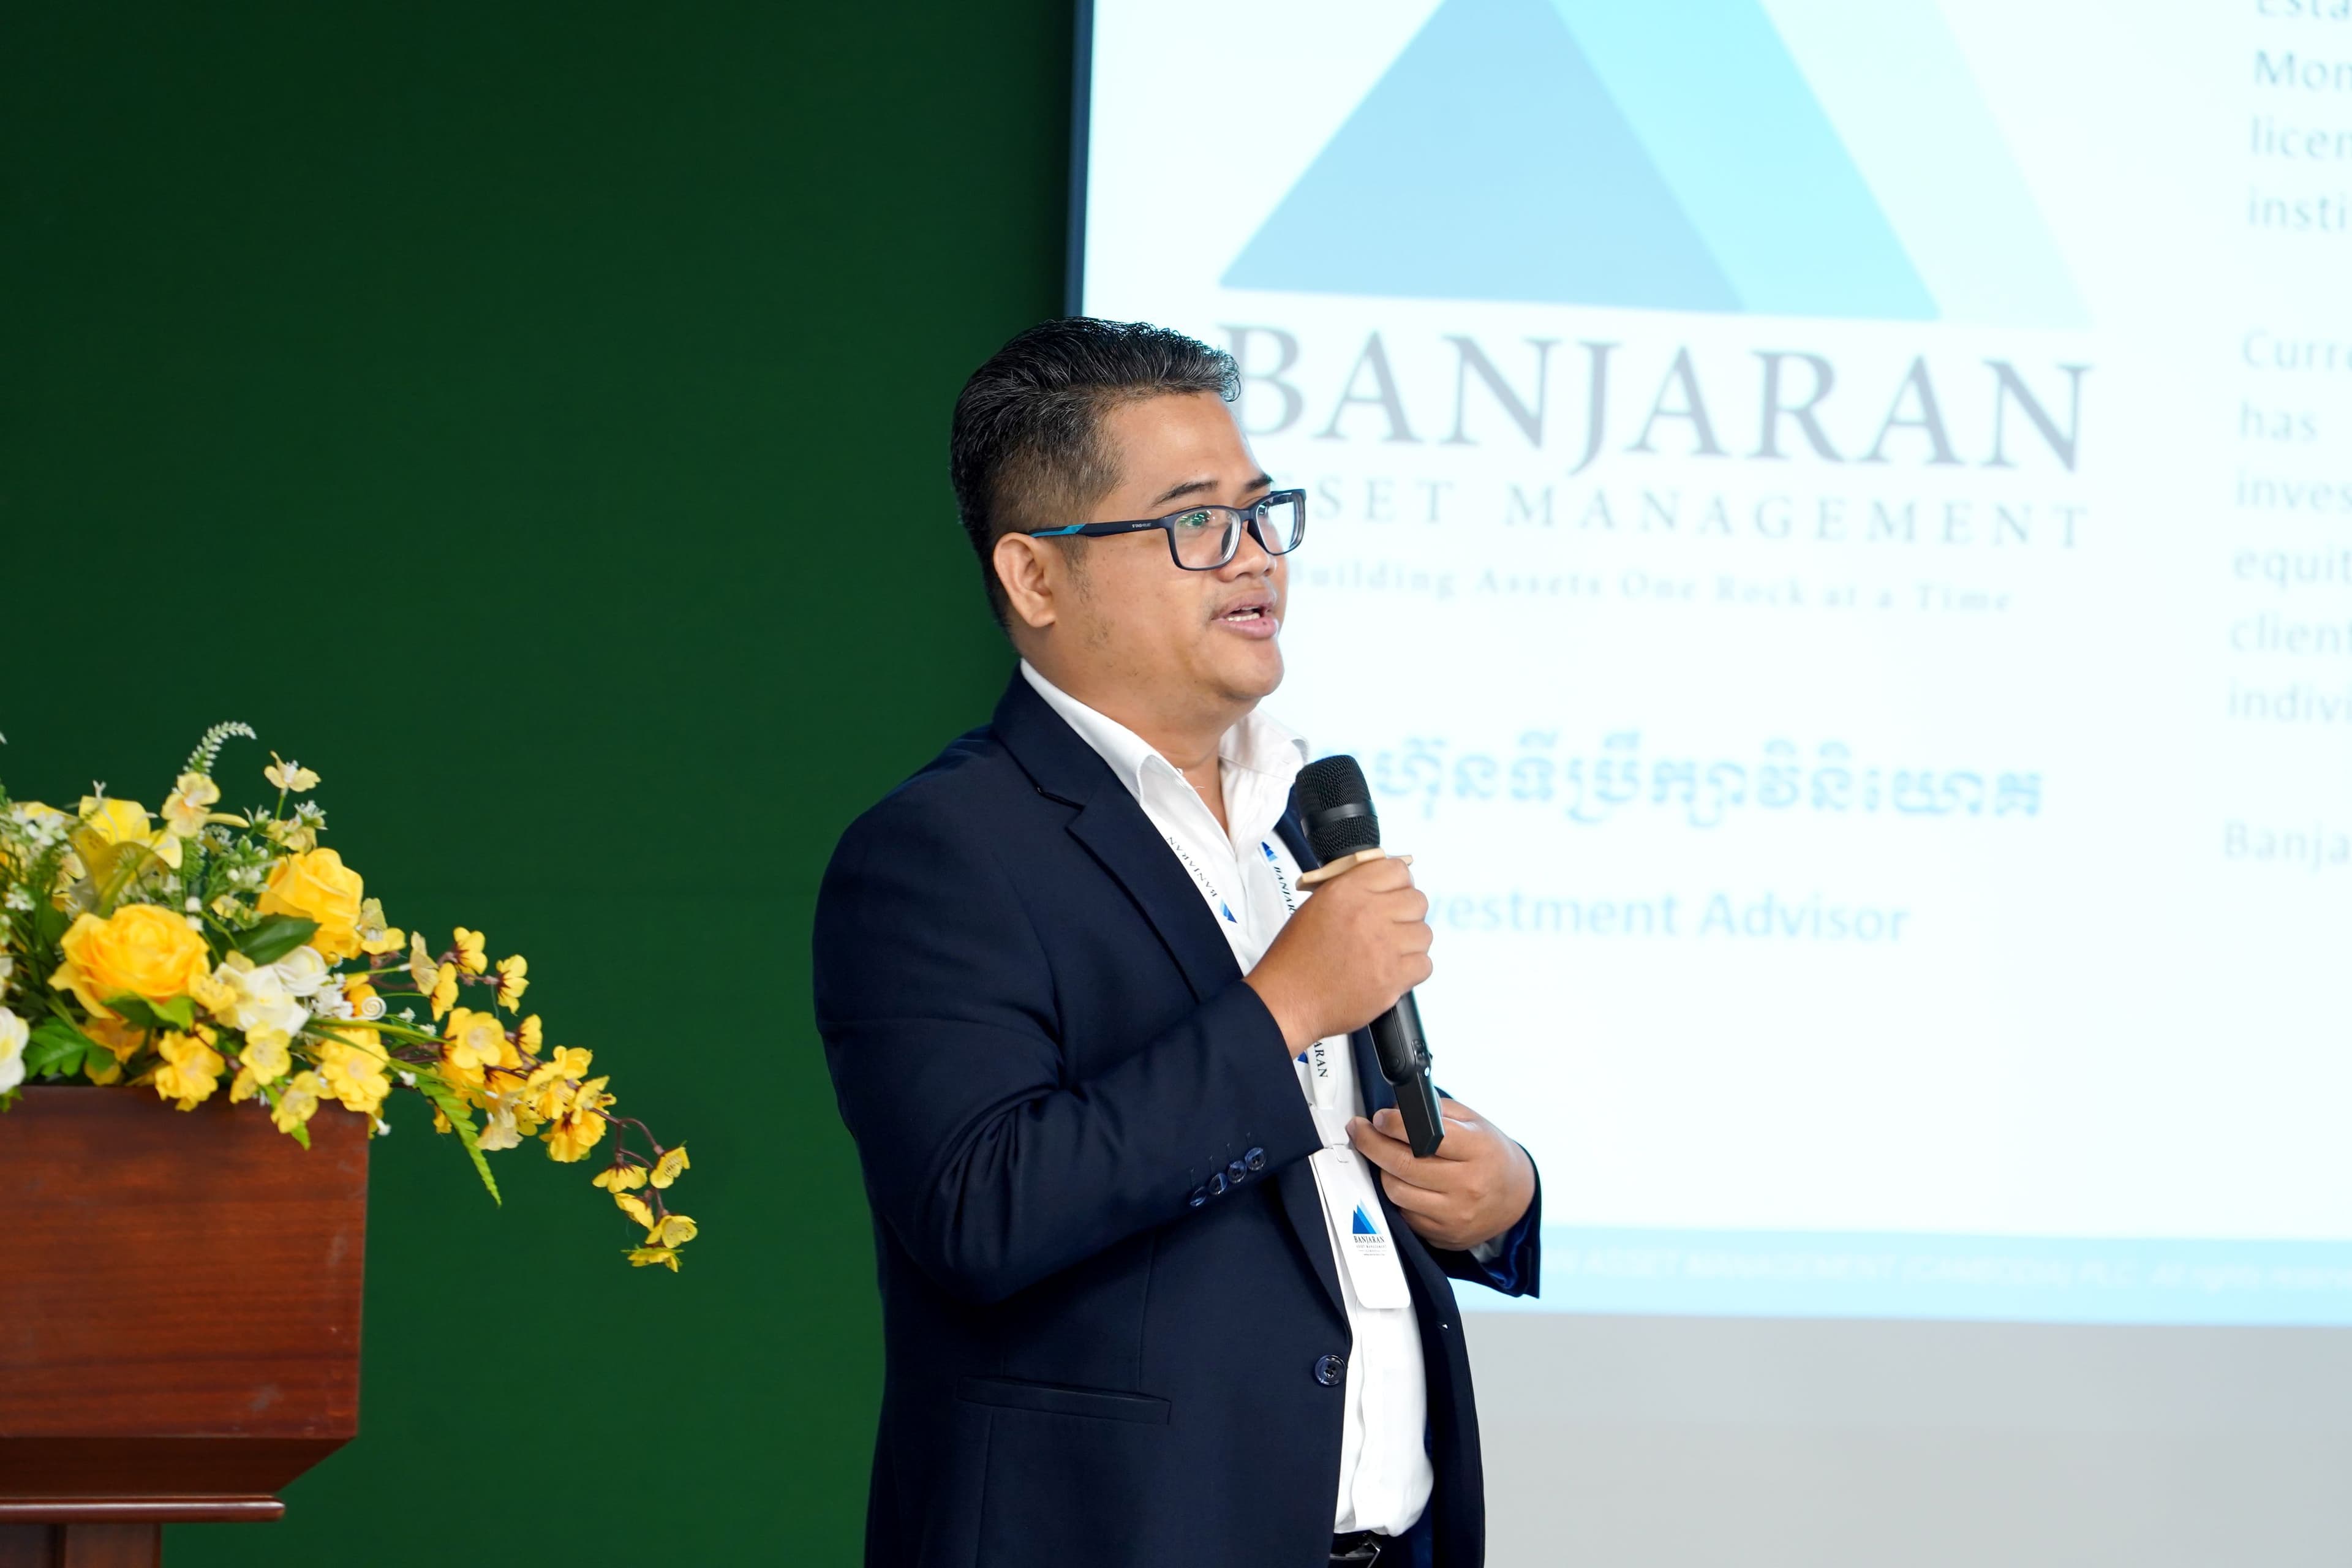
在柬埔寨证券交易监管机构第29期证券行业培训中分享柬埔寨首支集体投资计划基金经验
在柬埔寨证券交易监管机构举办的第 29 期证券行业培训中,富亚资产管理 ( 柬埔寨 ) 有限公司分享了在管理柬埔寨首支集体投资计划基金方面的宝贵经验。 2025 年 4 月 25 日上午,富亚资产管理 ( 柬埔寨 ) 有限公司企业经理 Nhem Sopaul 先生在柬埔寨证券交易监管机构举办的第 29 期培训、考试及持续专业教育活动上发表了主题演讲。活动在商务发展中心举行,汇聚了柬埔寨证券行业的各类专业人士。 Sopaul 先生分享了富亚在发行柬埔寨首支集体投资计划基金方面的宝贵经验,并概述了资产管理与基金运营的相关实践。他的演讲强调了富亚作为本地基金管理市场先锋的角色,以及公司通过创新、透明和投资者教育支持柬埔寨资本市场发展的坚定承诺。 此次培训活动标志着在金融行业促进专业能力提升和知识分享的又一重要里程碑,同时进一步巩固了富亚在柬埔寨投资市场中的领导地位。
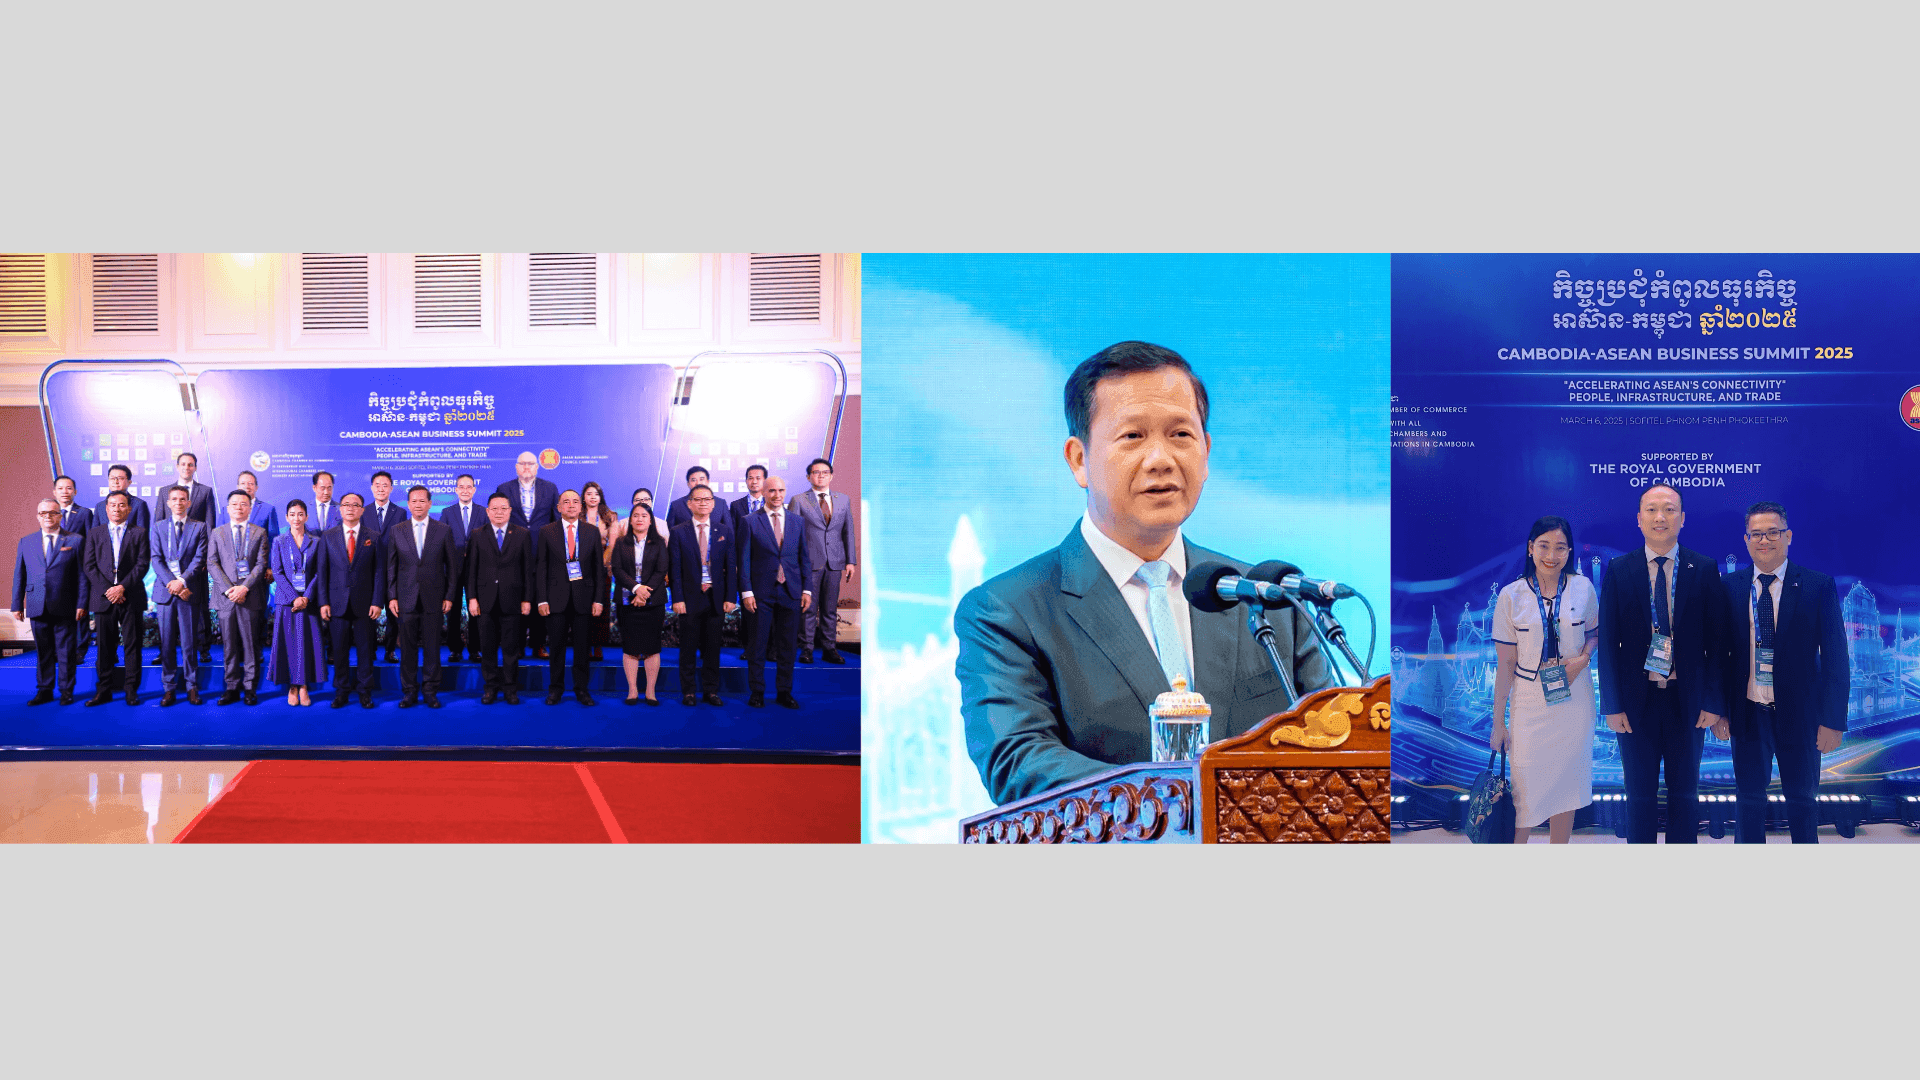
富亚资产管理 (柬埔寨) 有限公司出席2025柬埔寨-东盟商务峰会
2025 年,主题为 “ 加速东盟互联互通 —— 人力、基础设施与贸易 ” 的 2025 年柬埔寨 - 东盟商务峰会。 2025 年 3 月 6 日,富亚资产管理 ( 柬埔寨 ) 有限公司出席了在金边 Sofitel Phnom Penh Phokeethra 酒店举办的 2025 柬埔寨 - 东盟商务峰会。本届峰会以 “ 加速东盟经济一体化 ” 为主题,旨在为东盟区域内的经济合作与发展提供活跃平台,展示柬埔寨在区域经济一体化中的日益重要作用。 峰会汇聚了政府官员、企业领袖及行业专家,涵盖首席执行官、高级管理人员、企业家、投资者、政策制定者及思想领袖,代表了东盟各行各业的多元产业和部门。 峰会由 柬埔寨王国首相 Samdech Moha Borvor Thipadei Hun Manet 阁下 主持,首相亲自阐述了柬埔寨皇家政府对东盟企业的支持承诺及推动共享繁荣的发展愿景。 峰会内容丰富,不仅包含主题演讲和深入讨论,还提供了广泛的交流与合作机会。包括商务午餐和柬埔寨投资展示,让与会者与行业领导者建立联系并探索关键领域的投资机会;同时,商务配对 环节促成了预先安排的 B2B 会议,为潜在合作和伙伴关系奠定基础。 闭幕式总结了峰会的主要成果,并发出持续合作与投资东盟的号召。峰会为与会者提供了深入交流的平台,进一步推动了柬埔寨及东盟区域的经济增长、区域一体化与可持续发展。 2025 柬埔寨 - 东盟商务峰会成为推动经济增长、加强区域一体化及促进可持续发展的关键活动,吸引了多元化的与会者,为柬埔寨及东盟地区经济发展贡献重要力量。 2025 柬埔寨 - 东盟商务峰会议程 : * 主旨演讲:柬埔寨矿产与能源部部长 Keo Rottanak 阁下 专题讨论 1 :建设东盟未来 —— 基础设施建设与区域互联互通 探讨基础设施建设在推动经济增长与区域整合中的关键作用,包括实体基础设施、数字互联及东盟能源网 (AEG) 建设。 专题讨论 2 :通过贸易与投资驱动繁荣 重点探讨东盟如何通过贸易和投资推动经济发展,分享关键战略、举措与合作经验。 主要讨论嘉宾: - 柬埔寨副首相兼开发委员会第一副主席 Sun Chanthol阁下 - 柬埔寨商务部部长 Cham Nimul阁下 - 总理办公室部长兼税务总局局长Kong Vibol阁下 - 海关总局副总干事 Chan Sopheap先生 - 柬埔寨证券交易监管机构总干事 Sou Socheat阁下 专题讨论 3 :人力资本 —— 贸易与基础设施发展的关键 本次专题讨论聚焦人力资本在推动东盟贸易与基础设施发展中的关键作用。来自东盟各成员国的知名专家与企业代表探讨了如何通过投资人力资本释放区域经济潜力,为东盟可持续增长和区域一体化提供战略支持。 主要讨论嘉宾: - 柬埔寨劳动与职业培训部部长 Heng Suor阁下 - 柬埔寨工业、科技与创新部部长 Hem Vanndy阁下 - 香港经济贸易办事处驻曼谷主任 Parson Lam先生 - Wing银行人力资源主管 Sheanghai Lao先生 主持人 :柬埔寨美国商会会长 Casey Barnett 先生 Pictures credited to ASSOCIATION OF SOUTHEAST ASIAN NATIONS
路演回顾:洞察与创新全面呈现
2024 年 12 月 7 日上午,富亚资产管理 ( 柬埔寨 ) 有限公司 与爱喜利达银行 Chamkar Doung 分行携手举办了具有里程碑意义的活动 —— “ 柬埔寨首个基金认购路演 ” 。本次路演旨在向本地投资者重点介绍 “ 富亚亚洲股票基金 (BAEF)” ,展示其作为推动资本增长与促进柬埔寨经济发展的催化力量所具备的巨大潜力。 活动中,专家团队通过精彩的分享向与会者全面讲解了 “ 富亚亚洲股票基金 ” 的战略目标,强调其聚焦区域高成长性行业的投资方向。演讲涵盖基金的投资理念、风险管理策略及预期回报等关键内容,结合柬埔寨市场特性,为与会者带来深入且实用的投资见解。 路演期间,参与者积极与行业专家交流互动,深入了解新兴投资趋势及策略。此次活动不仅突出了基金在推动经济增长方面的潜在作用,也进一步强化了金融机构与资产管理公司在建设稳健投资市场中的重要协作关系。 总体而言,本次路演为本地投资者提供了宝贵的信息资源,帮助他们更好地把握不断发展的金融市场格局。同时, “ 富亚亚洲股票基金 ” 在活动中的亮相,进一步凸显其在推动柬埔寨经济增 长中的关键地位 —— 这只是开始,未来将有更多令人期待的投资机遇陆续展开。
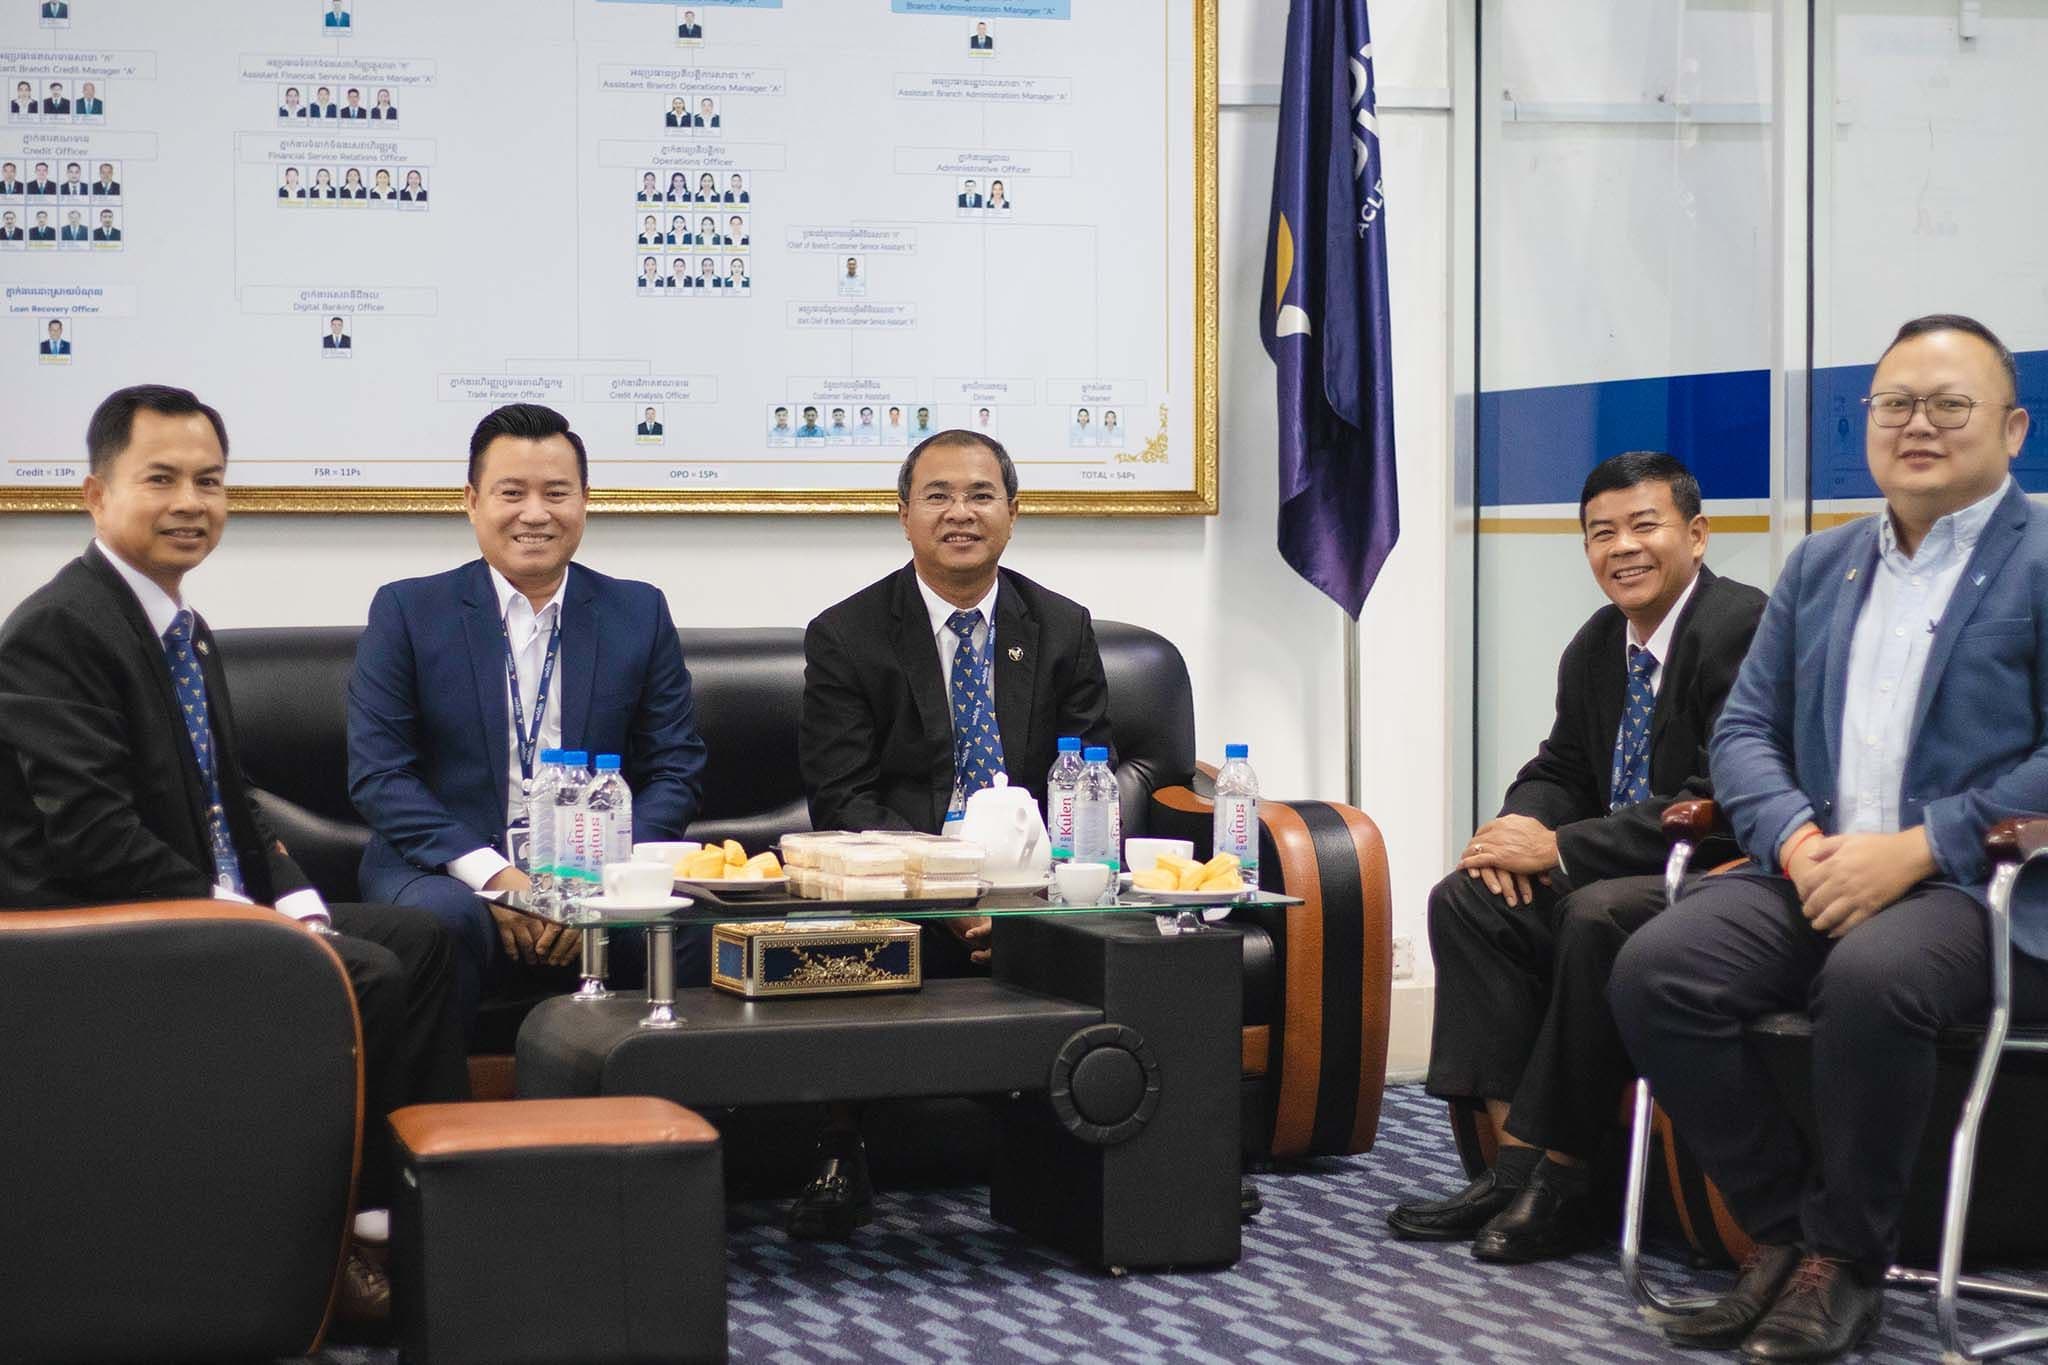
柬埔寨首个基金认购路演
2024 年 11 月 23 日上午,富亚资产管理 ( 柬埔寨 ) 有限公司参与了由爱喜利达证券有限公司主办的 “ 柬埔寨首个基金认购路演 ” 。 在活动中,通过生动的基金介绍与专题分享,我们向广大参与者深入讲解了 富亚亚洲股票基金的核心理念、投资亮点与市场机遇。此次路演不仅有效提升了公众对集体投资计划的了解,也进一步扩大了基金在本地市场的影响力,成为推动柬埔寨金融市场发展的又一重要里程碑。 衷心感谢主办方及所有参与者对本次活动的大力支持,使活动得以圆满成功。
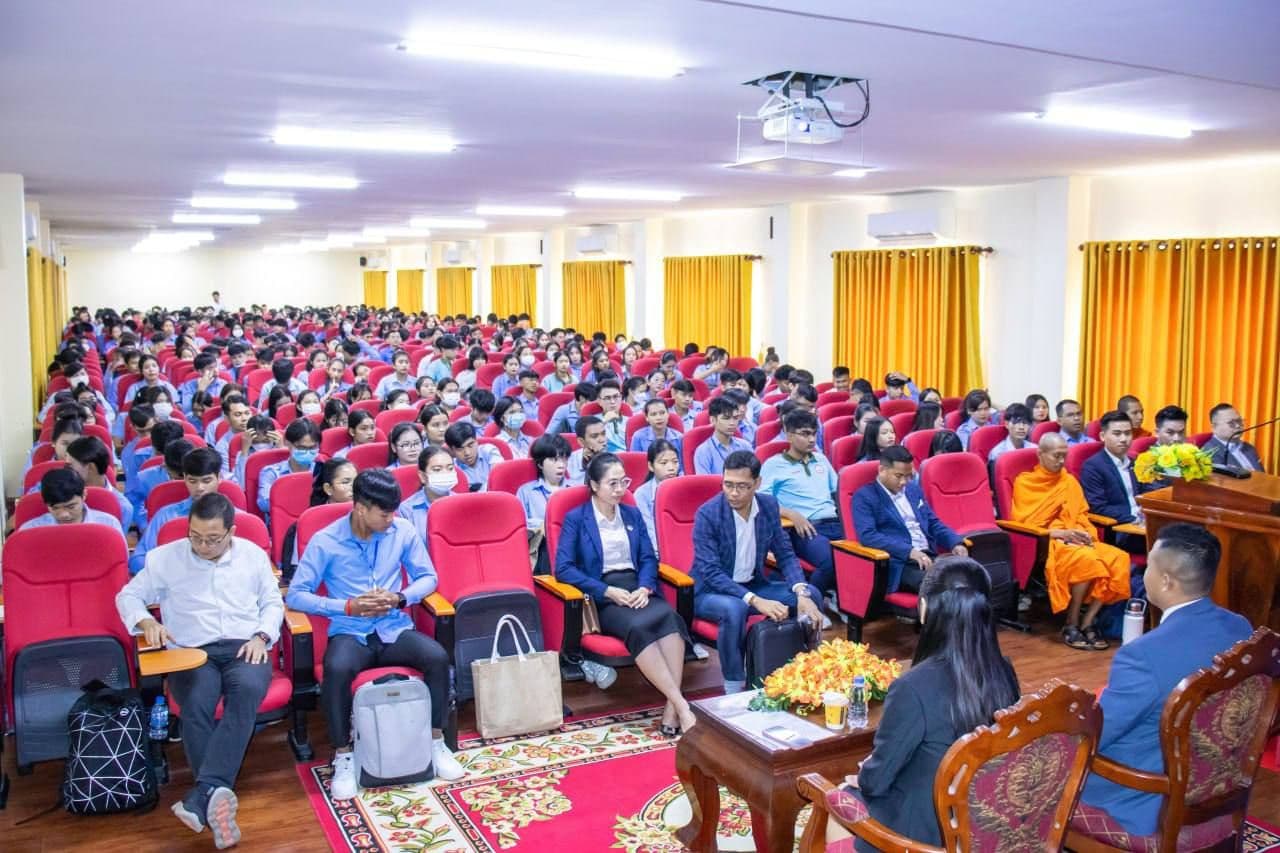
赋能未来投资者:富亚分享集体投资计划基金洞见
2024 年 10 月 30 日上午,富亚资产管理 ( 柬埔寨 ) 有限公司销售与市场执行员 Sok Chantola 先生 在 Preah Sihanouk Raja 佛教大学 开展了以集体投资计划基金为主题的专题分享。该活动属于由爱喜利达证券有限公司主办的 “ 智慧投资 ” 培训课程之一,旨在加深参与者对集体投资计划投资策略的理解。
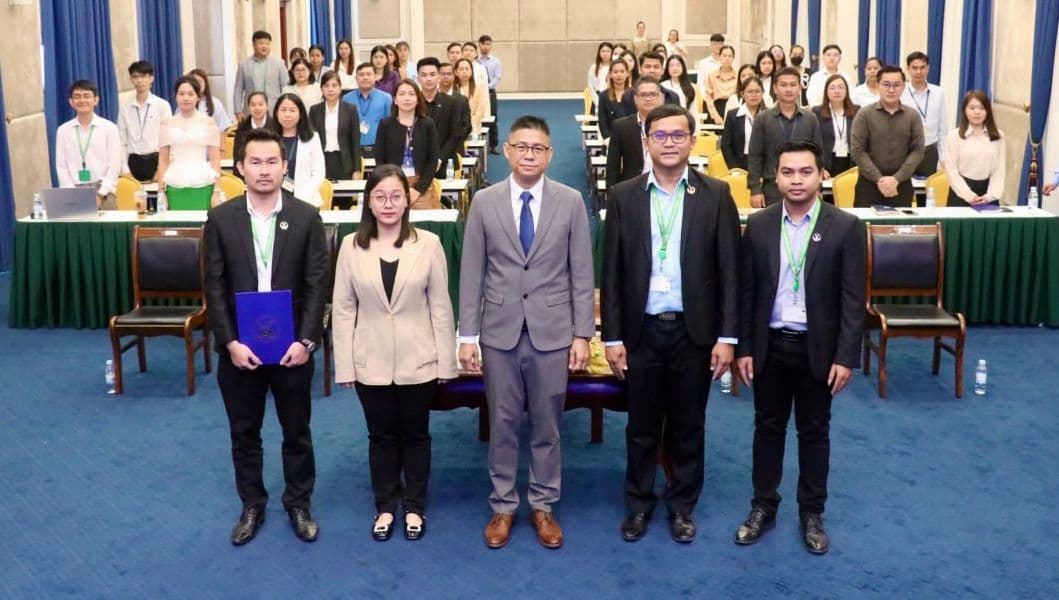
与柬埔寨证券交易监管机构共同举办的集体投资计划职业道德研讨会
2024 年 10 月 23 日 ( 星期三 ) 上午,柬埔寨证券交易监管机构 于非银行金融服务局大楼举办了主题为 “ 集体投资计划之职业道德 ” 的专题研讨会。本次研讨会面向基金管理公司、托管机构、分销商及受托人等行业参与者。 研讨会由柬埔寨证券交易监管机构副总干事 Vin Pakdey 博士阁下 主持,并代表政府特派员兼柬埔寨证券交易监管机构总干事 Sou Socheat 阁下 出席活动。 本次研讨会旨在帮助基金管理机构及相关企业深入理解职业道德、透明度和责任在集体投资计划业务中的关键作用。同时,研讨会亦强调行业机构需坚持高标准运营,以进一步增强投资者对金融市场的信心。 会议内容涵盖多项重要议题,包括:职业道德如何促进企业的可持续发展、如何确保合规经营、以及良好治理在金融行业中的重要性。这些讨论进一步强化了行业在稳健、透明和负责任框架下发展的必要性。 More Securities and Exchange Regulator of Cambodia
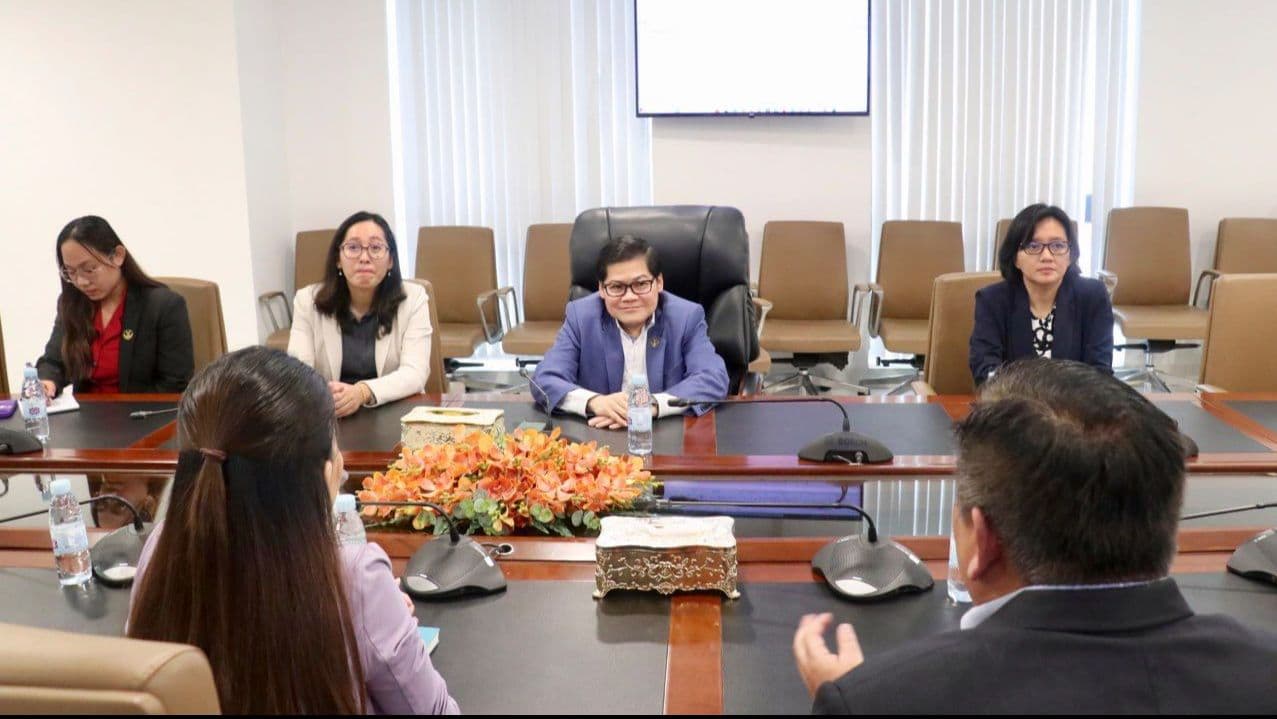
探索联合投资基金机会
柬埔寨证券交易监管机构政府代表兼总干事 Sou Socheat 阁下,率领代表团与富亚资产管理 ( 柬埔寨 ) 有限公司的代表进行会晤。 2024 年 10 月 11 日 ( 星期五 ) 上午, Sou Socheat 阁下及其团队与率领代表团与富亚资产管理 ( 柬埔寨 ) 有限公司的代表就联合投资基金项目进行讨论。会议在高度合作的氛围中顺利开展。 More Securities and Exchange Regulator of Cambodia
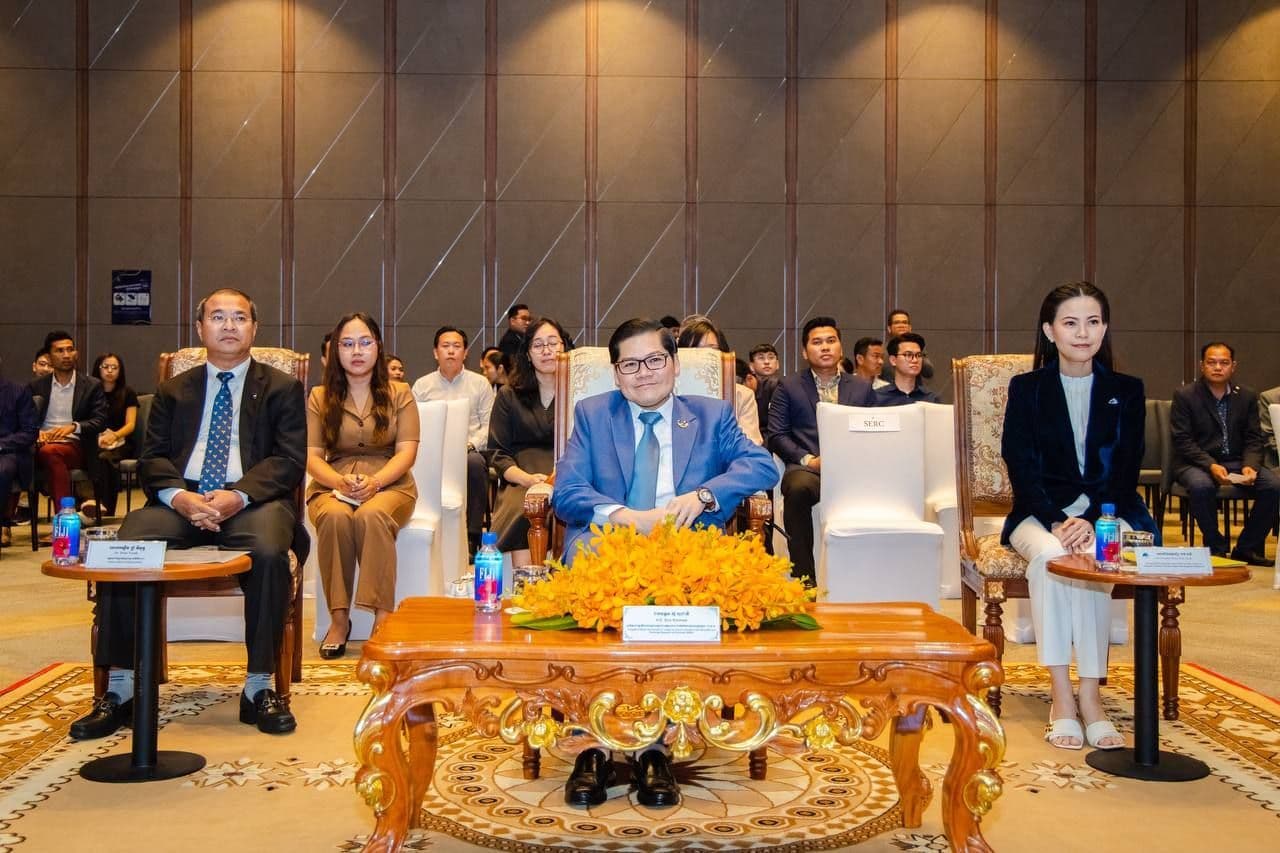
路演活动:2024 年柬埔寨首支集体投资计划基金认购启动
2024 年 10 月 10 日上午,富亚资产管理 ( 柬埔寨 ) 有限公司 . (BAMC) 与重要合作伙伴爱喜利达证券有限公司联合隆重举办了 “2024 年柬埔寨首支集体投资计划基金认购路演 ” 活动。本次活动非常荣幸地邀请到柬埔寨证券交易监管机构政府代表兼总干事 Sou Socheat 阁下 亲临指导并担任主礼嘉宾。 此项具有里程碑意义的活动标志着柬埔寨金融行业发展的重要阶段,我们正式向公众推出 富亚亚洲股票基金。活动通过深度讲解和互动讨论,向机构投资者、行业专家以及有意拓展投资机会的个人投资者全面展示了集体投资计划基金的潜力与价值。 路演深入介绍了集体投资计划基金的优势与特色,展示其如何推动更广泛的市场参与,并促进柬埔寨资本市场的持续发展。同时也体现了我们致力于推出创新型金融产品,以满足本地与国际投资者多元化需求的坚定承诺。 此次活动不仅是富亚资产管理有限公司的重要里程碑,也彰显了柬埔寨金融市场的快速扩集体投资计划基金在推动区域经济增长与投资机遇方面日益重要的作用。 我们对所有参与者的支持与出席表示衷心感谢。未来,我们将继续秉持使命,为投资者提供更便捷的投资渠道,并为柬埔寨经济的长远发展贡献力量。
市场展望
2026 September Market Outlook: Navigating Market Divergence
The Fed maintained a restrictive, data-dependent stance through August and subsequently raised the federal funds target range by 25 basis points to 3.75-4.00% citing persistent inflationary pressures. Updated projections point to the possibility of one further increase in 2026. Elevated long-dated US Treasury yields continue to present a valuation risk particularly for growth, technology and AI-related companies, whose expected cash flows lie further in the future. At the same time, continued corporate earnings delivery and investments in strategic technologies along the tech supply chain have so far helped the global economy absorb tighter financial conditions. Strong earnings guidance from major global technology companies supports the view that investment in data centres, advanced chips and supporting infrastructure remains resilient. Within Asia, performance has diverged meaningfully across countries. Singapore remains the region’s defensible market, with strong banking profitability and wealth management inflows attracting investor interest amid global uncertainty. Taiwan and South Korea’s technology sector continues to be major beneficiaries of surging AI-related demand. On the other hand, confidence towards China’s and Indonesia’s growth outlook remains fragile. China’s slow economic momentum is a result of a weak property market and slow domestic consumption, while Indonesia’s commodity price normalisation and concerns over capital outflows weigh on sentiment. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macroeconomic uncertainty.
2026 August Market Outlook: Navigating Volatility
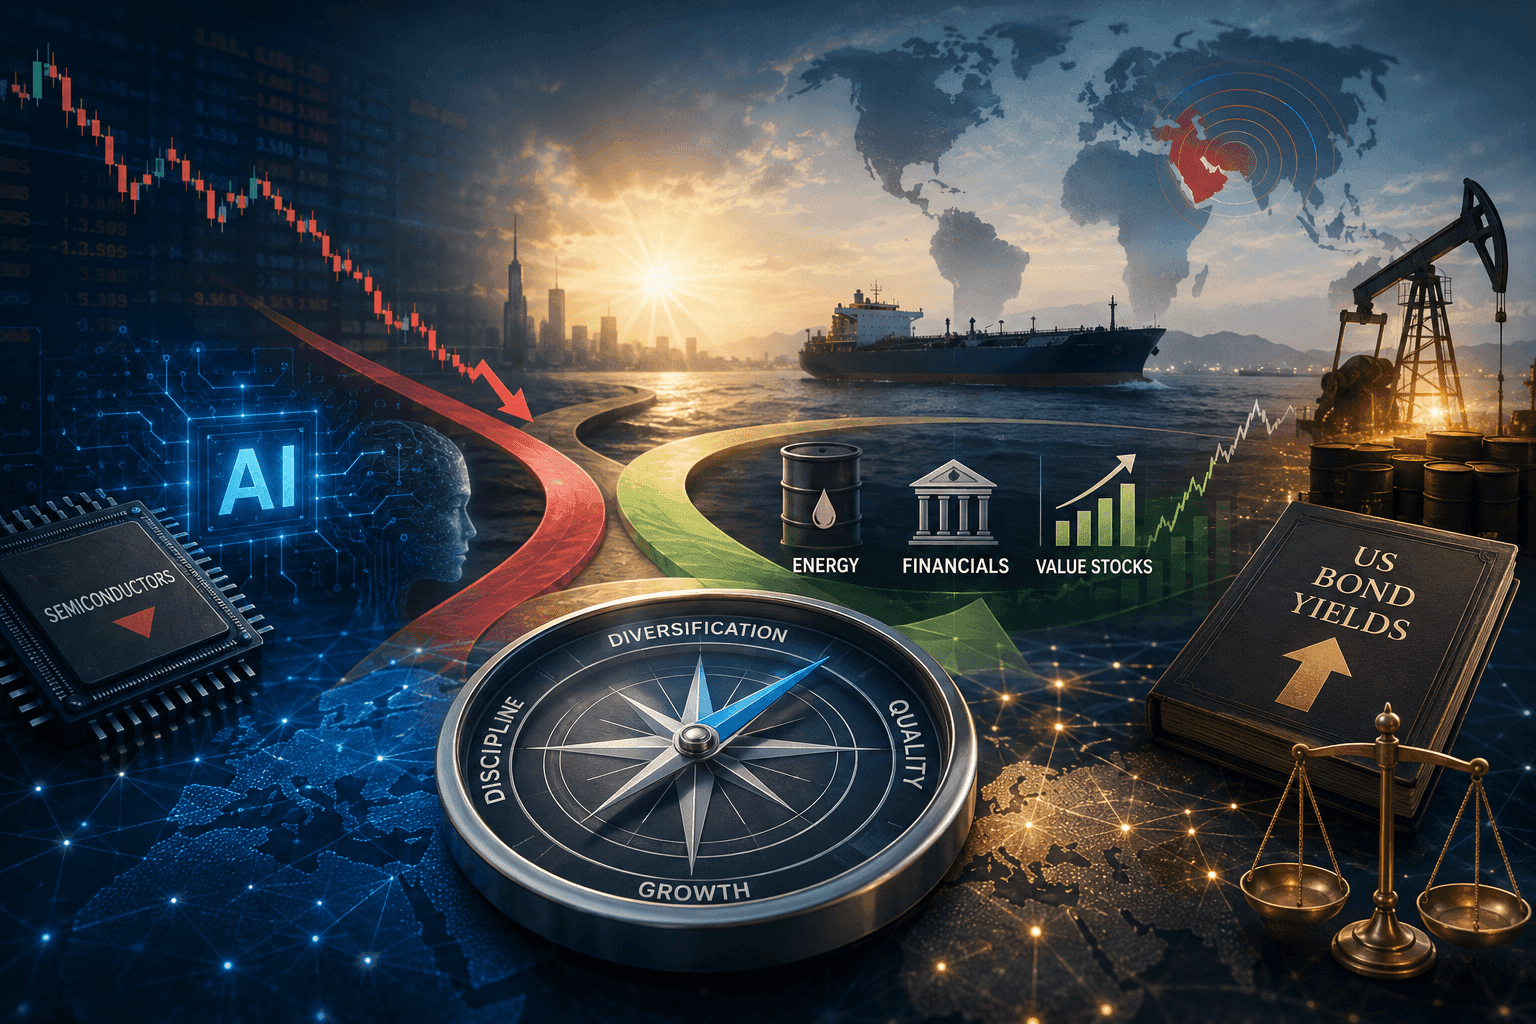
Concerns around the durability of AI-related capital expenditure and intensifying competition triggered a sharp sector sell-off after a mid-July peak. Investor sentiment turned more discerning on the back of earnings season, and questions arose regarding how sustainable the AI investment pace is without eating into cash generation. Capital rotated out of semiconductors and into energy, financials and value stocks, shifting to markets and names seen as less exposed to a single-theme correction. Layered on top was renewed Middle East escalation and its effect on rates expectations. Brent crude spiked back above $100/barrel intermittently after the US reinstated a naval blockade on Iran and announced plans to impose a levy on cargo transiting Hormuz, although the levy was never implemented. This revived inflation concerns and caused markets to price a reduced likelihood of further Fed easing. Elevated US bond yields further weighed on stocks. Looking ahead, renewed conflict or another AI-related pullback could swiftly unwind recent sentiment gains and force a repricing of both rates and earnings expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.
2026 July Market Outlook: Navigating Crosscurrents
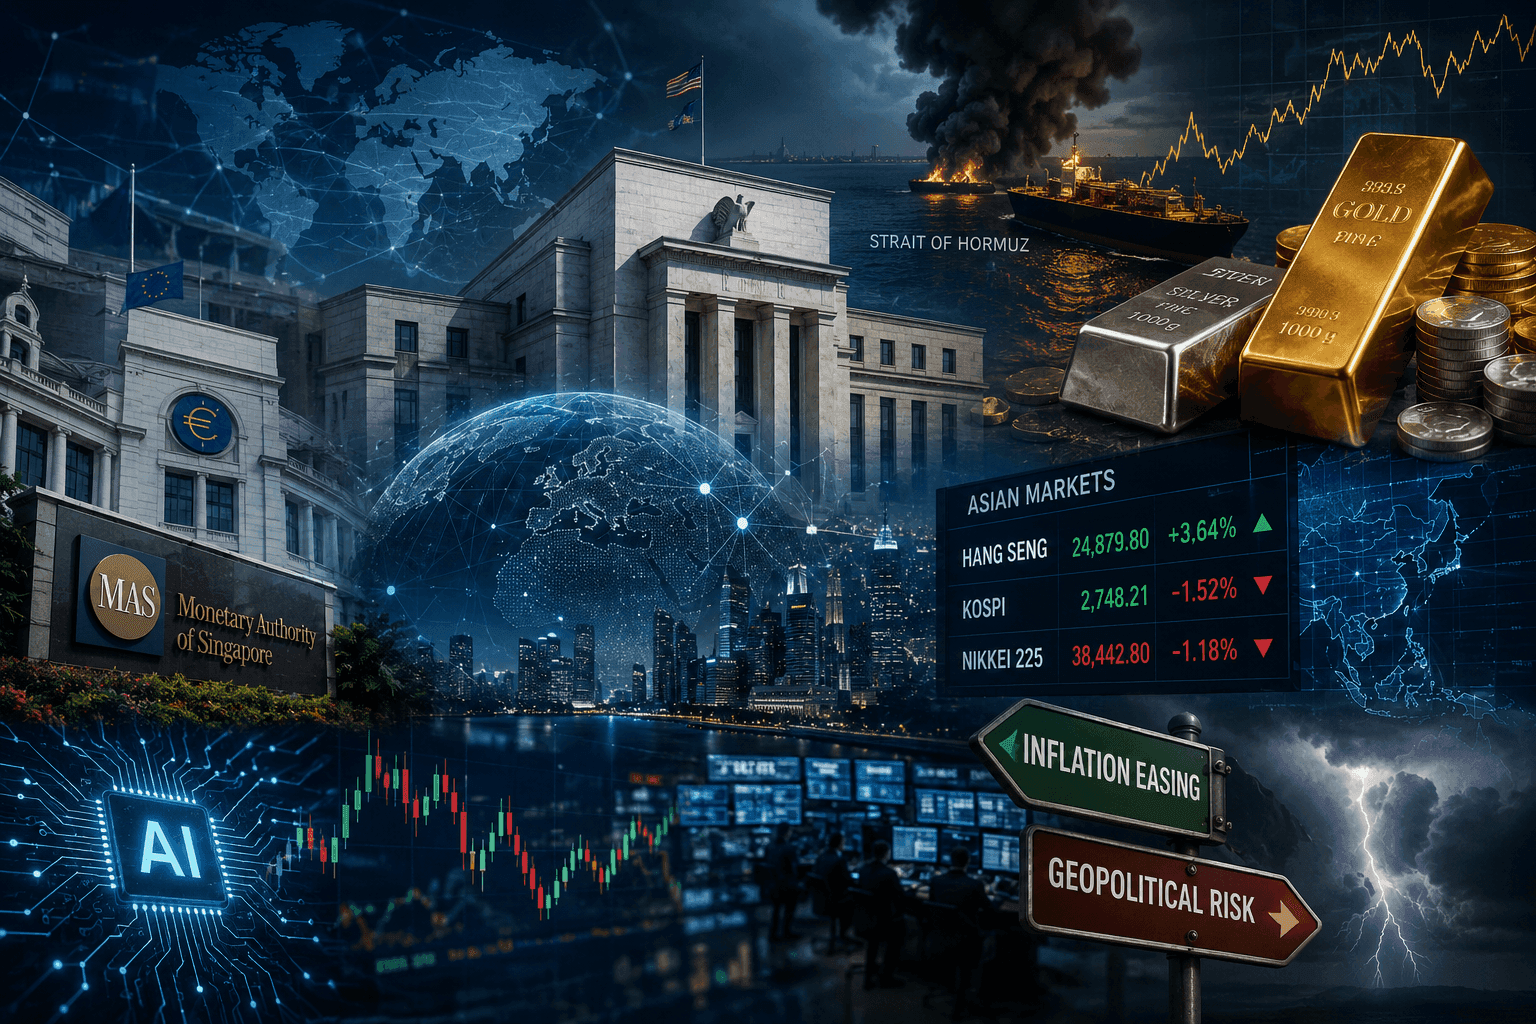
Central banks broadly maintained a data-dependent stance through the period and remained watchful even as global energy-driven inflation eased. The Federal Reserve reaffirmed its commitment to price stability even as growth prospects softened, while the European Central Bank similarly balanced improving headline inflation against still-elevated services prices. Closer to home, the Monetary Authority of Singapore raised its 2026 core inflation forecast on concerns that persistent price pressures could dampen household spending. The Hormuz disruption has driven inflation fears that outweigh traditional safe-haven demand. Gold and silver have moved in an unusual, counterintuitive pattern, falling rather than rallying as fighting escalated. In equities, investor sentiment shifted markedly as the AI-led rally that dominated the first half of the year gave way to a bout of volatility, prompting some rotation into value and cyclicals. Asian equities showed sharp dispersion rather than uniform resilience. In July 2026, Hong Kong’s Hang Seng emerged as the standout performer on continued strength in Chinese technology and AI names, while South Korea’s Kospi and Japan’s Nikkei slipped from June’s rebound as the memory-chip optimism and AI trade cooled. Looking ahead, markets remain caught between two competing narratives, a genuine easing of geopolitical and energy-driven inflation pressure, against the risk of renewed hostilities or a resurgence in AI-related volatility, which could quickly reverse recent gains in sentiment and reprice rate expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.
2026 June Market Outlook: From AI-Led Momentum to Persistent Uncertainty—A Disciplined Path Forward
Stronger than expected inflation in the US led newly installed Fed Chair Kevin Warsh to reinforce expectations that any rate cut is more likely in late 2026 or into 2027. Despite this hawkish view, US equities pushed to fresh highs, led by technology stocks. This period also saw Space Exploration Technologies Corp.’s (“SpaceX”) record-setting initial public offering, becoming a focal point for risk appetite and growth sentiment, which further amplified market enthusiasm. In the near term, the success of the SpaceX listing is likely to add further liquidity into space, artificial intelligence (“AI”) infrastructure and adjacent sectors. Investor sentiment remains heavily concentrated in AI-related and technology names, and some investors view the Asian market as a way to increase exposure at more attractive valuations than US technology leaders. Strong momentum in Asia is led by Korea, Taiwan and Japan, which play a central role in the AI and memory chip supply chain. On the other hand, China continues to lag even with incremental policy support. In other key markets, UK equities underperformed their peers, and Eurozone technology stocks performed moderately amid weak macroeconomic data, where the pullback in oil prices eased some inflationary pressure. Markets remain highly sensitive to developments in the Strait of Hormuz, where disruptions and the current partial normalisation of shipping through the strait weigh on energy prices and inflation expectations. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macroeconomic uncertainty.
2026 May Market Outlook: From Record Highs to Rising Uncertainty—A Selective Path Forward
Major indices have reached new highs since the March dip. Strong corporate earnings have reinforced investor confidence and sustained the ongoing risk-on rotation into AI-related stocks. The technology sector now represents a larger share on the MSCI Emerging Markets Index than the S&P 500, underscoring the central role of Taiwan and South Korea in the AI supply chain. With inflation still elevated and growth looking uneven across regions, central banks are balancing financial stability and energy-driven price pressures. Expectations for rate cuts have been pushed out or replaced by further tightening of monetary policy. The new Federal Reserve Chair, Kevin Warsh, known to favour rate cuts, faces inflationary pressures in the US economy that work against the dovish narrative, making rate cuts unlikely. Other central banks, such as the Bank of Japan and the European Central Bank have kept its policy unchanged, but with upward revisions to inflation forecasts, investors expect rate hikes this year. Though markets have appeared resilient to geopolitical shocks, the continuation of the Strait of Hormuz blockage can dampen economic activity through supply chain disruption and entrenching inflationary pressures. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macro uncertainty.
2026 April Market Outlook: From Conflict Shock to Market Strength — What’s Driving the Recovery
Major indices across the countries tumbled in March but abruptly spiked in April upon the announcement of US-Iran peace talks, though the US Navy continues its blockade of the Strait of Hormuz. Record highs in the tech-heavy S&P 500 and strong US corporate earnings reaffirm the market’s resilience throughout the conflict, particularly for demand in technology. Similarly, Asian markets tracked US gains and rallied in April; South Korea’s Kospi and Japan’s Nikkei were also driven by technology related optimism and de-escalation relief. Singapore’s central bank tightened monetary policy while the Bank of Japan cooled rate hike expectations. The situation in China remains mixed with continued weak domestic demand and an ongoing property sector drag, while local banks have outpaced broader market since the war broke out. As markets rebounded and risk sentiment improved in April, we remain highly selective in stock selection while diversifying across markets, maintaining our disciplined, bottom-up approach to portfolio construction.